ASEAN Macro Daily(Beta Mode)
BI Holds Rate as Rupiah Gains on Safe-Haven Shift
Market Snapshot
| Asset | Level | Change |
|---|---|---|
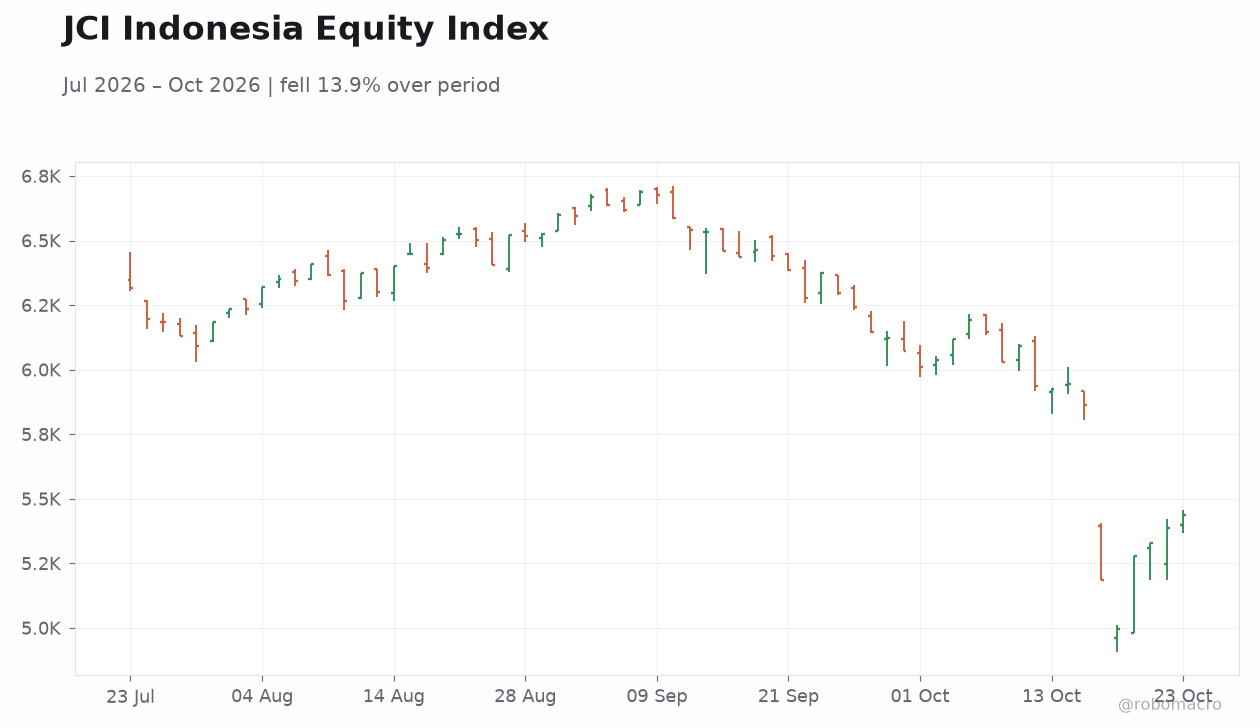
| JCI | 5,439.26 | +0.95% |
| KLCI | 1,611.56 | +0.21% |
| STI | 5,422.16 | +0.13% |
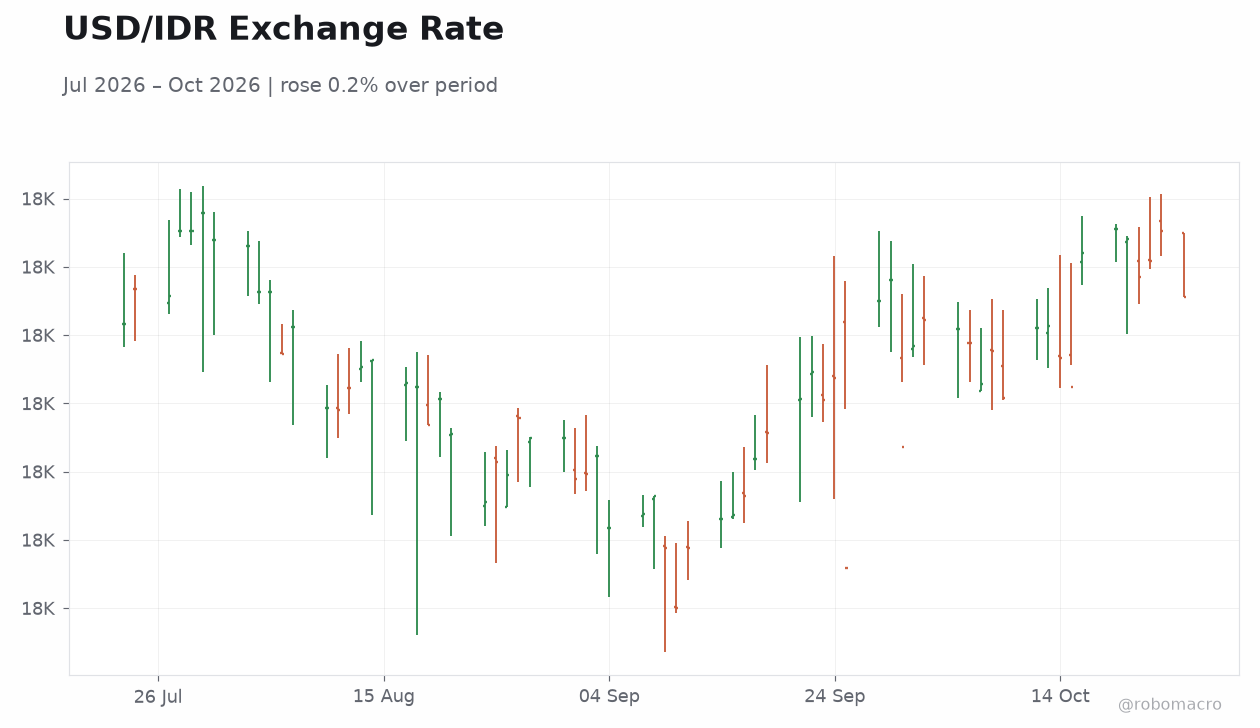
| USD/IDR | 17,956.00 | -0.54% |
| USD/THB | 33.74 | +0.07% |
| USD/MYR | 4.08 | +0.07% |
| USD/PHP | 63.58 | +0.26% |
| USD/SGD | 1.28 | +0.06% |
| Brent Crude | 111.70 | -4.30% |
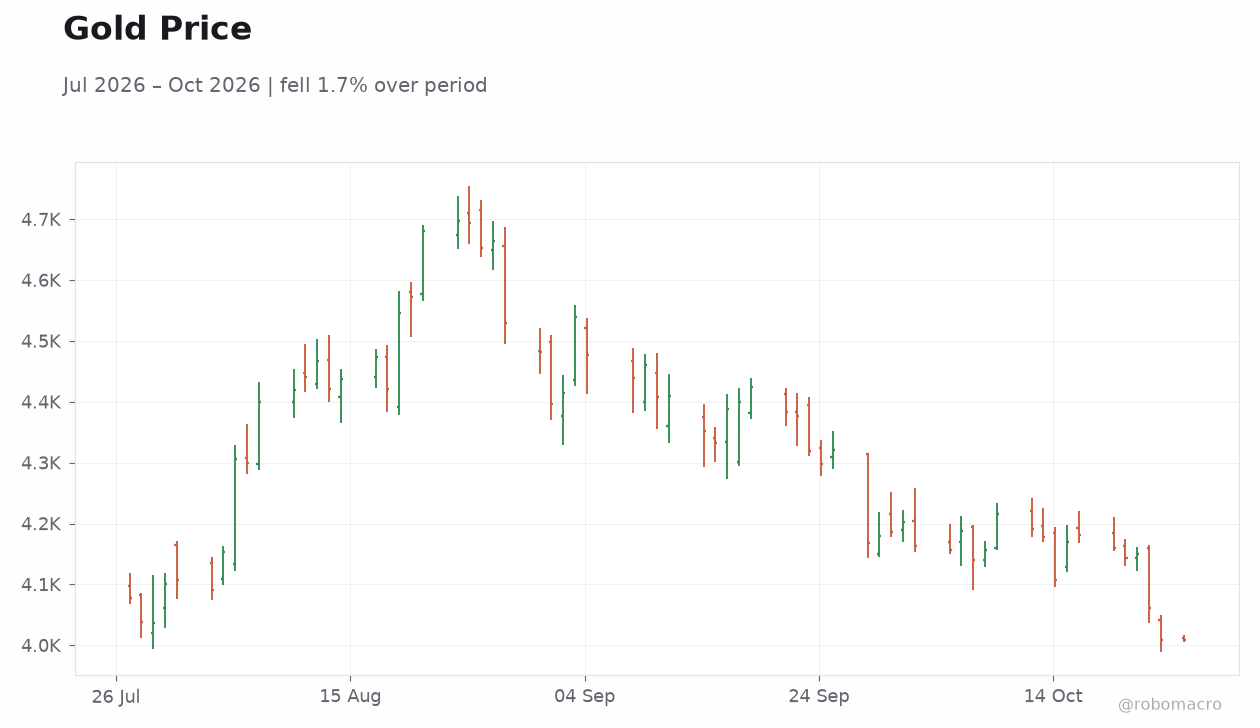
| Gold | 4,007.90 | +0.00% |
| Bitcoin | 80,370.54 | -0.52% |
| Indonesia 10Y Govt Yield | - | - |
| Thailand 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
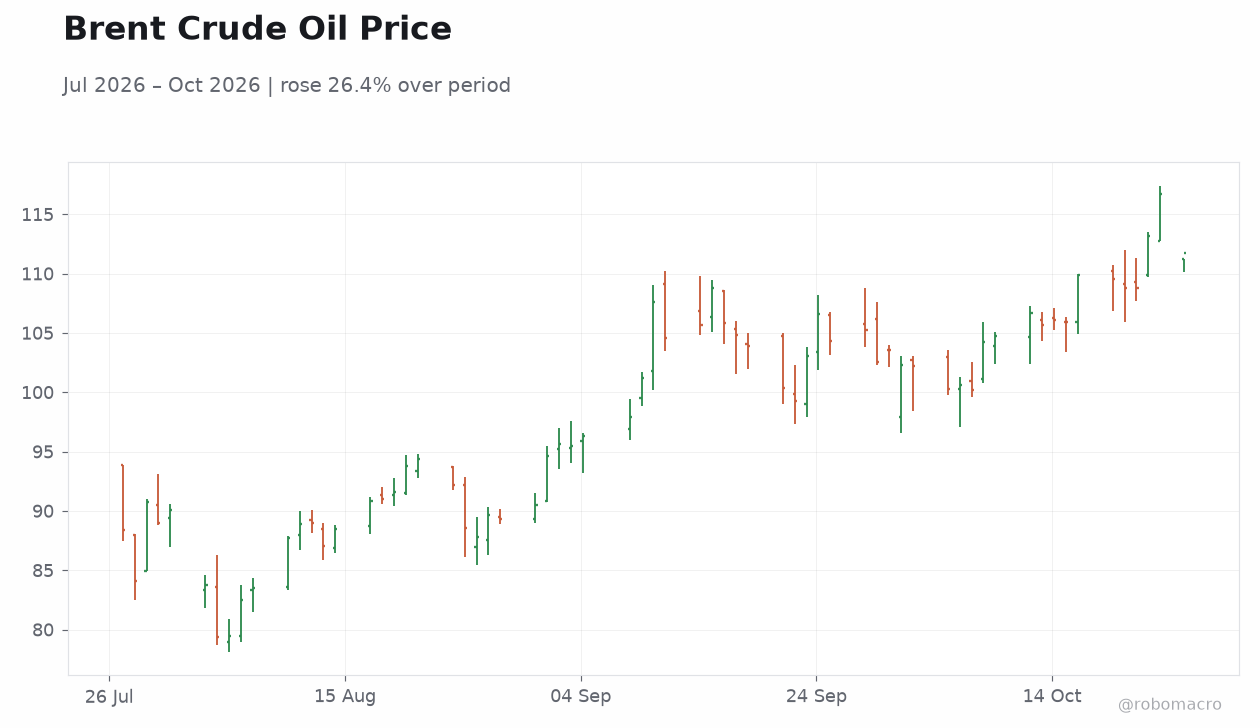 Brent Crude Oil Price | Type: market_hloc | USD per Barrel: 111.7 (2026-10-25) | Range: 79.36–116.7 | Trend(5pt): 88.36,91.02,107.6,102.2,111.7
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Bank Indonesia keeps policy rate steady at 5.75% while rupiah strengthens 0.54% against the dollar.
- Regional equities advance modestly with JCI rising 0.95% and KLCI up 0.21%.
- Malaysia and Thailand join Singapore digital settlement initiative amid quiet data calendar.
Yesterday's Recap
Indonesia dominated ASEAN moves as Bank Indonesia held its benchmark rate at 5.75% despite MSCI downgrade concerns weighing on sentiment. The rupiah appreciated against the dollar as safe-haven demand shifted toward Indonesian assets, lifting USD/IDR to 17,956. Equity markets responded positively, with the JCI climbing 0.95% while the KLCI and STI posted smaller gains of 0.21% and 0.13%.
Brent crude fell sharply, easing imported inflation risks for net importers across the region. Malaysia and Thailand advanced cooperation with Singapore on digital money settlement, signaling deeper financial integration. Creative economy initiatives in Indonesia received renewed policy attention but had limited immediate market impact.
No major data prints emerged from Thailand, Malaysia, Philippines, Singapore or Vietnam. Regional bond markets showed limited movement, with yields data unavailable in the snapshot. External factors such as steady gold prices near 4,008 and a modest Bitcoin decline reinforced selective risk appetite rather than broad dollar weakness.
The Day Ahead
The regional calendar remains light with no scheduled releases across the six economies. Markets will monitor follow-through on Bank Indonesia’s policy stance and any updates on MSCI index decisions affecting Indonesia. Traders may also track progress on Malaysia-Thailand-Singapore digital settlement talks and potential statements from the Bank of Thailand or Bank Negara Malaysia.
External drivers such as Brent crude volatility and US dollar direction will likely set the tone for ASEAN currencies. Vietnam and Philippines data flows stay quiet, leaving focus on Indonesia and cross-border financial initiatives. Policy continuity at 2.75% in Malaysia and 1.00% in Thailand provides a stable backdrop for any follow-up commentary on growth support.
Other Economic Notes
Commodity price swings, especially the sharp drop in Brent, offer relief to ASEAN importers while pressuring exporters in Indonesia and Malaysia. Supply-chain realignment from China continues to support manufacturing FDI into Vietnam and Thailand. Digital finance cooperation among Malaysia, Thailand and Singapore highlights a structural push toward regional payment efficiency.
↓ p.2