ASEAN Macro Daily(Beta Mode)
Rupiah Falls After GDP Beat; BSP CPI Jumps
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| JCI | 4,919.77 | +0.32% |
| KLCI | 1,616.56 | -0.33% |
| STI | 5,268.63 | -0.01% |
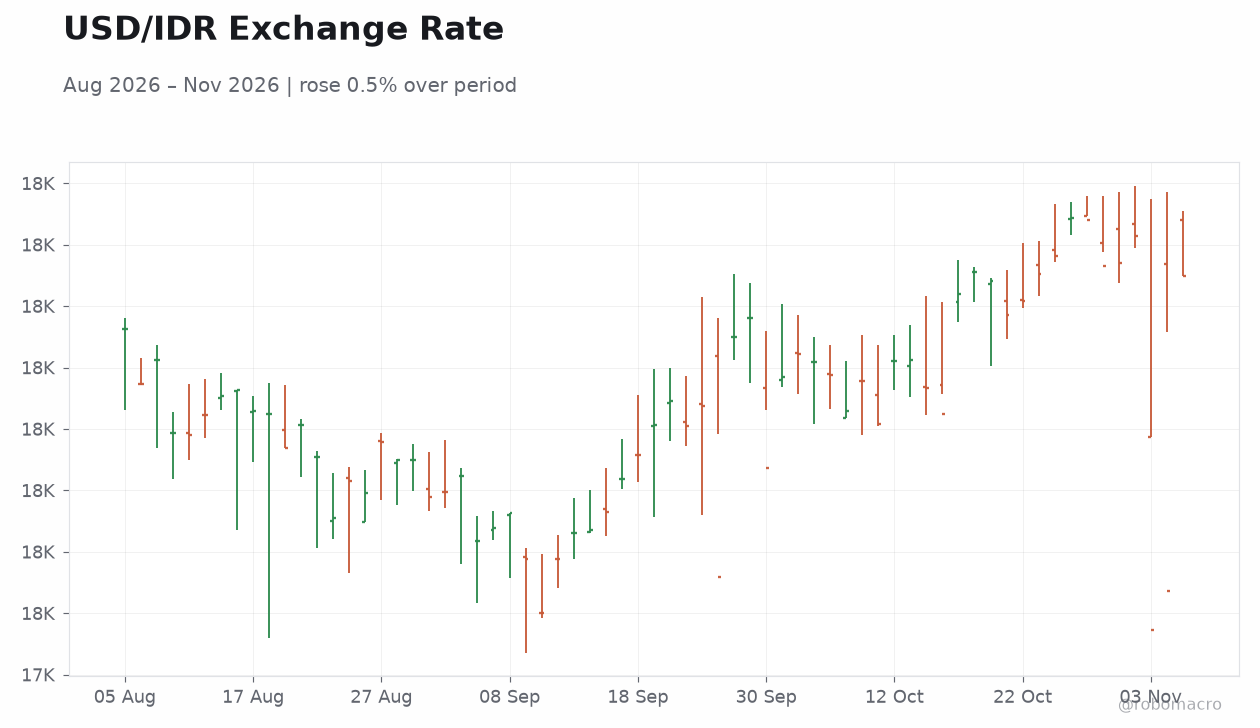
| USD/IDR | 18,049.00 | +2.92% |
| USD/THB | 33.42 | -0.98% |
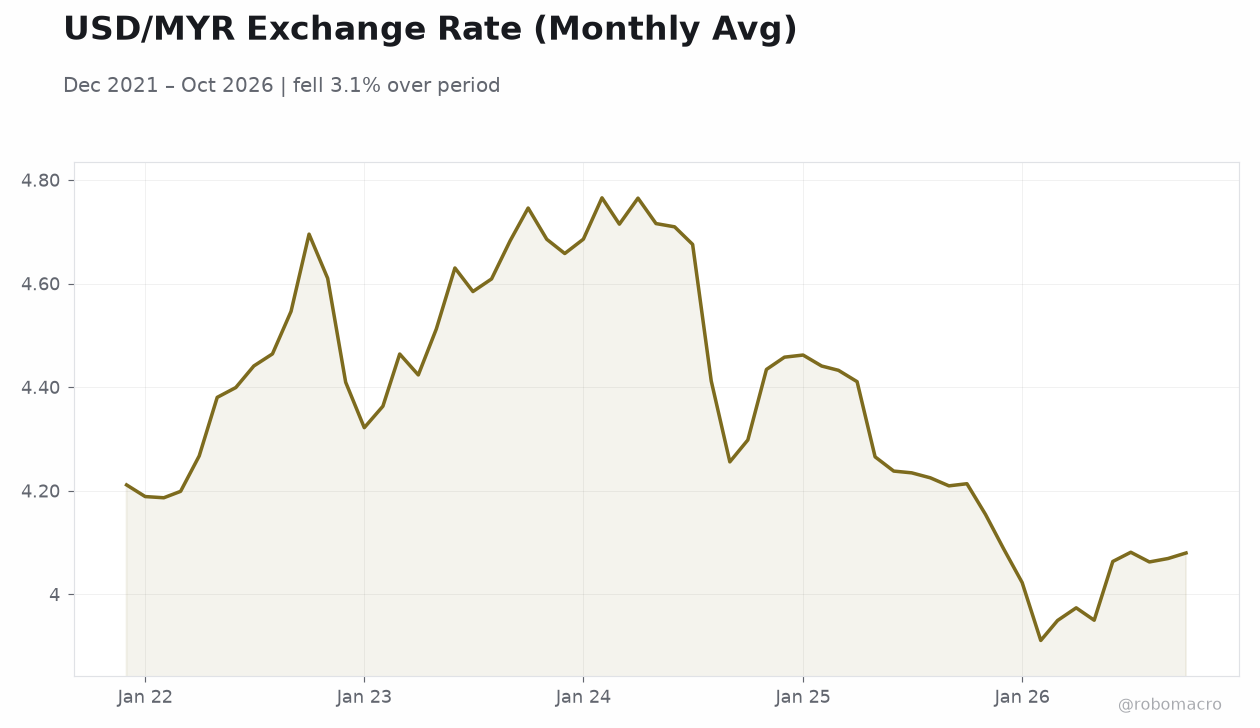
| USD/MYR | 4.04 | -0.75% |
| USD/PHP | 62.96 | -0.64% |
| USD/SGD | 1.28 | -0.22% |
| Brent Crude | 99.25 | +4.89% |
| Gold | 4,097.90 | +0.61% |
| Bitcoin | 75,922.00 | -5.58% |
| Indonesia 10Y Govt Yield | - | - |
| Thailand 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Year-over-Year | 7.20 | 7.60 | 7.80 |
| GDP Growth Year-over-Year | 5.29 | 5.20 | 5.47 |
| Central Bank Interest Rate Decision | 2.75 | 2.75 | 2.75 |
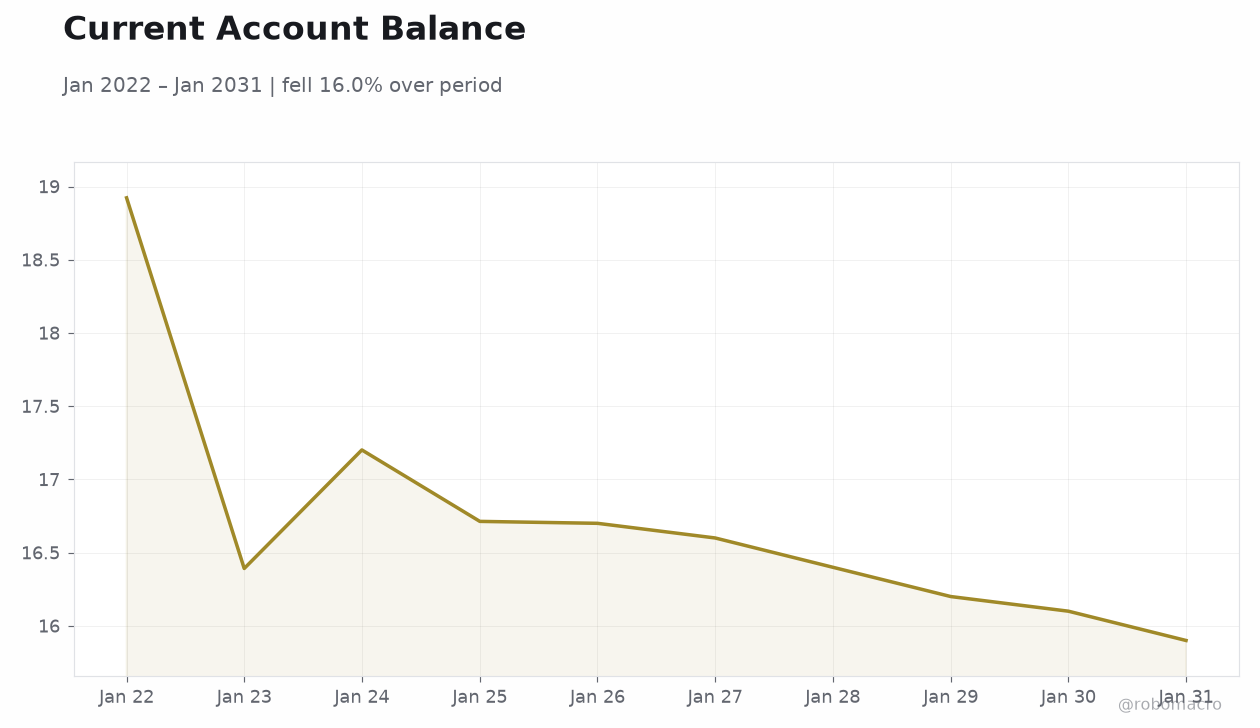 Current Account Balance | Type: macro_line | Current Account Balance: 15.9 (2031-01-01) | Range: 15.9–18.92 | Trend(6pt): 18.92,17.2,16.7,16.4,16.1,15.9
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Headline Unemployment Rate | 5.30 | - | 20:00 |
- Indonesia's Q3 GDP beat at 5.47% YoY, but the rupiah slumped nearly 3% to 18,049/USD as global pressures and job-market concerns offset the growth surprise.
- Philippines inflation accelerated to 7.8% YoY, above the 7.6% consensus, keeping BSP under pressure to tighten further.
- BNM held its overnight policy rate at 2.75%, with the ringgit extending gains after the decision.
Yesterday's Recap
Indonesia's Q3 GDP printed at 5.47% YoY, beating the 5.2% consensus and accelerating from 5.29% prior, yet the rupiah fell 2.92% to 18,049/USD — its weakest level on record — as global pressures and a soft job market overshadowed the growth beat. The Philippines reported November inflation at 7.8% YoY, above the 7.6% consensus and up from 7.2% prior, underscoring persistent price pressures. Bank Negara Malaysia held its policy rate at 2.75%, in line with expectations, and the ringgit subsequently extended gains, closing 0.75% stronger at 4.04/USD.
Regional equities were mixed: the JCI rose 0.32% to 4,919.77 while the KLCI slipped 0.33% and the STI was flat. The baht firmed 0.98% to 33.42/USD, and the peso gained 0.64% to 62.96. Brent crude surged 4.89% to $99.25/bbl, adding to imported inflation risks across the region.
The Day Ahead
The Philippines releases its headline unemployment rate at 20:00 ET, with the prior reading at 5.3%; no consensus is published, so the print will be watched for signs of labor-market softening amid elevated inflation. Beyond the calendar, markets will continue to digest the divergence between Indonesia's strong growth print and its currency weakness, with attention on whether BI signals further FX defense ahead of its November 18 meeting. Singapore and Vietnam have no scheduled releases, leaving regional focus on Philippine labor data and any follow-through in currency markets after the rupiah's sharp move.
Thailand's S&P affirmation at BBB+ with a stable outlook should support sentiment in Thai assets.
Other Economic Notes
Thailand's informal economy is estimated at roughly 48% of GDP, with grey money at 13%, per BoT research — a structural factor complicating tax policy and formal-sector growth measurement. S&P Global Ratings affirmed Thailand's sovereign rating at BBB+ with a stable outlook, reinforcing the sovereign's investment-grade standing. Thailand's rice exports to ASEAN doubled year-to-date through September, rising 109% to about 1.25 million tonnes, reflecting stronger regional demand.
Indonesia's growth beat is being questioned by analysts who flag weak rupiah dynamics and a job crisis as tests of the headline number's durability. ↓ p.2