Andeans Macro Daily(Beta Mode)
Colombia Rate Hold Looms as Copper Slides
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
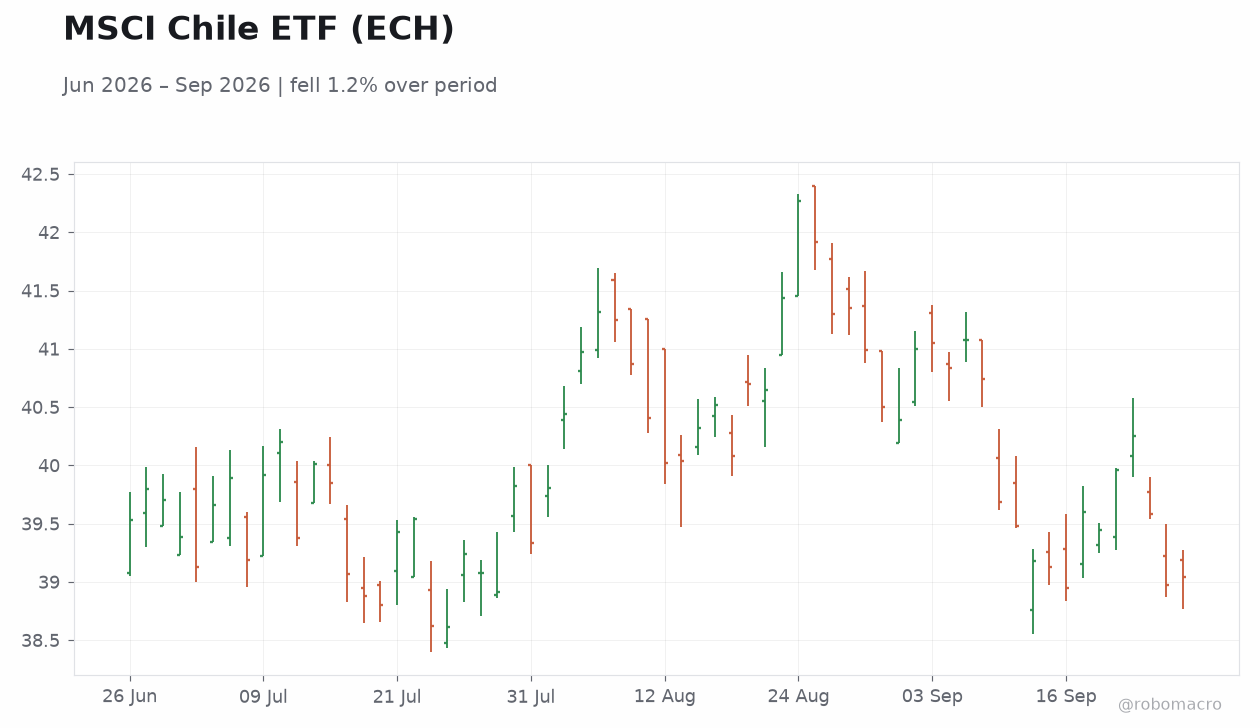
| MSCI Chile | 39.04 | +0.18% |
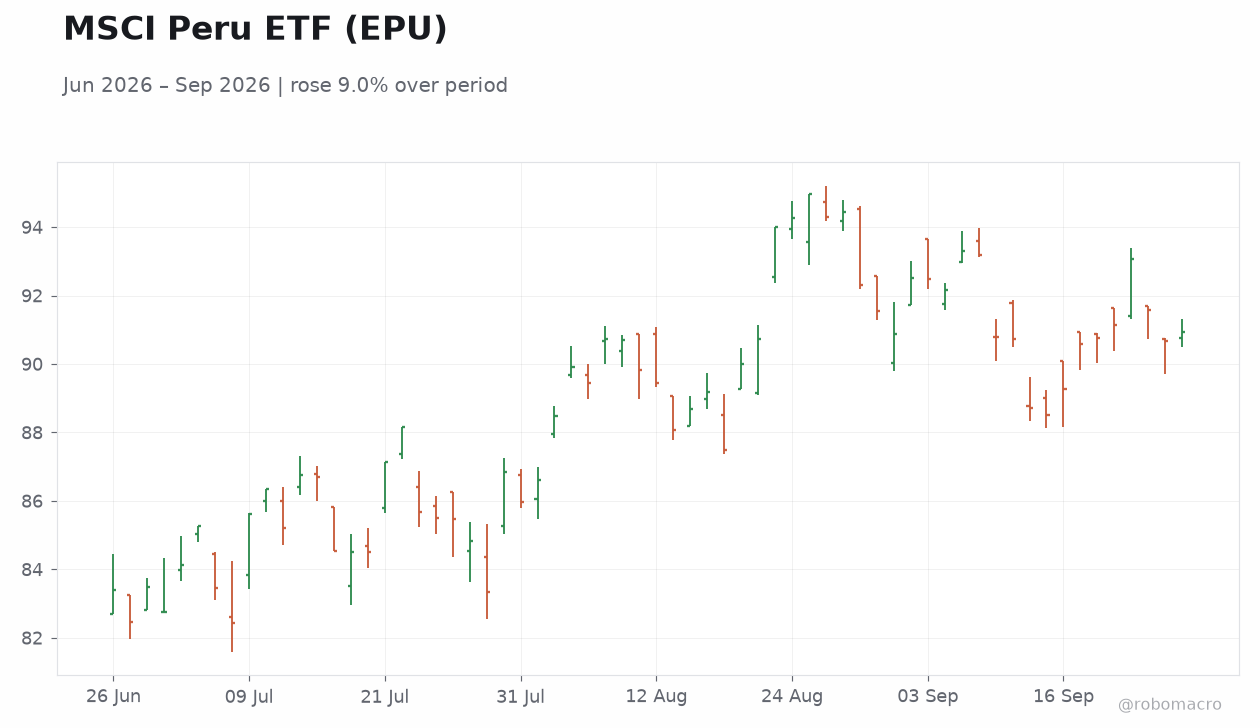
| MSCI Peru | 90.94 | +0.29% |
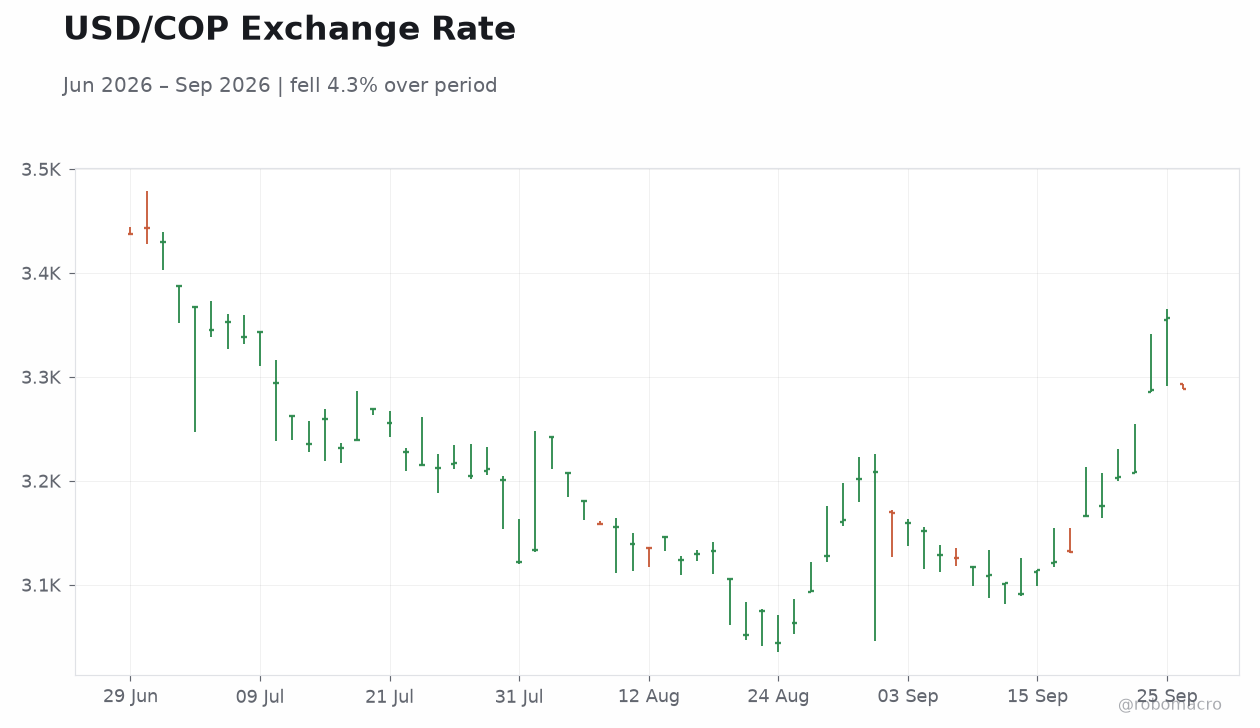
| USD/COP | 3,288.50 | -2.03% |
| USD/CLP | 967.00 | +0.46% |
| USD/PEN | 3.40 | +3.39% |
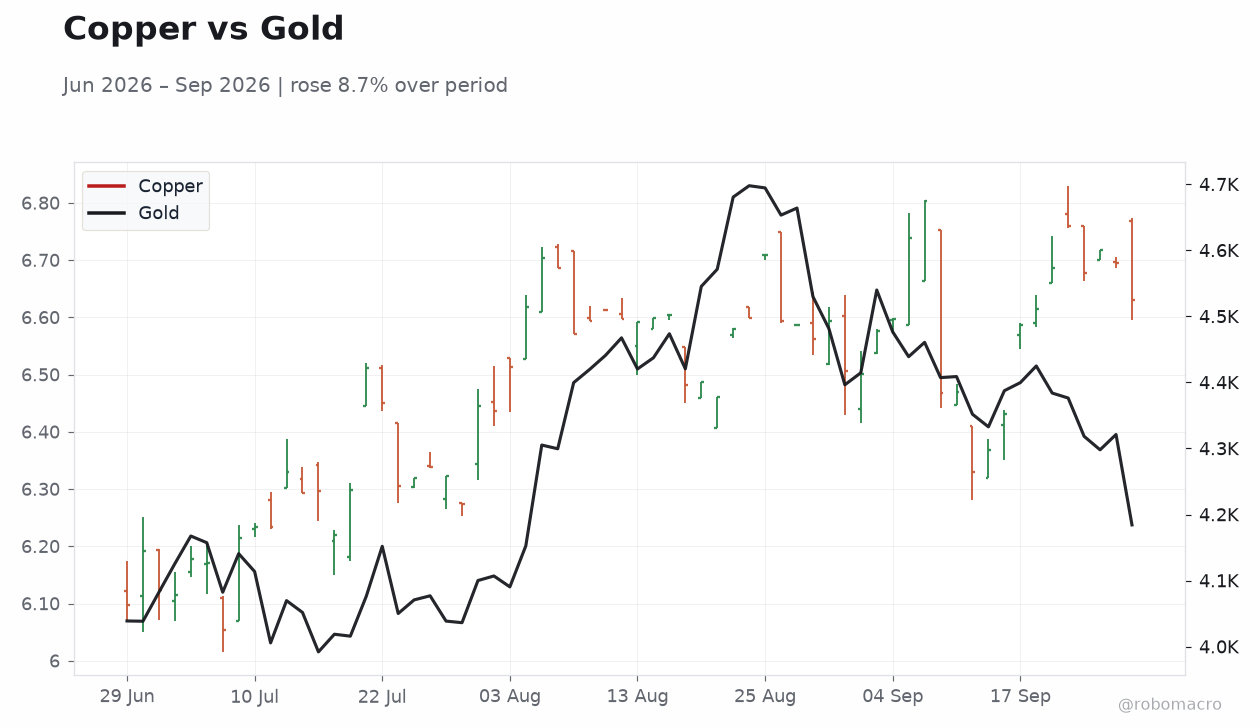
| Copper | 6.63 | -0.99% |
| Gold | 4,184.90 | -3.15% |
| Brent Crude | 101.03 | -3.15% |
| Bitcoin | 82,924.93 | -1.82% |
| Colombia 10Y Govt Yield | 12.91% | +16 bp |
| Peru 10Y Govt Yield | 6.67% | +15 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
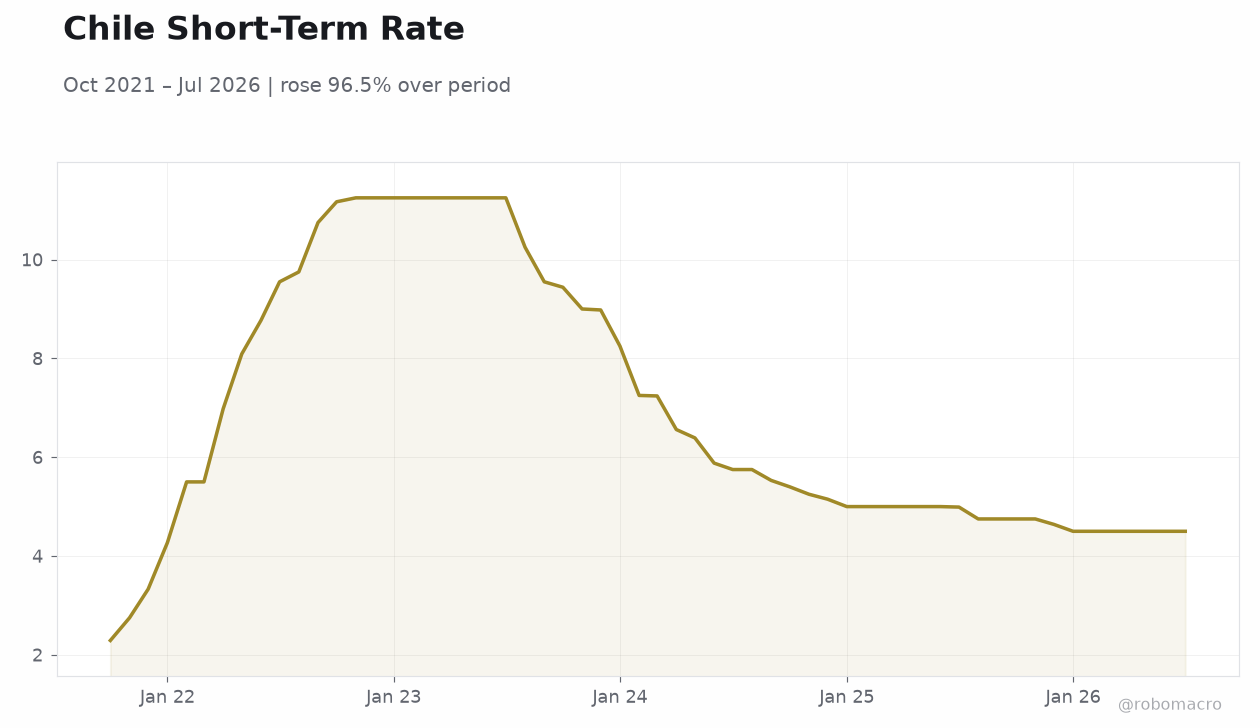 Chile Short-Term Rate | Type: macro_line | Policy Rate %: 4.5 (2026-07-01) | Range: 2.29–11.25 | Trend(5pt): 2.29,11.25,7.25,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Central Bank Interest Rate Decision | 12 | 12 | 10:00 |
- Colombia's BanRep set to hold policy rate at 12% on September 30 amid stable inflation outlook.
- MSCI Peru and Chile posted modest gains while copper fell 0.99% to 6.63, pressuring CLP and PEN.
- Colombia 10-year yield rose 16 bp to 12.91% and Peru's climbed 15 bp to 6.67% as USD/COP eased 2.03%.
Yesterday's Recap
Equity markets in the Andean region recorded limited advances on September 27. MSCI Peru advanced 0.29% to 90.94 while MSCI Chile rose 0.18% to 39.04; MSCI Colombia stayed flat at 9.02. Currency moves diverged sharply, with USD/PEN surging 3.39% to 3.40 and USD/CLP adding 0.46% to 967.00, whereas USD/COP declined 2.03% to 3,288.50.
Commodity prices fell across the board, as copper dropped 0.99% to 6.63, gold declined 3.15% to 4,184.90 and Brent crude slipped 3.15% to 101.03. Sovereign yields moved higher, lifting Colombia's 10-year yield 16 bp to 12.91% and Peru's 10-year yield 15 bp to 6.67%. No macroeconomic data releases occurred in Colombia, Chile or Peru, leaving market pricing driven by external commodity and dollar flows.
The absence of local prints kept attention on upcoming BanRep policy action and persistent commodity weakness. Copper's decline weighed directly on Chile and Peru fiscal balances given their reliance on mining royalties, while Brent's drop reduced Colombia's oil-related inflows and widened current-account pressure.
The Day Ahead
Markets await Colombia's Central Bank Interest Rate Decision scheduled for September 30 at 10:00 ET, with consensus pointing to an unchanged 12% rate. No other high-impact releases are listed for Chile or Peru over the next 24 hours. Traders will scrutinize any forward guidance from BanRep for signals on the persistence of its hawkish stance relative to regional peers.
Copper and oil price trajectories remain key external drivers for Chile's and Colombia's fiscal and external accounts. Local equity and FX desks are expected to position ahead of the decision, with limited domestic data risk otherwise. The committee is expected to vote to hold given the still-elevated inflation path and focus on credibility.
Other Economic Notes
Copper's decline directly threatens fiscal revenue in Chile and Peru, both major producers whose budgets rely on mining royalties and export taxes. Lower Brent prices reduce Colombia's oil-linked inflows, widening pressure on its current-account and fiscal balances. Regional equity indices showed resilience despite commodity weakness, suggesting investors continue to differentiate Andean assets from global risk-off moves.
↓ p.2