US Macro Daily(Beta Mode)
Equities Advance as 2Y Yield Jumps 14bp
Market Snapshot
| Asset | Level | Change |
|---|---|---|
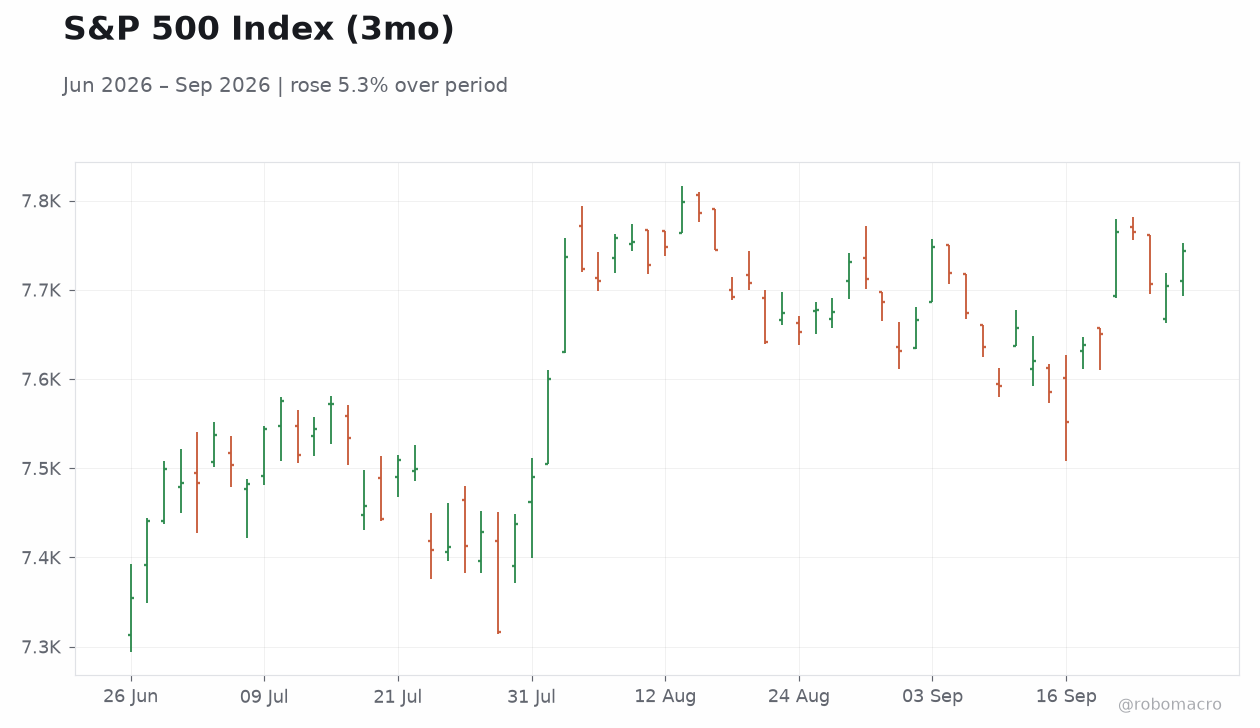
| S&P 500 | 7,743.41 | +0.51% |
| Nasdaq 100 | 30,608.13 | +0.42% |
| Dow Jones | 51,828.62 | +0.93% |
| Russell 2000 | 2,837.55 | +0.07% |
| USD/JPY | 157.05 | -1.11% |
| EUR/USD | 1.14 | +0.00% |
| GBP/USD | 1.33 | +0.33% |
| Gold | 4,189.80 | -3.04% |
| WTI Crude | 96.19 | +4.09% |
| Bitcoin | 82,951.20 | -1.78% |
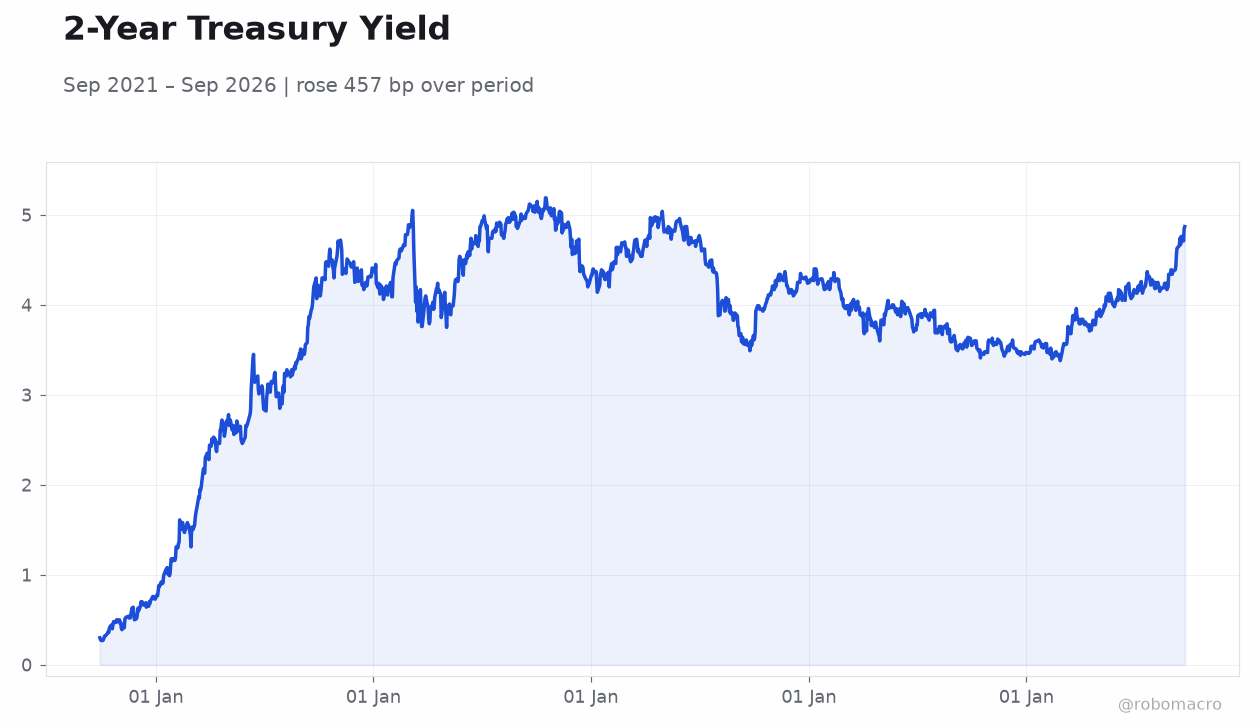
| US 2Y Treasury | 4.85% | +14 bp |
| US 10Y Treasury | 5.17% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
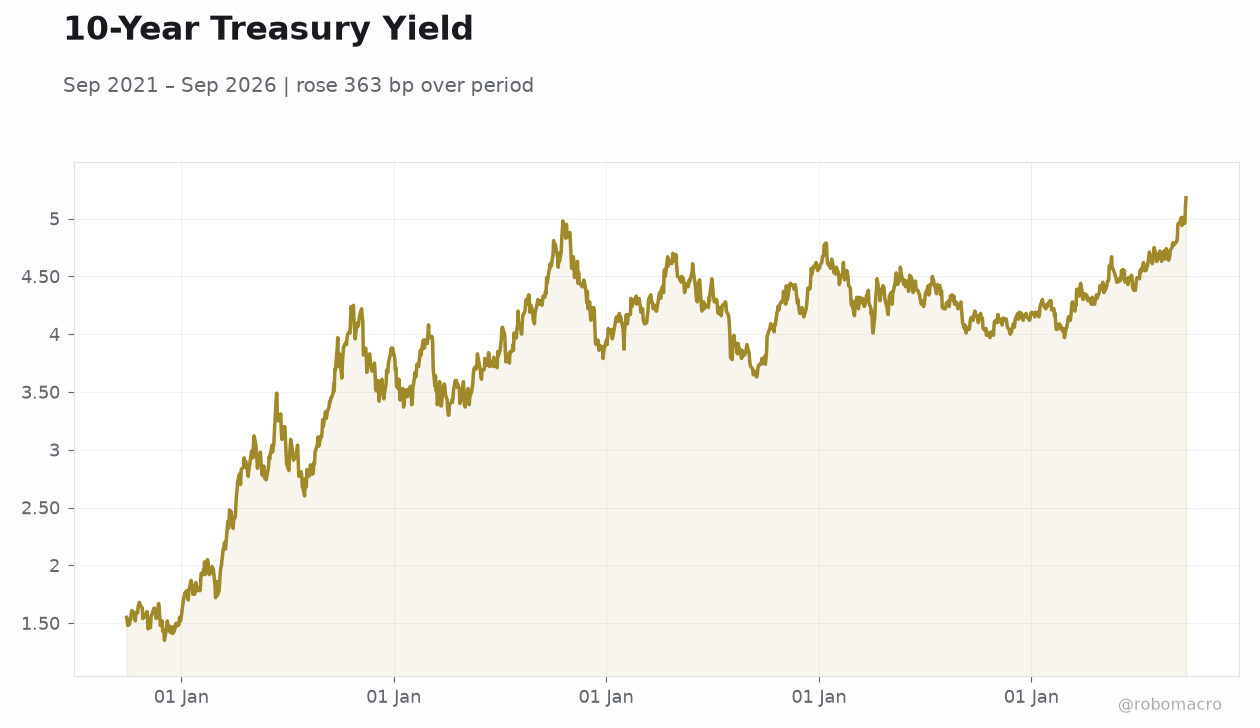 10-Year Treasury Yield | Type: macro_line | Yield %: 5.18 (2026-09-24) | Range: 1.35–5.18 | Trend(6pt): 1.55,3.83,4.2,4.26,5.11,5.18
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Speech by Fed's Bowman | - | - | 04:15 |
| Dallas Fed Manufacturing Index | 11.60 | - | 06:30 |
| Speech by Fed's Barkin | - | - | 09:30 |
| Tuesday (2026-09-29) | |||
| S&P/Case-Shiller Home Price Year-over-Year | 2.10 | 2.20 | 05:00 |
| JOLTs Job Openings | 7.3m | 7.2m | 06:00 |
| Cb Consumer Confidence | 89.40 | - | 06:00 |
| Fed Goolsbee Speech | - | - | 09:00 |
| Speech by Fed's Musalem | - | - | 09:30 |
| Speech by Fed's Williams | - | - | 10:00 |
- US equities rose with the Dow up 0.93% while the 2-year Treasury yield climbed 14 bp to 4.85%.
- No economic releases occurred yesterday as attention turns to Fed speeches and the Dallas Fed index today.
- China and the US agreed to cut tariffs on $60 billion of bilateral goods.
Yesterday's Recap
Equity indices posted solid gains on September 27. The S&P 500 closed at 7,743.41, up 0.51 percent, while the Nasdaq 100 rose 0.42 percent to 30,608.13. The Dow Jones advanced 0.93 percent to 51,828.62 and the Russell 2000 edged 0.07 percent higher to 2,837.55.
WTI crude surged 4.09 percent to 96.19 as gold fell 3.04 percent to 4,189.80. The 2-year Treasury yield rose 14 basis points to 4.85 percent while the 10-year yield eased 1 basis point to 5.17 percent. USD/JPY declined 1.11 percent to 157.05 and EUR/USD held steady at 1.14.
No US data prints or Fed communications drove the session.
The Day Ahead
Markets will focus on three medium-impact events. Fed Governor Michelle Bowman speaks at 4:15 ET followed by Dallas Fed President Thomas Barkin at 9:30 ET. The Dallas Fed Manufacturing Index is scheduled for 6:30 ET with the prior reading at 11.6.
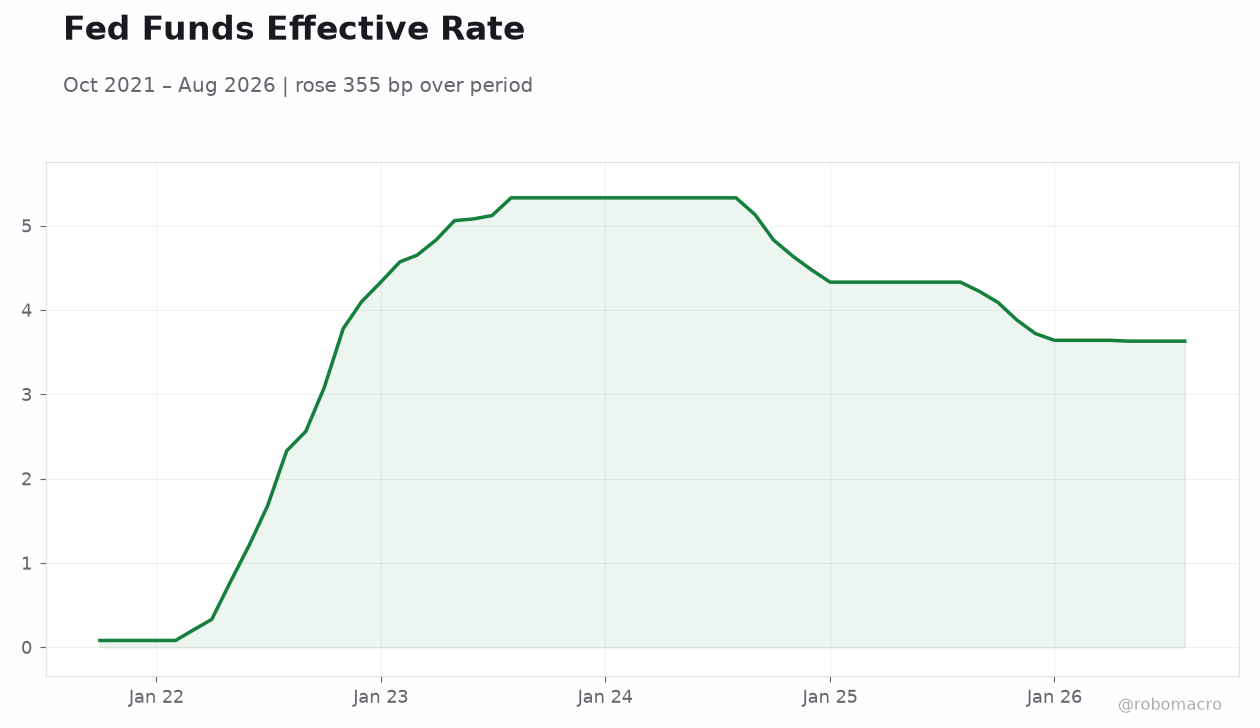
These Fed remarks will be parsed for any updates on inflation persistence and labor-market balance. The regional manufacturing gauge offers limited national insight but can influence short-term rate expectations. Treasury yields and equity futures will react to any shifts in tone from the speakers.
Other Economic Notes
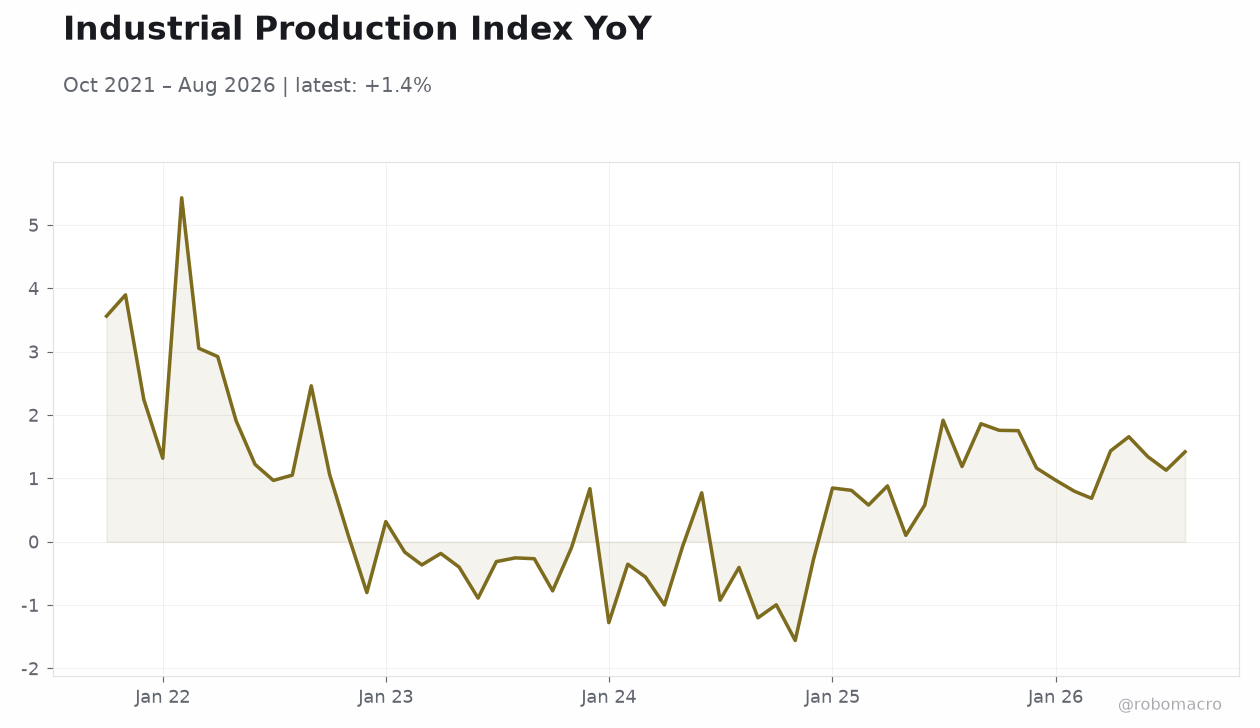
US consumer sentiment fell in September to a four-month low on concerns over prices and the economic outlook. Soaring bond yields have yet to restrain activity despite the 10-year yield near 5.17 percent. Retail sales grew 6.01 percent year-over-year through August while unemployment stood at 4.10 percent.
GDP expanded 1.50 percent quarter-over-quarter annualized in the first quarter and 2.10 percent year-over-year. Core PCE inflation remains above the Fed’s target with the August CPI print at 3.40 percent year-over-year.
Global Macro News
China and the United States agreed to reduce tariffs on $60 billion of mutual imports, easing some bilateral trade tension. India’s foreign-exchange reserves fell the most in two years as the central bank defended the rupee amid higher oil prices. ↓ p.2