Andeans Macro Daily(Beta Mode)
BanRep Holds at 12% as Chile, Peru Equities Slip
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
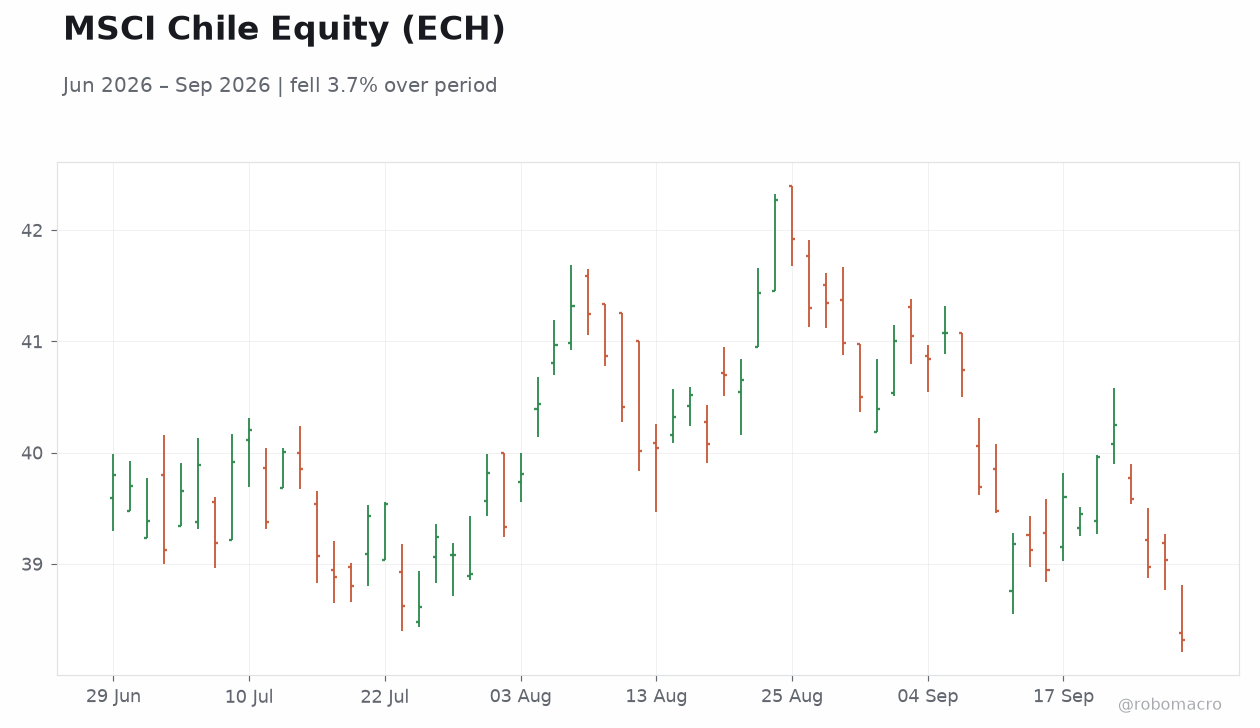
| MSCI Chile | 38.32 | -1.84% |
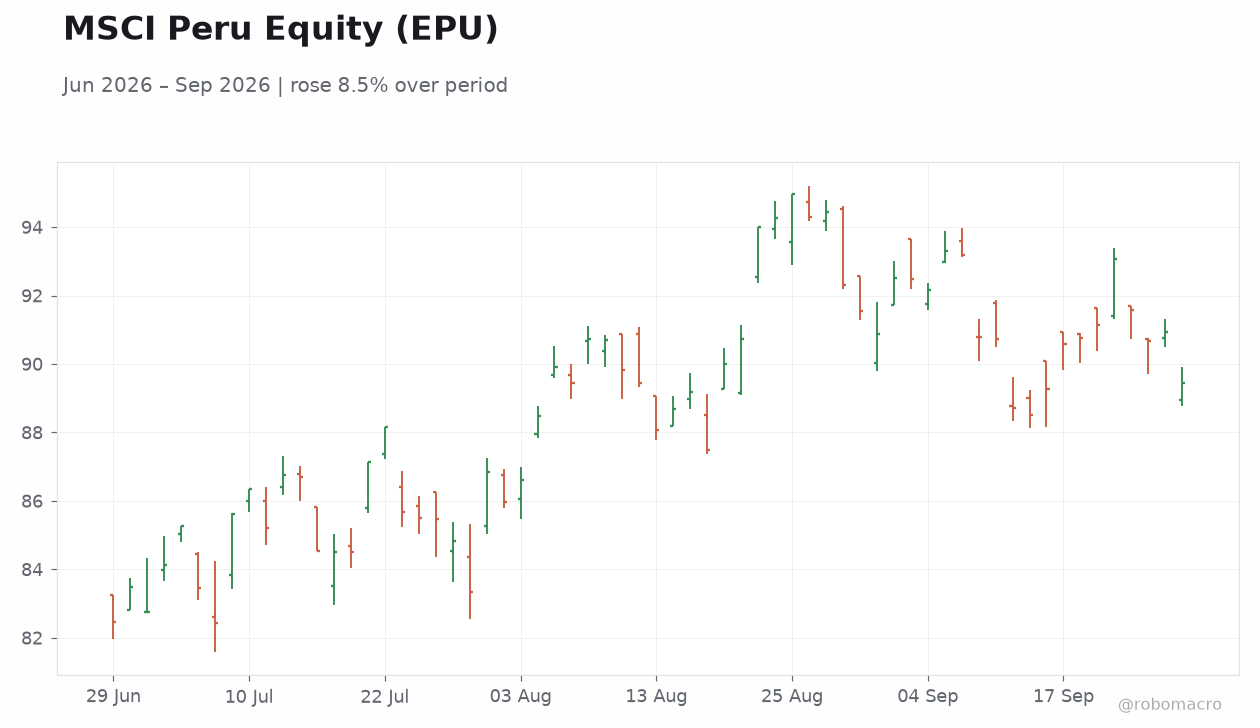
| MSCI Peru | 89.44 | -1.65% |
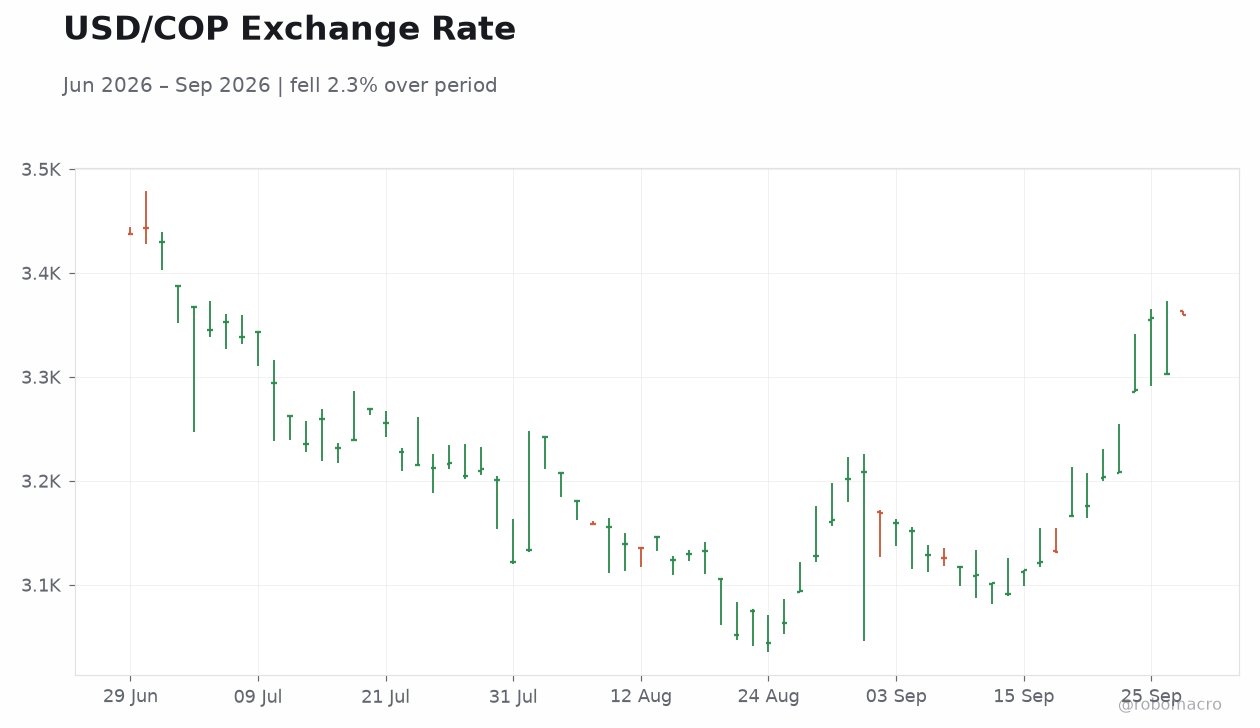
| USD/COP | 3,359.23 | +1.70% |
| USD/CLP | 963.95 | +0.30% |
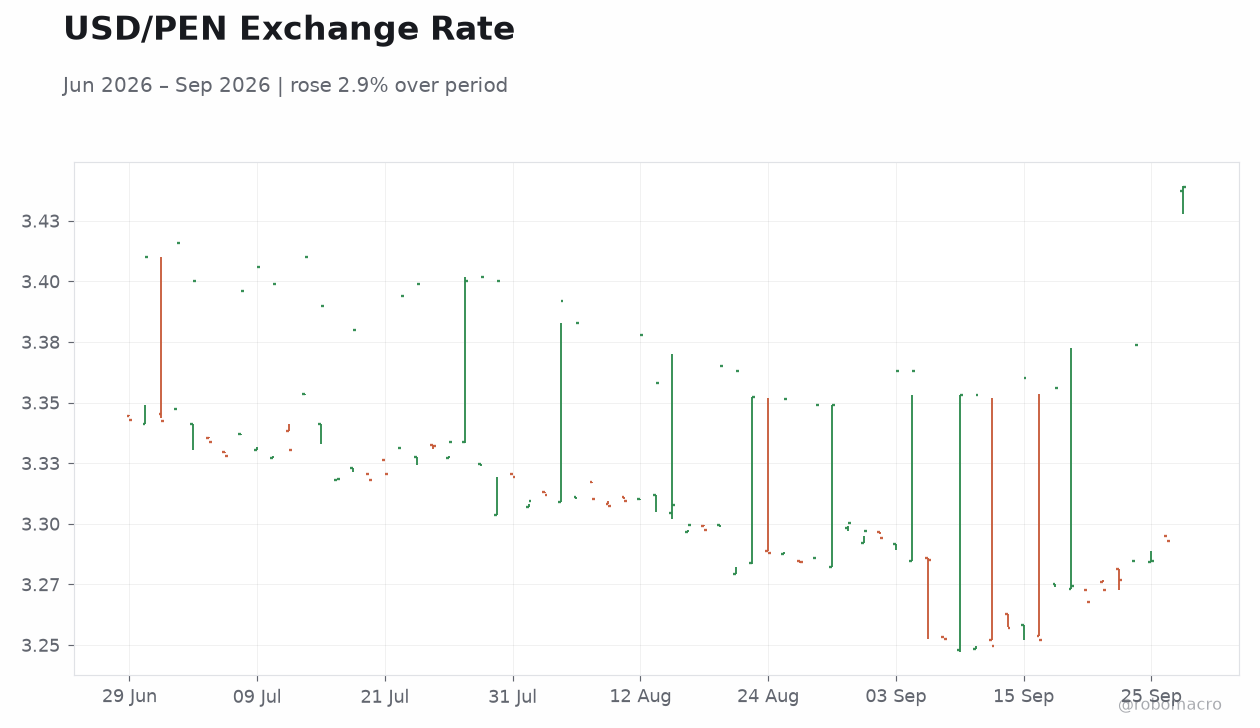
| USD/PEN | 3.44 | +4.44% |
| Copper | 6.62 | +0.86% |
| Gold | 4,187.60 | +0.46% |
| Brent Crude | 96.83 | -8.03% |
| Bitcoin | 83,970.62 | +0.56% |
| Colombia 10Y Govt Yield | - | - |
| Peru 10Y Govt Yield | 6.67% | +15 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
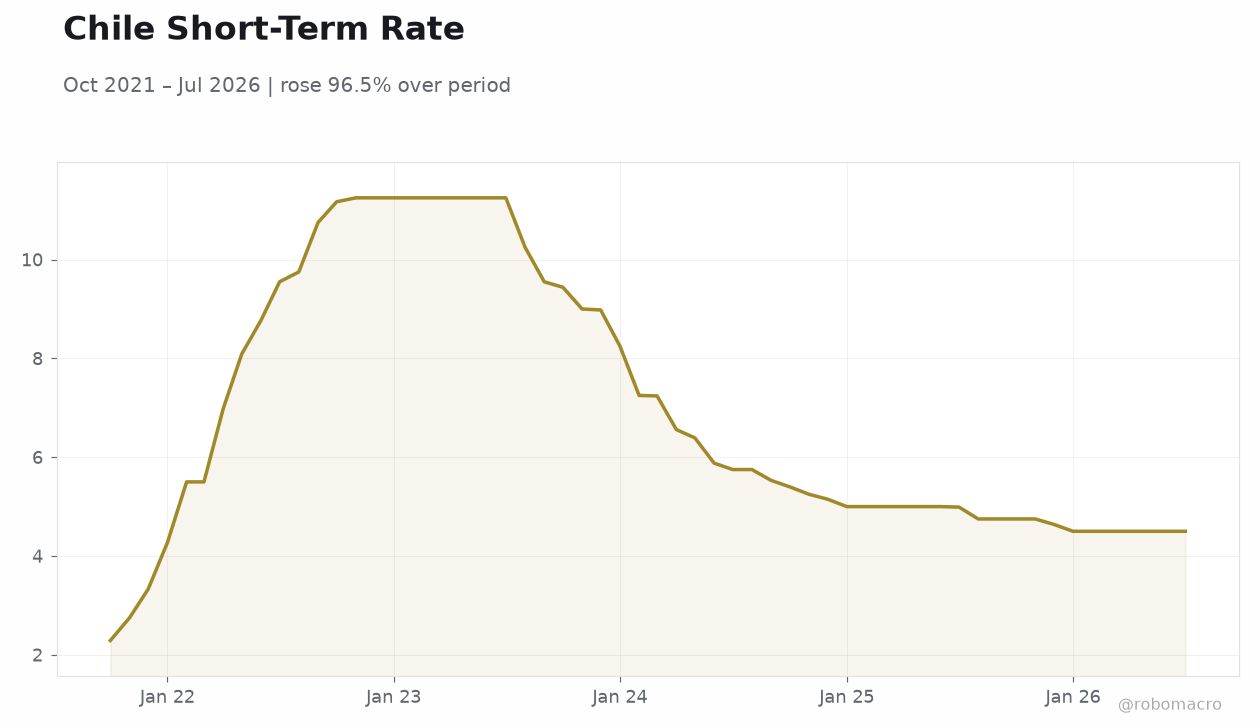 Chile Short-Term Rate | Type: macro_line | Short-Term Rate %: 4.5 (2026-07-01) | Range: 2.29–11.25 | Trend(5pt): 2.29,11.25,7.25,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Central Bank Interest Rate Decision | 12 | 12 | 10:00 |
| Wednesday (2026-09-30) | |||
| Central Bank Interest Rate Decision | 12 | 12 | 10:00 |
- BanRep expected to hold policy rate at 12.00% on September 30, matching consensus and prior level.
- MSCI Chile fell 1.84% to 38.32 and MSCI Peru declined 1.65% to 89.44, while USD/COP rose 1.70% to 3,359.23 and USD/PEN jumped 4.44% to 3.44.
- Copper advanced 0.86% to 6.62 on Chile mine strike concerns, while Peru 10-year yield climbed 15 bp to 6.67%.
Yesterday's Recap
Equity markets across the Andean bloc posted losses on September 28, with MSCI Chile dropping 1.84% to 38.32 and MSCI Peru falling 1.65% to 89.44 while MSCI Colombia held flat at 9.02. Currencies weakened against the dollar, as USD/COP rose 1.70% to 3,359.23, USD/CLP gained 0.30% to 963.95, and USD/PEN surged 4.44% to 3.44. Peru’s 10-year government yield increased 15 bp to 6.67%.
Copper prices climbed 0.86% to 6.62 after workers at a major Chilean mine voted to strike following failed labor talks, lifting supply-risk premiums for the world’s top producer. Brent crude plunged 8.03% to 96.83, weighing on Colombia’s oil-linked fiscal and export outlook. No macroeconomic data releases occurred in Colombia, Chile, or Peru.
Gold edged up 0.46% to 4,187.60, offering modest support to Peru’s mining sector.
The Day Ahead
Colombia’s central bank will announce its interest-rate decision at 10:00 ET on September 30, with consensus and the prior rate both at 12.00%, pointing to a hold. No sovereign debt auctions or major mining announcements are scheduled for the three countries in the immediate window. Market participants will monitor any accompanying statement language on inflation persistence and fiscal developments in Colombia.
Regional equity and FX markets are likely to react to the BanRep outcome and any signals on future policy divergence. Copper prices may remain sensitive to updates on the Chilean mine labor dispute.
Other Economic Notes
Chile and Peru, the world’s leading copper producers, stand to gain from higher prices through stronger export revenues and royalty collections that bolster fiscal balances. Brent’s sharp decline poses downside risks to Colombia’s oil-dependent fiscal receipts and current-account position. Peru’s 10-year yield rise of 15 bp to 6.67% reflects modest repricing amid stable local conditions.
Broader commodity strength, including gold’s modest advance, provides limited offsets for Andean mining exporters. Fiscal deficit widening in Colombia has prompted IMF discussions that could shape medium-term policy credibility.