Andeans Macro Daily(Beta Mode)
BanRep Surprises With 25bp Hike to 12.25%
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
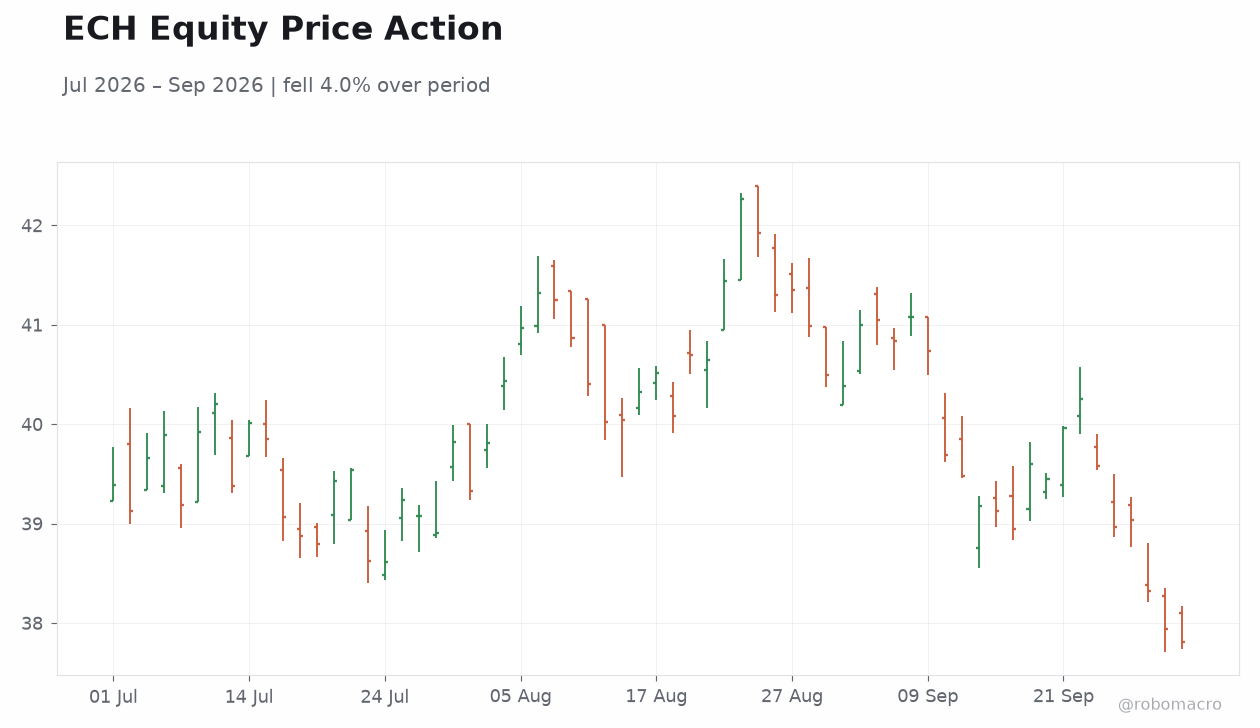
| MSCI Chile | 37.81 | -0.34% |
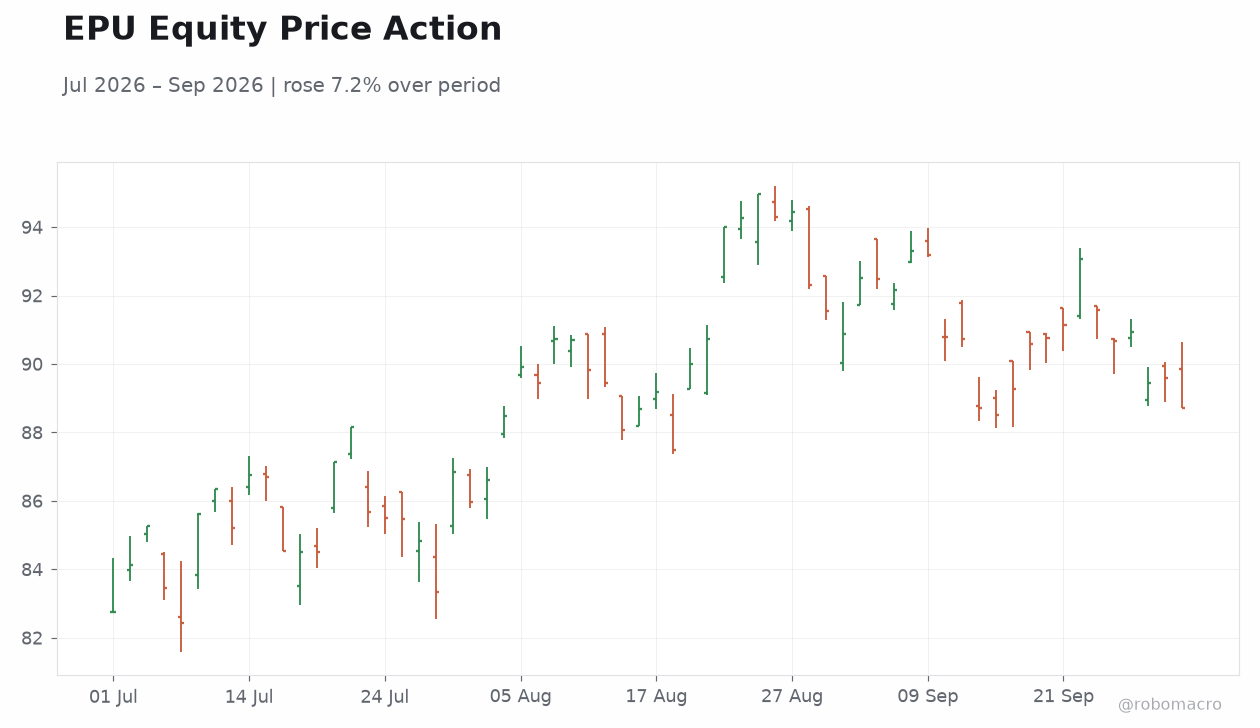
| MSCI Peru | 88.73 | -0.96% |
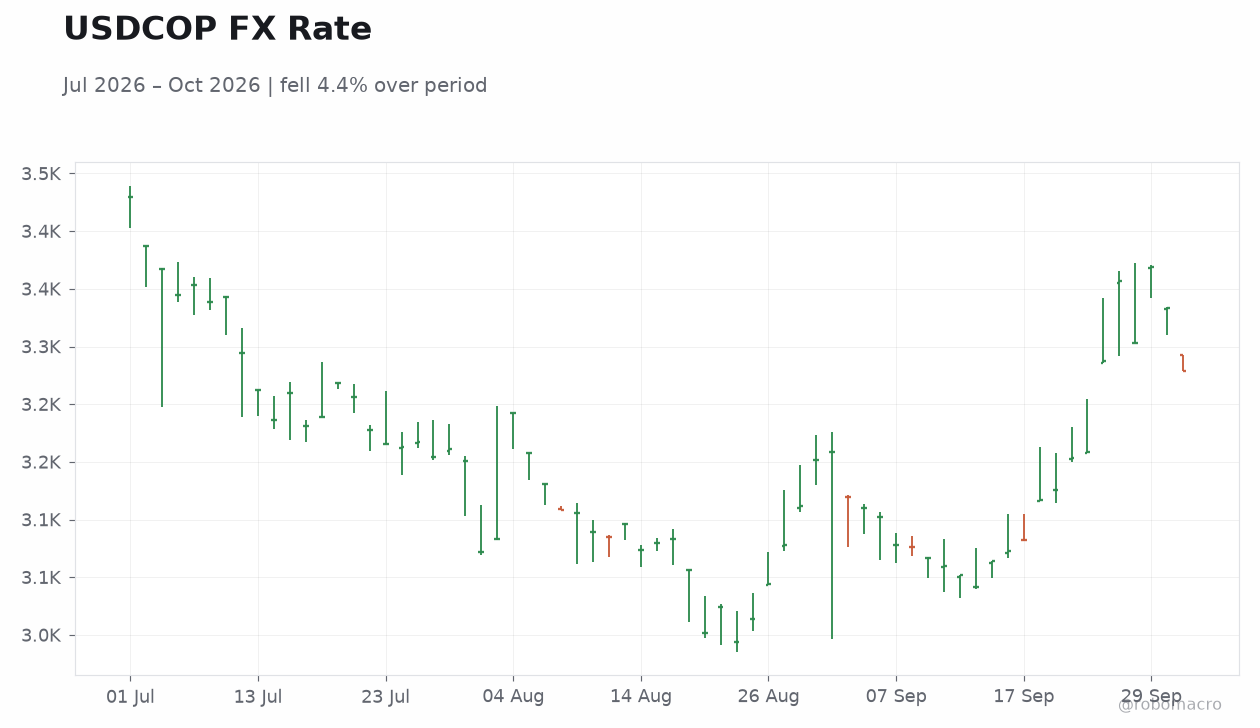
| USD/COP | 3,278.50 | -1.65% |
| USD/CLP | 977.86 | +0.50% |
| USD/PEN | 3.45 | +3.33% |
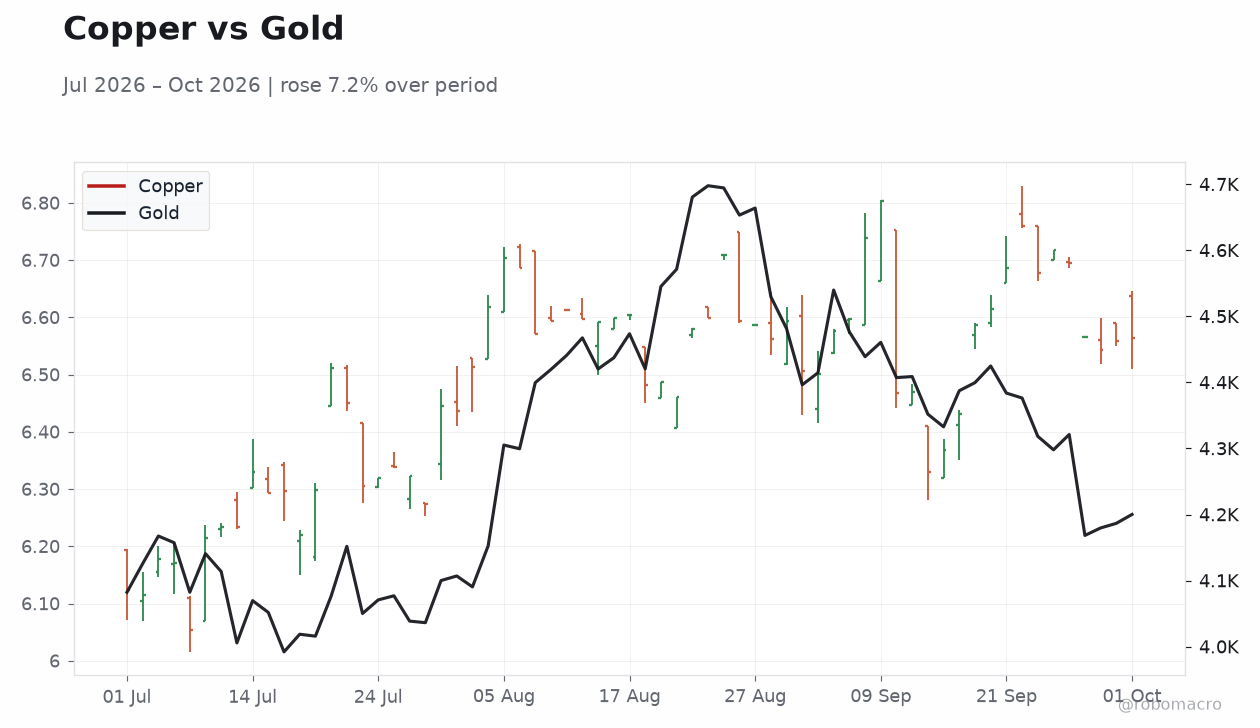
| Copper | 6.57 | +0.15% |
| Gold | 4,200.80 | +0.34% |
| Brent Crude | 100.50 | -2.93% |
| Bitcoin | 83,812.51 | +0.31% |
| Colombia 10Y Govt Yield | - | - |
| Peru 10Y Govt Yield | 6.72% | +5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Central Bank Interest Rate Decision | 12 | 12 | 12.25 |
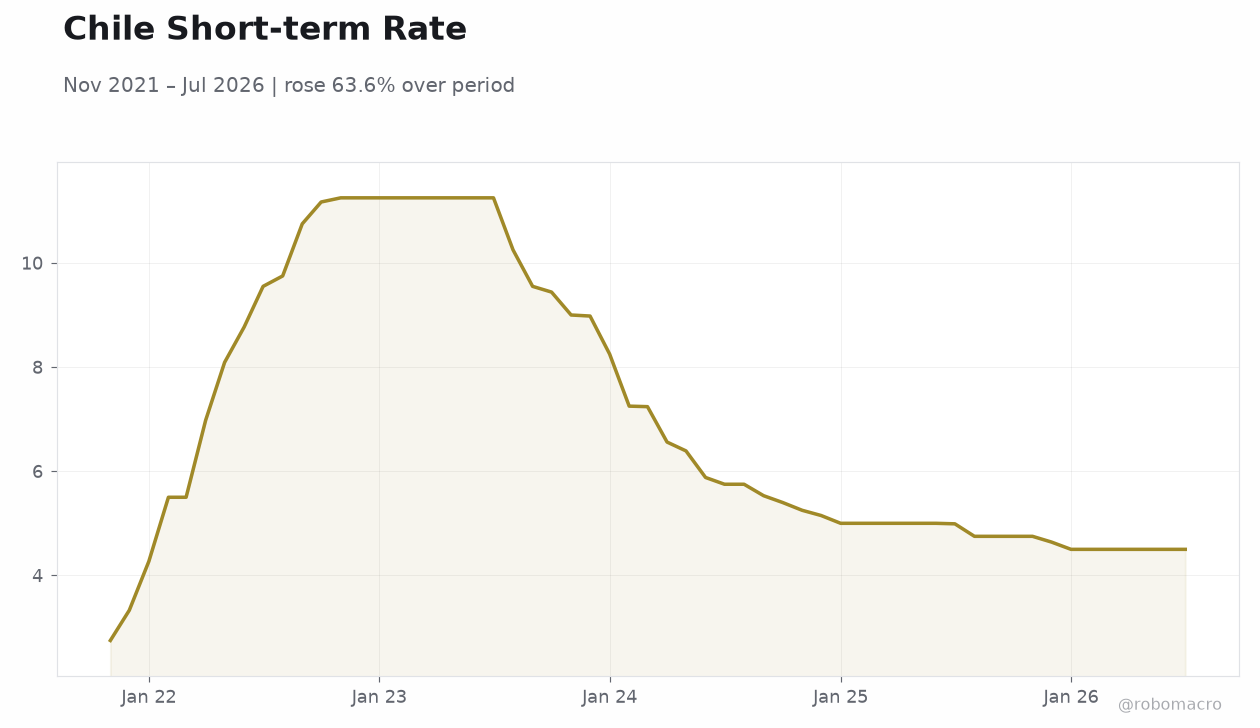 Chile Short-term Rate | Type: macro_line | Short-term rate %: 4.5 (2026-07-01) | Range: 2.75–11.25 | Trend(5pt): 2.75,11.25,7.24,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- BanRep raised its policy rate 25 bp to 12.25%, defying consensus expectations for a hold and signaling sustained inflation vigilance.
- MSCI Peru fell 0.96% while the PEN weakened 3.33% against the USD; MSCI Chile slipped 0.34% as the CLP depreciated 0.50%.
- Copper rose 0.15% to 6.57 and gold advanced 0.34% to 4,200.80, offering modest support to Chile and Peru export revenues.
Yesterday's Recap
Colombia’s central bank delivered the region’s sole policy move, lifting the benchmark rate to 12.25% and catching markets off guard after a 12 consensus. The decision reinforced BanRep’s hawkish tilt amid persistent price pressures. Equity markets reflected the divergence: MSCI Colombia held steady at 9.02 while MSCI Chile and MSCI Peru posted losses of 0.34% and 0.96%.
The Colombian peso strengthened sharply, with USD/COP falling 1.65% to 3,278.50, whereas USD/CLP rose 0.50% to 977.86 and USD/PEN jumped 3.33% to 3.45. Peru’s 10-year government yield climbed 5 bp to 6.72%. Brent crude’s 2.93% drop to 100.50 weighed on Colombia’s fiscal outlook, while copper’s modest gain provided limited relief for Chile and Peru current accounts.
No macroeconomic releases emerged from Chile or Peru.
The Day Ahead
No economic data releases, central-bank meetings, or sovereign bond auctions are scheduled for Colombia, Chile, or Peru over the next two sessions. Market attention will therefore remain on external drivers, including commodity price swings and Federal Reserve signals. Copper and gold movements will continue to shape sentiment toward Chilean and Peruvian assets.
The stronger Colombian peso may keep regional FX volatility elevated in the near term. Analysts will monitor any follow-up comments from BanRep officials for clues on the timing of further tightening.
Other Economic Notes
Copper’s stability at 6.57 continues to underpin fiscal balances in Chile and Peru, though sustained prices above 6.50 remain necessary to offset mining royalty shortfalls. Gold at 4,200.80 offers incremental support to Peru’s export receipts and Colombia’s smaller mining sector. Brent’s decline pressures Colombia’s oil-linked revenues and widens the gap between fiscal and current-account trajectories across the bloc.
Lithium policy developments in Chile stay on the medium-term radar but produced no immediate market reaction. Regional equity underperformance versus global benchmarks highlights the Andean bloc’s sensitivity to both commodity cycles and differentiated monetary paths.