Andeans Macro Daily(Beta Mode)
COP Leads Gains as Copper Rallies; Peru Equities Pop
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
| MSCI Chile | 37.73 | +0.13% |
| MSCI Peru | 90.68 | +2.28% |
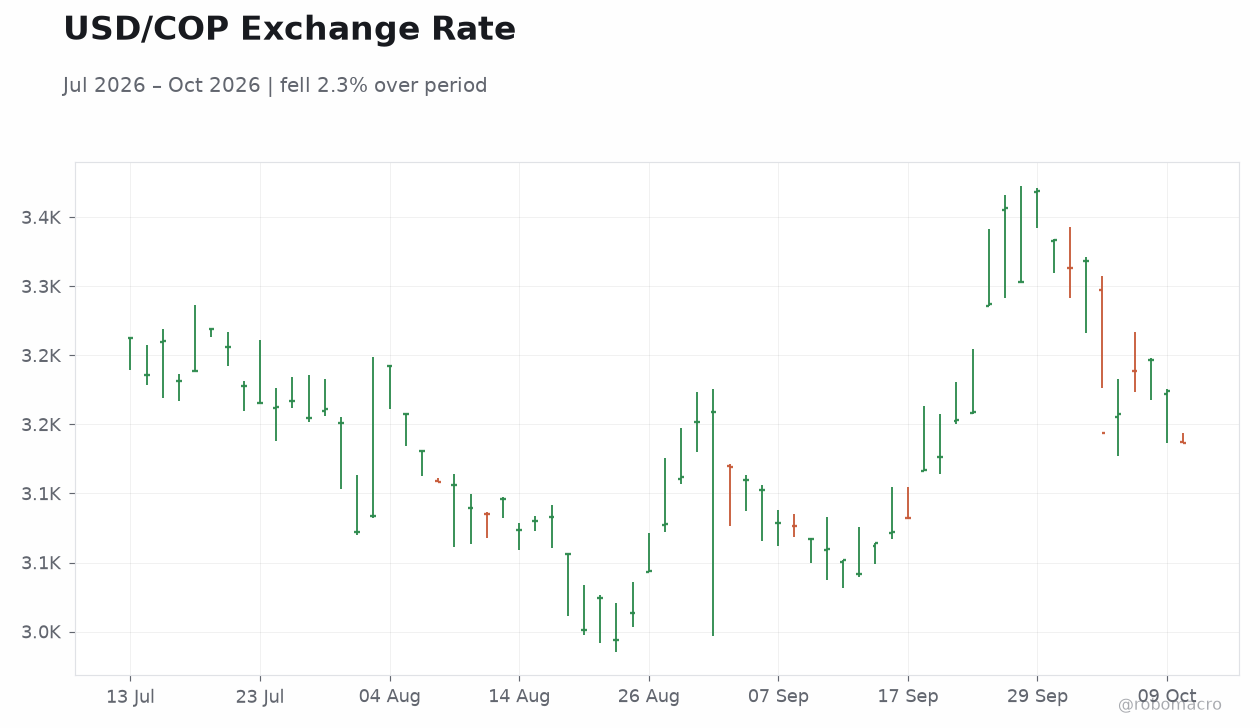
| USD/COP | 3,186.55 | -1.17% |
| USD/CLP | 975.06 | -0.31% |
| USD/PEN | 3.44 | +0.06% |
| Copper | 6.77 | +1.87% |
| Gold | 4,195.40 | -0.50% |
| Brent Crude | 106.13 | +1.35% |
| Bitcoin | 83,343.03 | -0.40% |
| Colombia 10Y Govt Yield | - | - |
| Peru 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
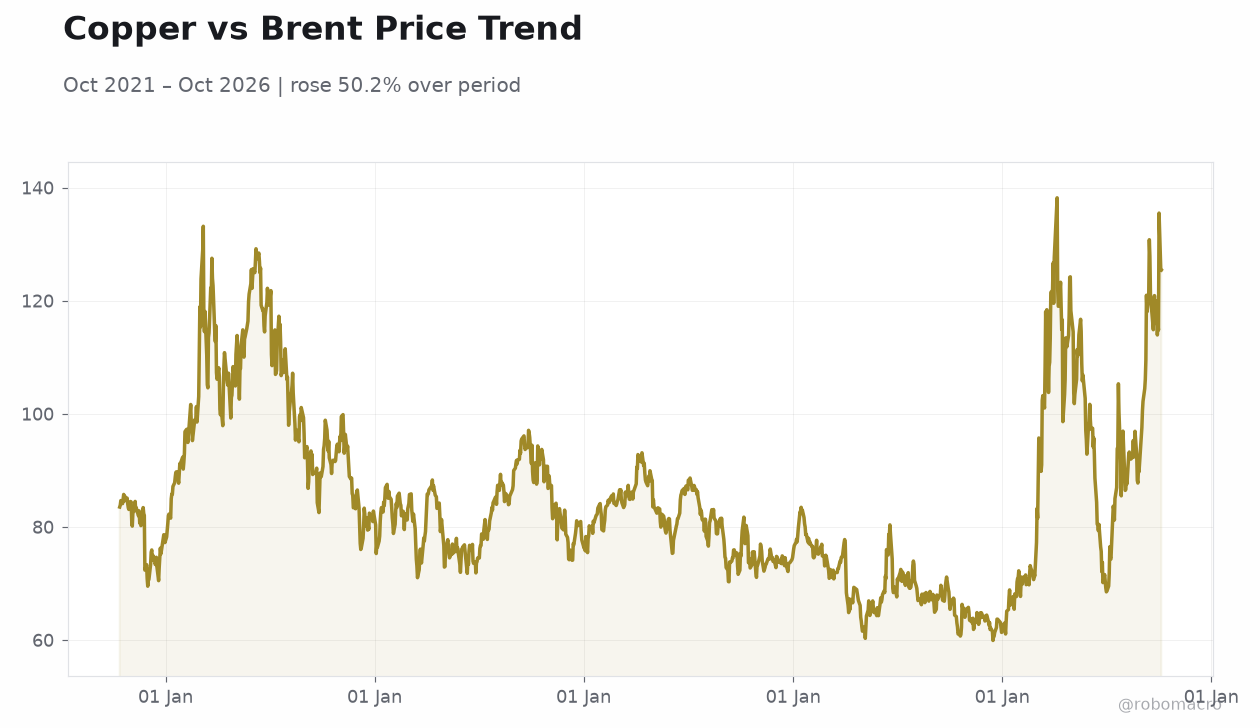 Copper vs Brent Price Trend | Type: macro_line | Brent ($/bbl): 125.4 (2026-10-06) | Range: 59.93–138.2 | Trend(6pt): 83.53,81.11,91.57,72.5,135.5,125.4
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Colombian peso strengthens 1.17% to 3,186.55 against the dollar, outperforming regional peers as MSCI Peru surges 2.28% and copper climbs 1.87% to $6.77/lb.
- World Bank projects Colombia will outpace Brazil and Mexico in 2026 growth, lending a fundamental tailwind to COP and local assets.
- Chile's capital hit by flash floods and mudslides; Atacama lithium extraction faces scrutiny over social and environmental costs, keeping the CLP supply narrative in focus.
Yesterday's Recap
Andean markets closed Friday's session with a broadly risk-on tone. Peru led the region, with the MSCI Peru index advancing 2.28% to 90.68, buoyed by the sharp rally in copper prices, which rose 1.87% to $6.77/lb — a key revenue driver for Peruvian miners. The Colombian peso was the standout currency, appreciating 1.17% to 3,186.55/USD, supported by both the commodity complex and the World Bank's constructive 2026 growth outlook for Colombia.
Chilean equities edged up 0.13% to 37.73, while USD/CLP eased 0.31% to 975.06. The Peruvian sol was the laggard in FX, slipping marginally by 0.06% to 3.44/USD. Elsewhere in the complex, Brent crude gained 1.35% to $106.13, a supportive backdrop for Colombia's oil-linked fiscal revenues, while gold retreated 0.50% to $4,195.40/oz.
Sovereign yield data for Colombia and Peru were unavailable in Friday's tape, leaving the rates picture reliant on cash-market proxies.
The Day Ahead
The regional calendar is quiet to start the week, with no scheduled Andean data releases or central-bank events on Monday. Attention turns instead to secondary flows: copper's momentum will be scrutinized for follow-through after Friday's 1.87% jump, given its outsized weighting in Chilean and Peruvian export baskets. In Colombia, focus stays on the Gran Tierra Energy situation — shareholders have approved the sale of its Colombian and Ecuadorian businesses, a transaction that could influence FDI sentiment and sector consolidation dynamics.
Chilean markets will digest the aftermath of the Santiago flash floods, watching for any infrastructure or mining-operations disruption headlines. Later in the week, the absence of prints today keeps the door open for positioning ahead of any mid-week inflation or activity data. Traders should also monitor regional FX for carry-driven flows after COP's outsized Friday move.
Other Economic Notes
The World Bank's projection that Colombia will outpace both Brazil and Mexico in 2026 is a notable endorsement of the country's macro framework and investment cycle, reinforcing the case for Colombian assets even as political noise persists. ↓ p.2