Andeans Macro Daily(Beta Mode)
PEN Slides 3% While CLP Lags; Copper Grinds Higher
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
| MSCI Chile | 37.39 | -1.03% |
| MSCI Peru | 90.28 | -0.46% |
| USD/COP | 3,181.88 | -0.40% |
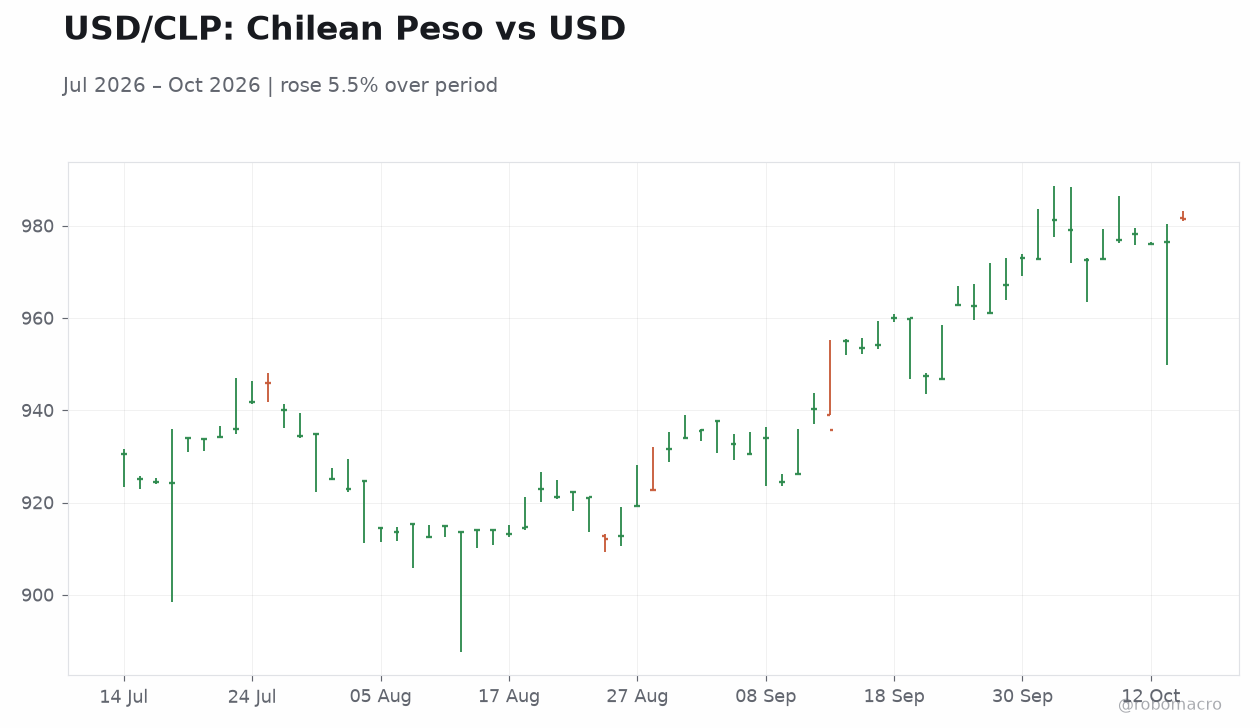
| USD/CLP | 981.18 | +0.49% |
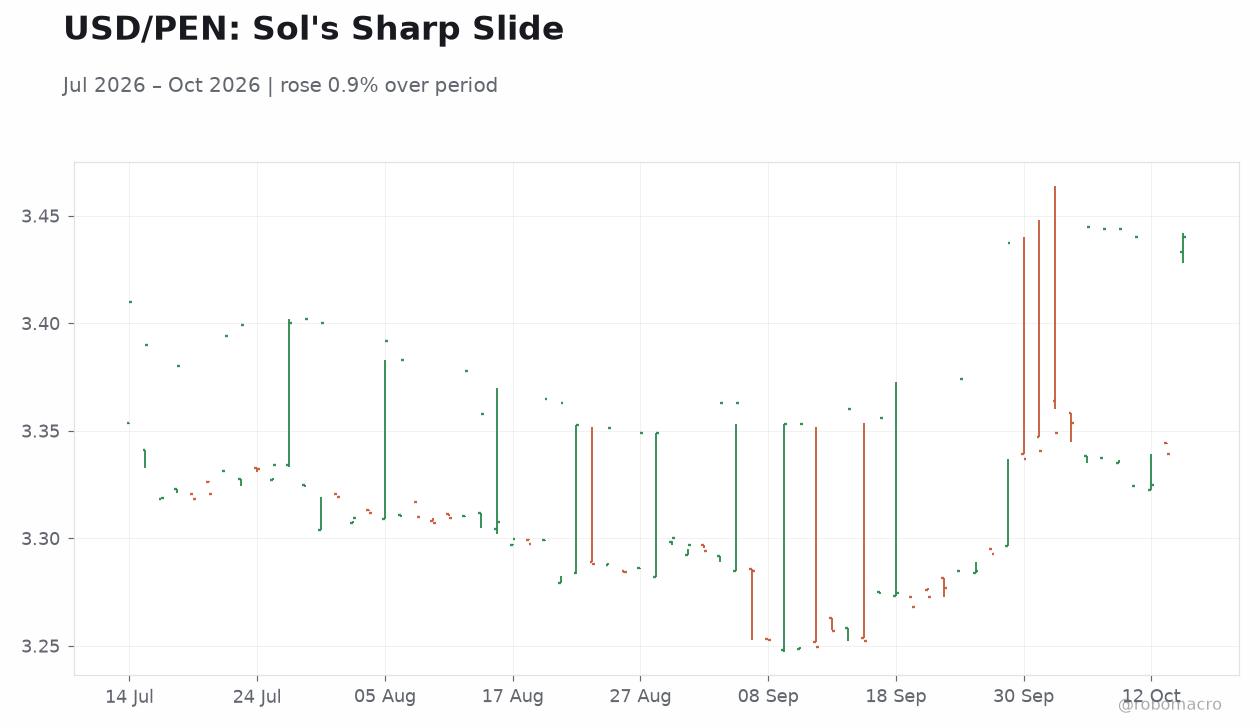
| USD/PEN | 3.44 | +3.02% |
| Copper | 6.74 | +0.88% |
| Gold | 4,159.20 | -0.43% |
| Brent Crude | 106.56 | +0.82% |
| Bitcoin | 83,374.69 | +0.34% |
| Colombia 10Y Govt Yield | - | - |
| Peru 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
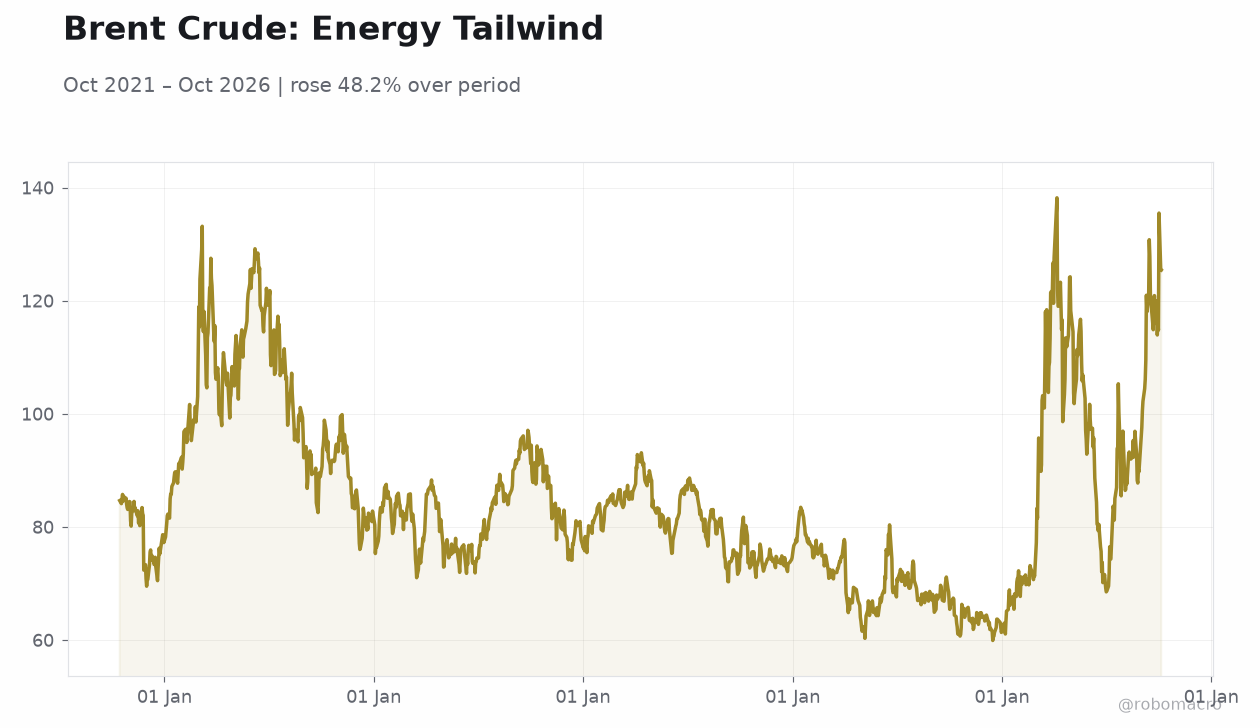 Brent Crude: Energy Tailwind | Type: macro_line | Brent Crude (USD/bbl): 125.4 (2026-10-06) | Range: 59.93–138.2 | Trend(5pt): 84.67,83.43,93.12,70.38,125.4
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Peru's sol weakened sharply, with USD/PEN up 3.02% to 3.44, the largest FX move in the Andean complex, while equities slipped modestly.
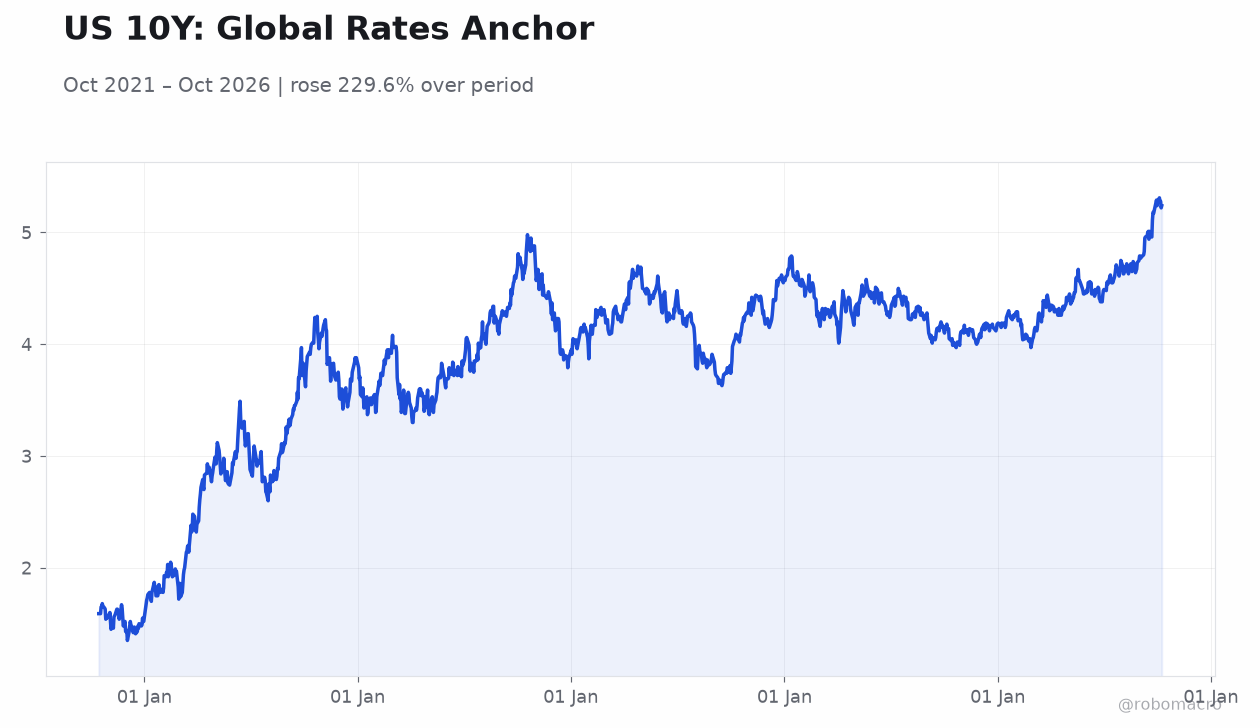
- Chilean equities underperformed, with MSCI Chile down 1.03%, as pension funds race to unwind mispriced US rates bets.
- Copper advanced 0.88%, lending support to Chilean and Peruvian external accounts despite broad risk-off tones in local assets.
Yesterday's Recap
Andean markets diverged on Tuesday, October 13, with FX doing most of the work. The Peruvian sol was the standout mover, depreciating 3.02% against the dollar to 3.44, a sharp single-day adjustment for a currency that is typically the region's most stable; the move suggests either a local portfolio rebalancing, a catch-up after an extended period of stability, or a shift in non-resident positioning in the local bond market. The Colombian peso bucked the regional softness, strengthening 0.40% to 3,181.88 per dollar, consistent with the higher-for-longer BanRep narrative and attractive carry.
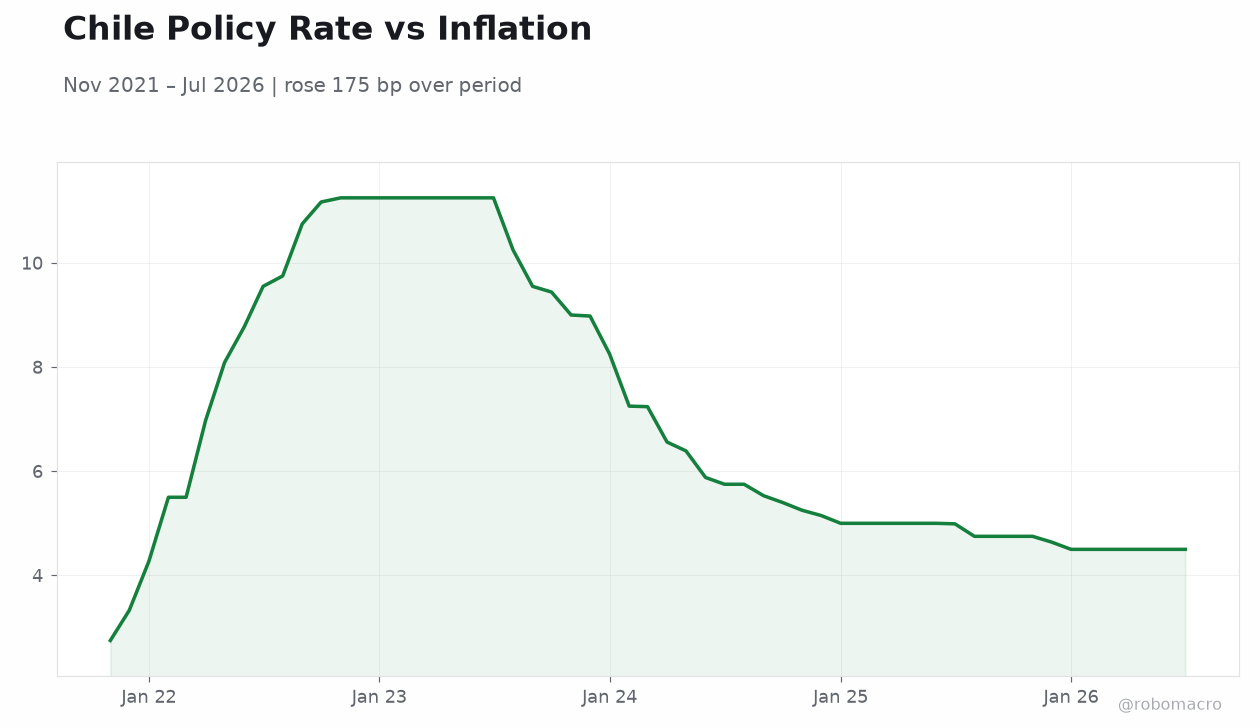
The Chilean peso weakened 0.49% to 981.18, lagging peers as the BCCh's easing cycle narrows the rate differential. On equities, MSCI Chile fell 1.03% to 37.39, the weakest of the three proxies, while MSCI Peru shed 0.46% to 90.28 and MSCI Colombia was flat at 9.02. Commodity tailwinds were intact: copper rose 0.88% to 6.74, gold eased 0.43% to 4,159.20, and Brent crude gained 0.82% to 106.56, a mix that is unambiguously positive for Chilean and Peruvian terms of trade and supportive of Colombian fiscal revenues.
No scheduled macro prints crossed the tape for the region.
The Day Ahead
The calendar is light across the Andean bloc on Wednesday, October 14, with no scheduled inflation, GDP, or labor-market releases for Colombia, Chile, or Peru. In the absence of hard data, attention turns to flow-driven dynamics: the persistence of the sol's sharp depreciation and whether the BCRP leans on spot or swap operations to smooth volatility, given Peru's history of active FX reserve management. For Colombia, the focus stays on the COP's grind stronger and whether the 3,180 area holds as a base, with the fiscal reform agenda and BanRep's hawkish tilt underpinning sentiment.
Chilean assets will track the unwind of pension funds' US rates hedges, a story with direct implications for CLP liquidity and local fixed-income demand. Copper's direction remains the key exogenous variable for both Santiago and Lima.
Other Economic Notes
Mining headlines dominated the regional corporate tape. Highlander Silver was received by President Keiko Fujimori of Peru, underscoring the government's push to court precious-metals investment amid a favorable price environment. ↓ p.2