Andeans Macro Daily(Beta Mode)
Andean FX Falls as Copper, Gold Slip; Oil Rises
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
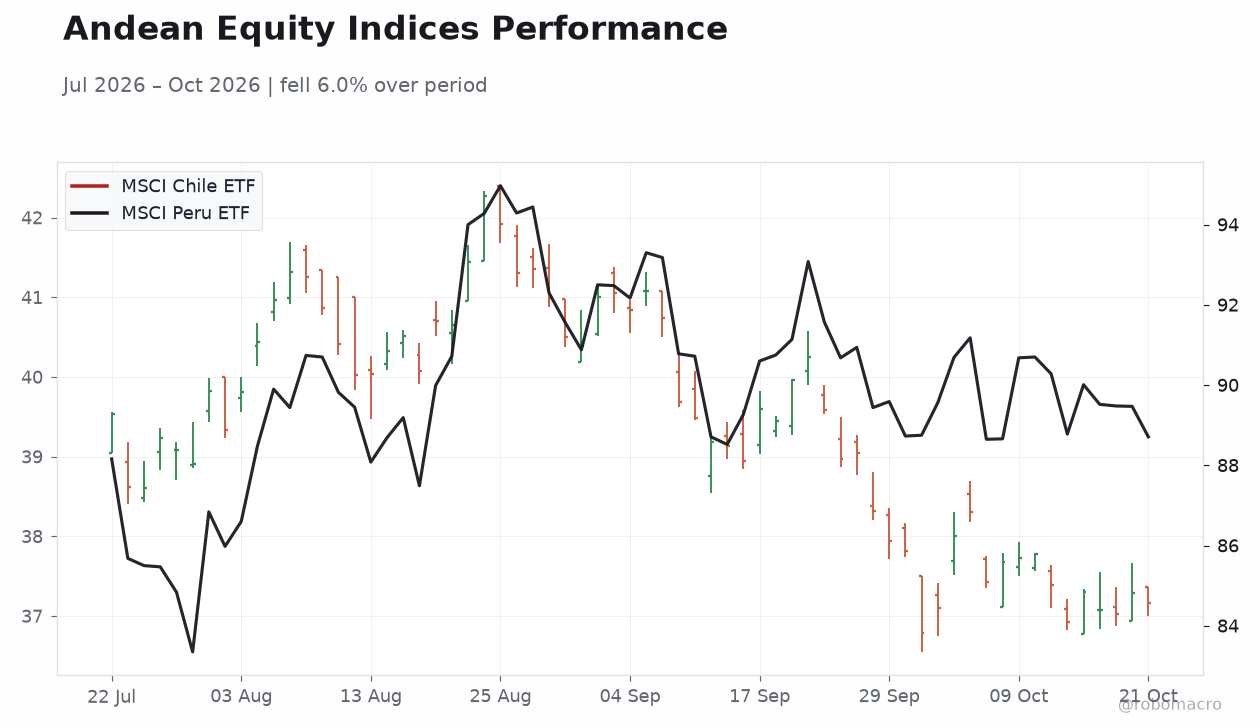
| MSCI Chile | 37.16 | -0.35% |
| MSCI Peru | 88.71 | -0.85% |
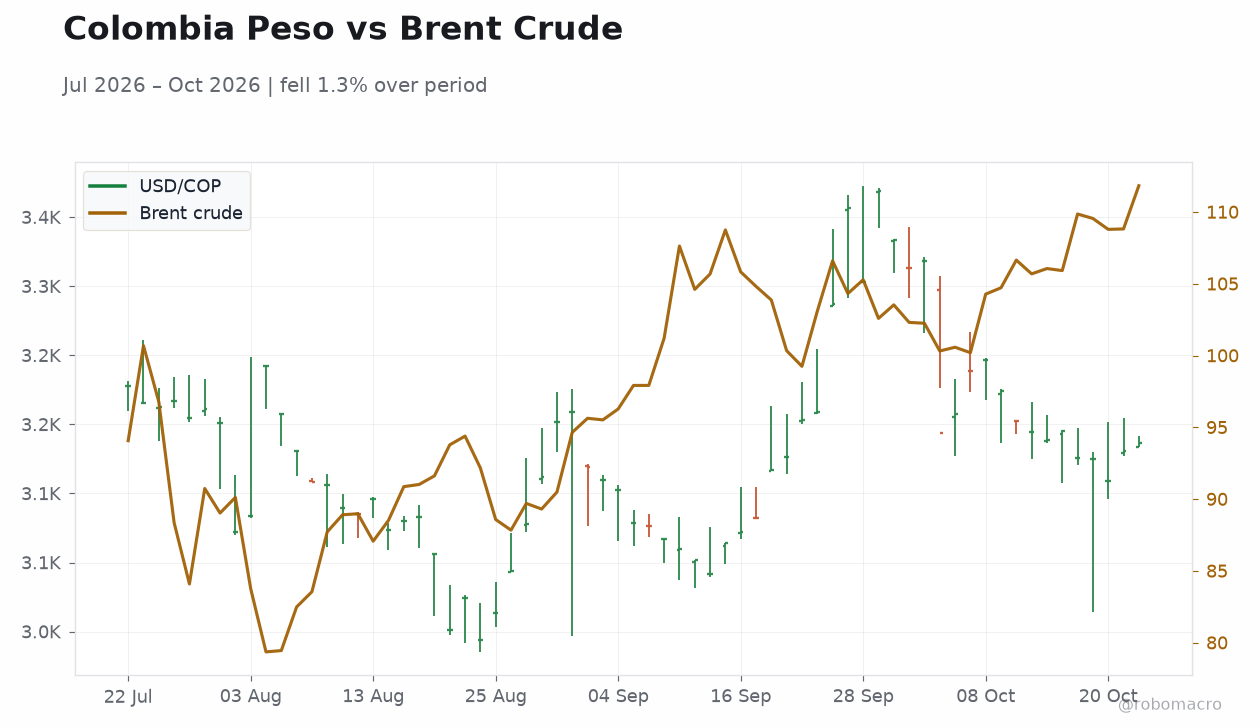
| USD/COP | 3,186.49 | +0.19% |
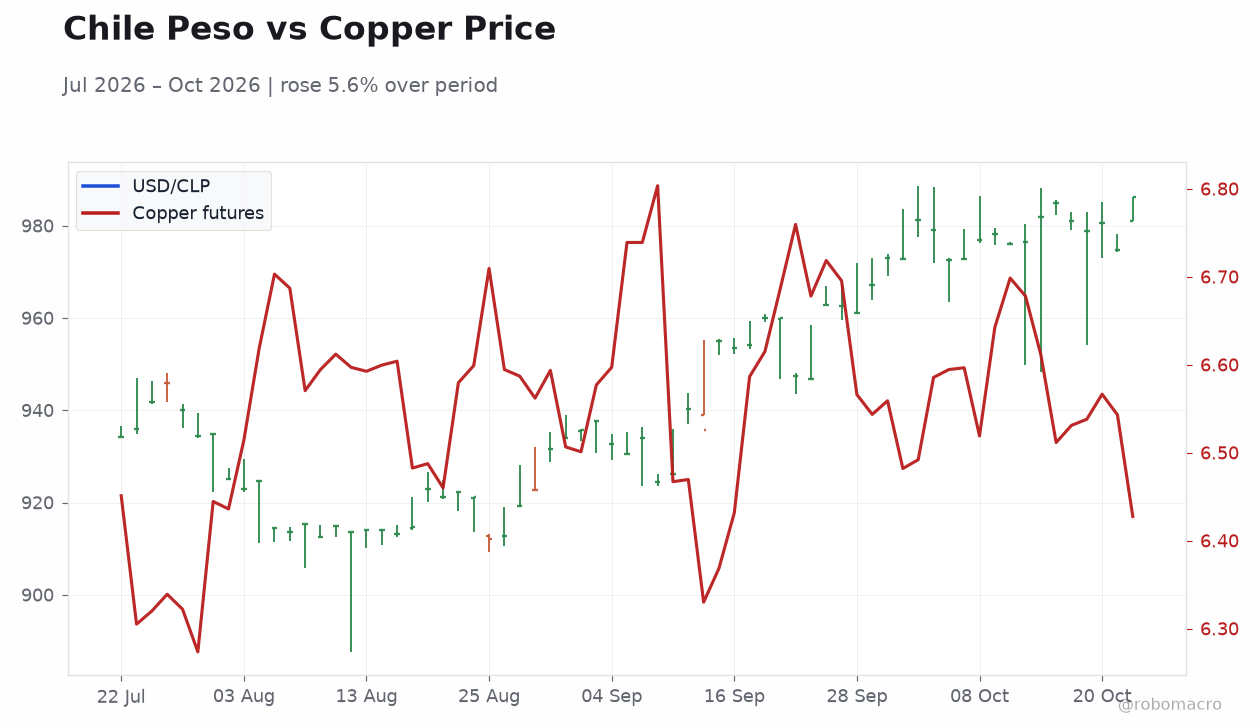
| USD/CLP | 985.54 | +1.10% |
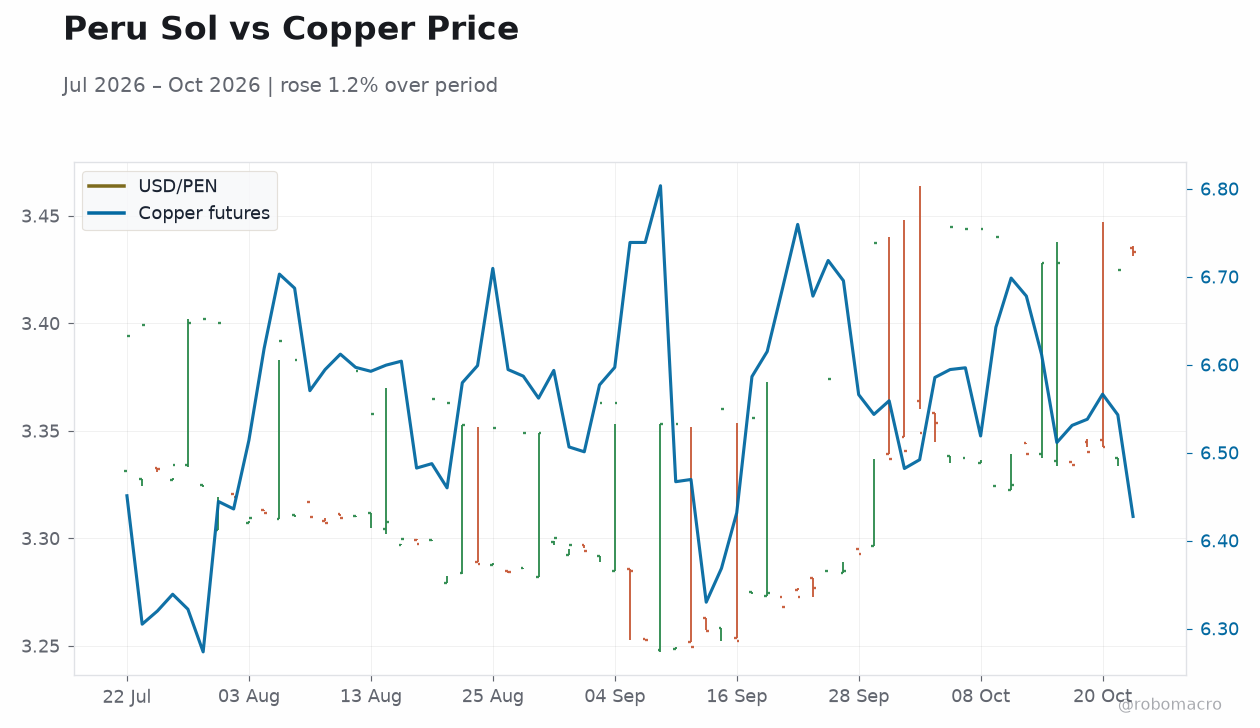
| USD/PEN | 3.43 | +0.24% |
| Copper | 6.42 | -1.82% |
| Gold | 4,090.40 | -1.44% |
| Brent Crude | 111.90 | +2.83% |
| Bitcoin | 81,920.95 | -2.49% |
| Colombia 10Y Govt Yield | - | - |
| Peru 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
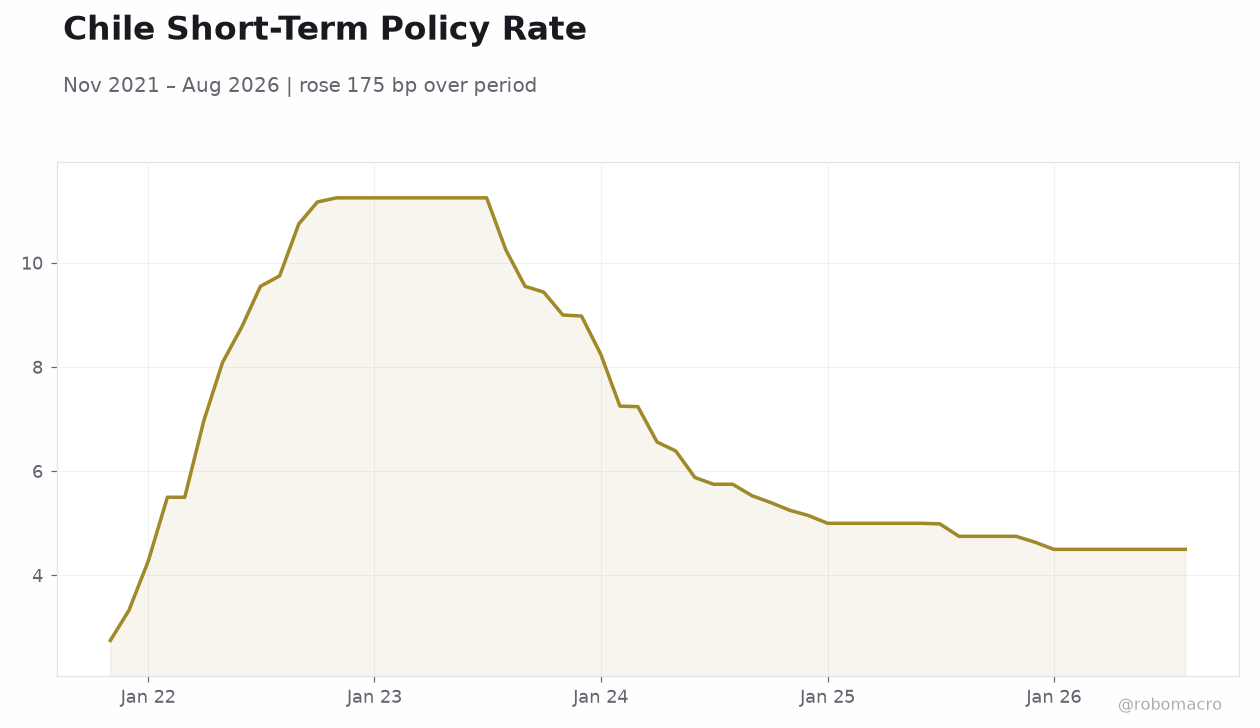 Chile Short-Term Policy Rate | Type: macro_line | Chile short-term rate (%): 4.5 (2026-08-01) | Range: 2.75–11.25 | Trend(5pt): 2.75,11.25,7.24,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- USD/CLP jumps 1.10% as copper falls 1.82%; USD/PEN up 0.24%, USD/COP up 0.19% — broad Andean FX weakness
- MSCI Peru -0.85%, MSCI Chile -0.35%, MSCI Colombia flat; Brent +2.83% supports Colombian fiscal outlook
- No Andean calendar prints yesterday or today; BCCh and BCRP hold the policy line while BanRep stays hawkish
Yesterday's Recap
The Andean bloc traded without domestic data catalysts on October 21, leaving price action driven entirely by commodities and the dollar. Chile was the weakest link: the peso depreciated 1.10% against the greenback as copper — the country's dominant export — fell 1.82%, a combination that tightens imported-inflation pressure just as the BCCh weighs further easing. Peru's sol slipped 0.24% while MSCI Peru dropped 0.85%, the sharpest equity decline in the bloc, reflecting mining-sector sensitivity to the copper move.
Colombia was comparatively insulated: MSCI Colombia was unchanged and the peso edged only 0.19% weaker, with Brent crude's 2.83% surge to $111.90 offering a meaningful offset to the fiscal and external accounts. Gold's 1.44% decline to $4,090.40 removed a secondary support for Peruvian and Colombian export revenue. No Andean macro releases printed during the session, so positioning ahead of month-end and commodity flows dominated.
Regional risk appetite was further dented by Bitcoin's 2.49% slide, a decent proxy for broader EM risk sentiment.
The Day Ahead
The Andean calendar is empty again on October 22, with no scheduled releases across Colombia, Chile, or Peru, so markets will again take direction from external drivers. Traders will focus on the copper complex after yesterday's 1.82% decline, given its outsized weight in Chilean and Peruvian export earnings and fiscal revenue. Brent crude near $111.90 remains the key variable for Colombia, where higher oil prices support both the external balance and sovereign revenue.
With no domestic prints, FX desks will watch whether USD/CLP consolidates above the 985 level or extends toward parity, a psychologically significant threshold for Chilean importers. Peruvian markets will track mining-sector headlines, including Teck's Highland Valley Copper strike notice in Canada, which could tighten global concentrate supply and indirectly support Peruvian copper revenues. Colombian local bond markets will look for direction from the oil price and any shifts in the global risk backdrop.
Other Economic Notes
The Andean bloc's macro story remains one of divergence in inflation trajectories and policy credibility. Chile's aggressive easing cycle has been the region's most pronounced, but a weaker peso and firm copper volatility complicate the disinflation path. ↓ p.2