Andeans Macro Daily(Beta Mode)
BCCh Decision Looms as Andean FX Weakens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
| MSCI Chile | 35.56 | -1.22% |
| MSCI Peru | 84.40 | +0.24% |
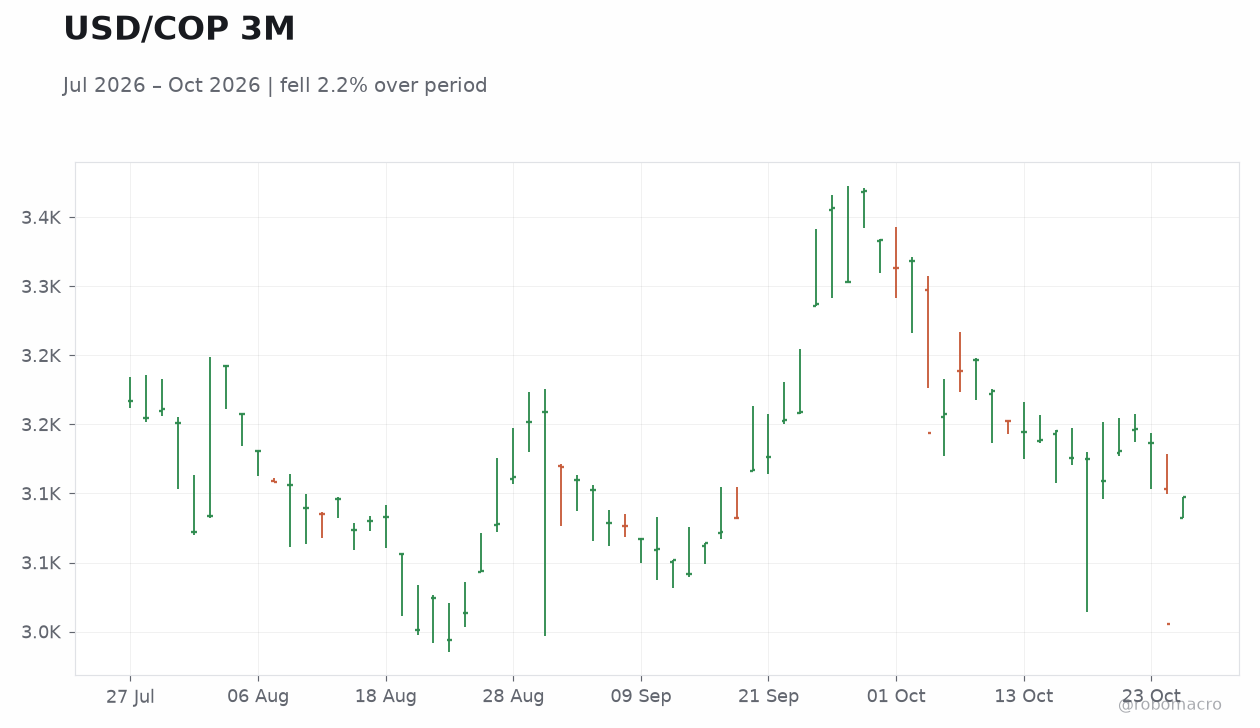
| USD/COP | 3,147.43 | +3.00% |
| USD/CLP | 989.50 | +3.12% |
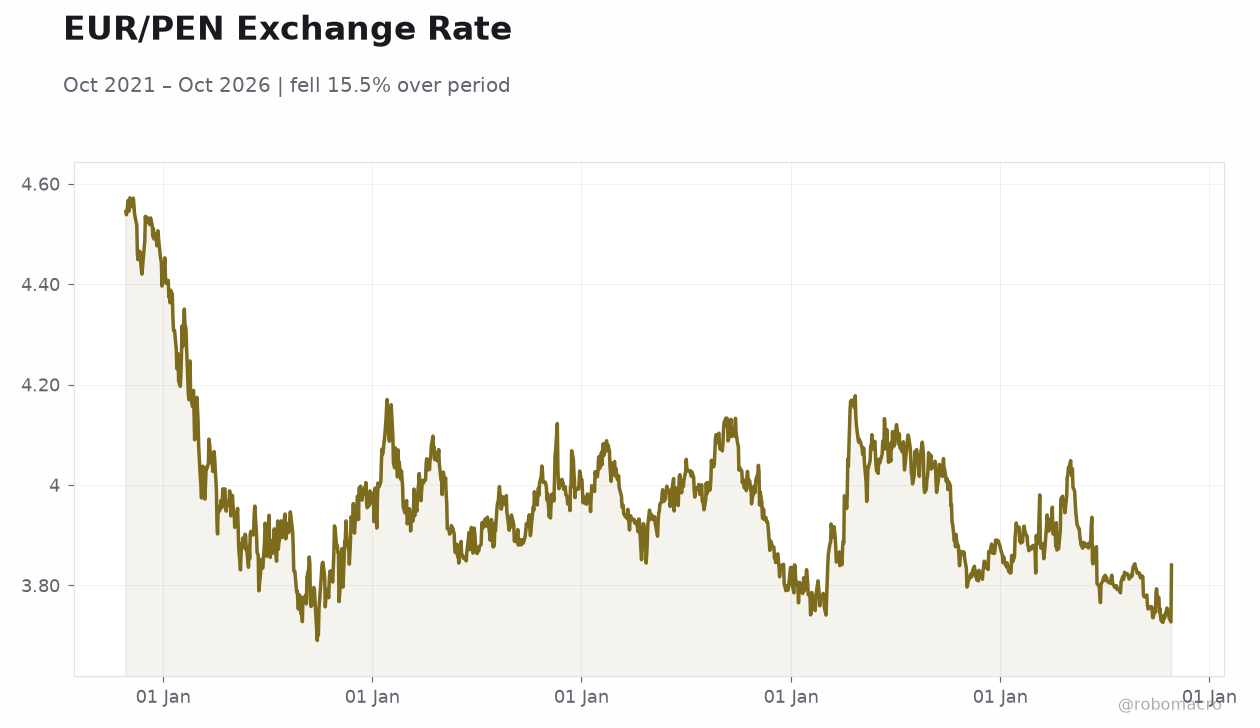
| USD/PEN | 3.44 | +3.47% |
| Copper | 6.63 | +1.85% |
| Gold | 4,024.50 | -0.34% |
| Brent Crude | 110.04 | -4.98% |
| Bitcoin | 79,891.90 | -0.14% |
| Colombia 10Y Govt Yield | - | - |
| Peru 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
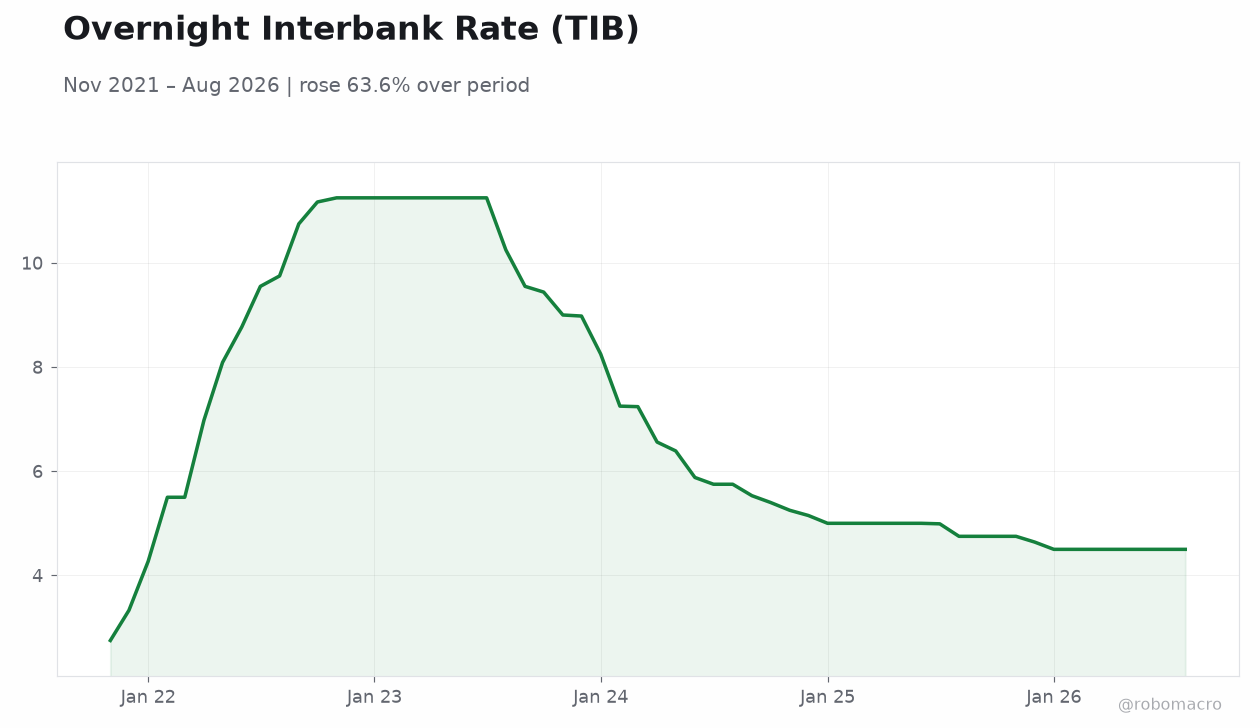
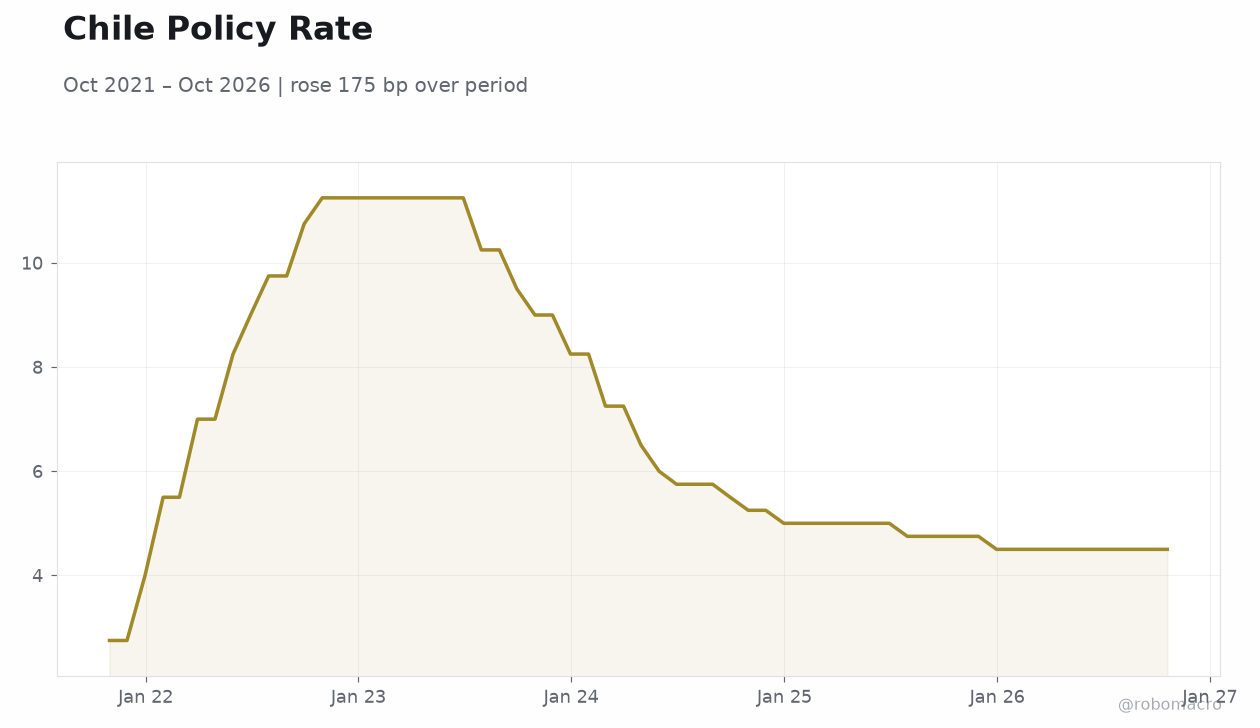 Chile Policy Rate | Type: macro_line | Policy Rate (%): 4.5 (2026-10-20) | Range: 2.75–11.25 | Trend(5pt): 2.75,11.25,6.5,4.75,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Central Bank Interest Rate Decision | 4.50 | 4.50 | 17:00 |
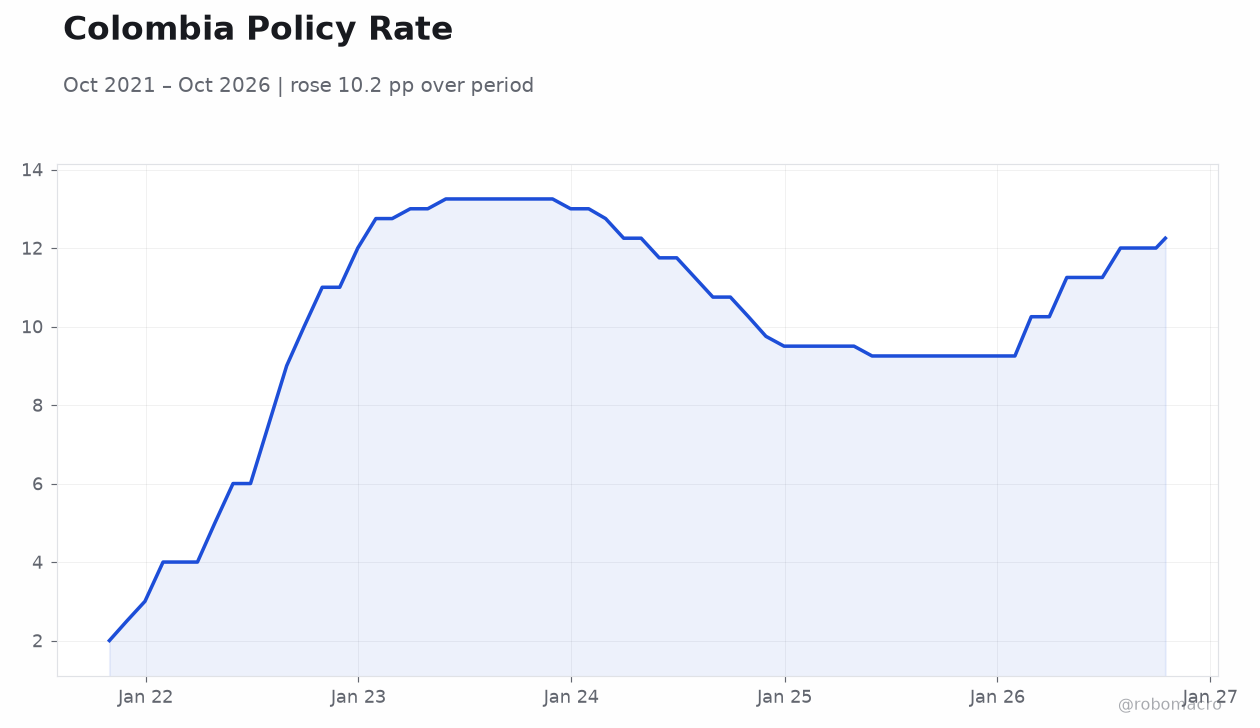
| Central Bank Interest Rate Decision | 12.25 | - | 14:00 |
- BCCh expected to hold rate at 4.50% with Chile CPI at 4.08%
- USD/COP, USD/CLP and USD/PEN all surge over 3% in sharp selloff
- Copper rises 1.85% while Brent crude drops nearly 5%
Yesterday's Recap
Andean equity and currency markets posted mixed results with clear regional divergence. MSCI Chile fell 1.22% while MSCI Peru edged up 0.24% and MSCI Colombia held flat. The Chilean peso, Colombian peso and Peruvian sol all depreciated sharply, with USD/CLP rising 3.12%, USD/COP climbing 3.00% and USD/PEN jumping 3.47%.
Copper advanced 1.85% to 6.63, providing some support to Chile and Peru, while Brent crude plunged 4.98% to 110.04. No macroeconomic data releases occurred across the three countries. Gold slipped 0.34% and Bitcoin was little changed.
The Day Ahead
Markets will focus on the BCCh monetary policy decision scheduled for 17:00 ET. Consensus expects the committee to leave the policy rate unchanged at 4.50%. Attention will center on any updated inflation and growth projections released alongside the decision.
The BanRep meeting follows on 30 October with the policy rate currently at 12.25%. Traders will also monitor copper and oil price action given their direct impact on fiscal and external balances in Chile and Colombia.
Other Economic Notes
Chile’s CPI at 4.08% and Peru’s at 4.06% remain well below Colombia’s 6.29% reading, underscoring divergent inflation paths. Commodity dependence continues to shape external accounts, with copper critical for Chile and Peru while oil remains central to Colombia. Fiscal balances across the bloc stay under pressure from elevated global energy and mining price volatility.
Lithium developments in Chile add a longer-term structural theme for export diversification.
Global Macro News
Copper prices steadied as investors balanced signs of resilient Chinese demand against weakness in AI-related equities. Brent crude’s steep decline reflected softer global growth signals and ample supply. Broader risk sentiment stayed cautious amid mixed equity performance in developed markets.
China’s economic data releases continue to influence metal prices that directly affect Andean terms of trade. Emerging-market currencies faced broad pressure from higher US yields and dollar strength. Trade policy developments, including Chile’s FTA discussions with Canada, offer modest positive offsets for regional exporters.