Andeans Macro Daily(Beta Mode)
BCCh Holds at 4.50%, BanRep Decision Looms
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
| MSCI Chile | 36.19 | -0.49% |
| MSCI Peru | 84.62 | -1.02% |
| USD/COP | 3,172.14 | +0.71% |
| USD/CLP | 993.63 | +0.79% |
| USD/PEN | 3.45 | +0.20% |
| Copper | 6.59 | -0.85% |
| Gold | 4,039.90 | -0.29% |
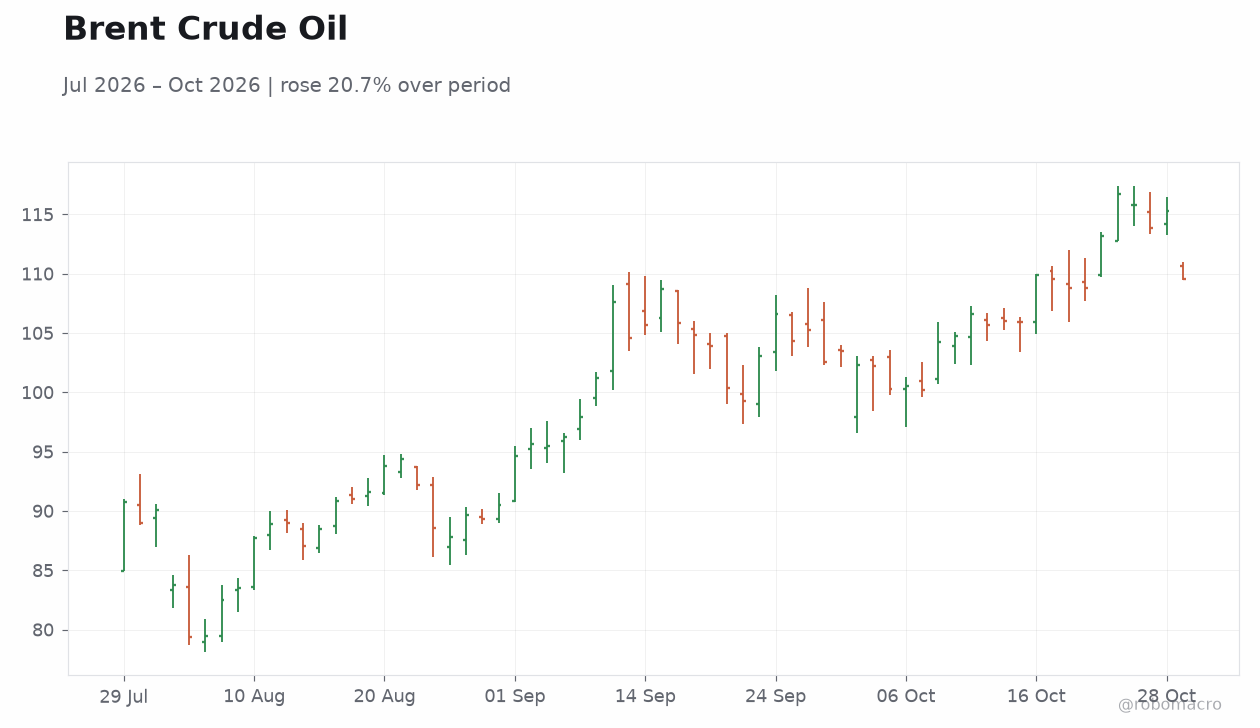
| Brent Crude | 109.79 | -4.80% |
| Bitcoin | 80,039.55 | -1.51% |
| Colombia 10Y Govt Yield | - | - |
| Peru 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Central Bank Interest Rate Decision | 4.50 | 4.50 | 4.50 |
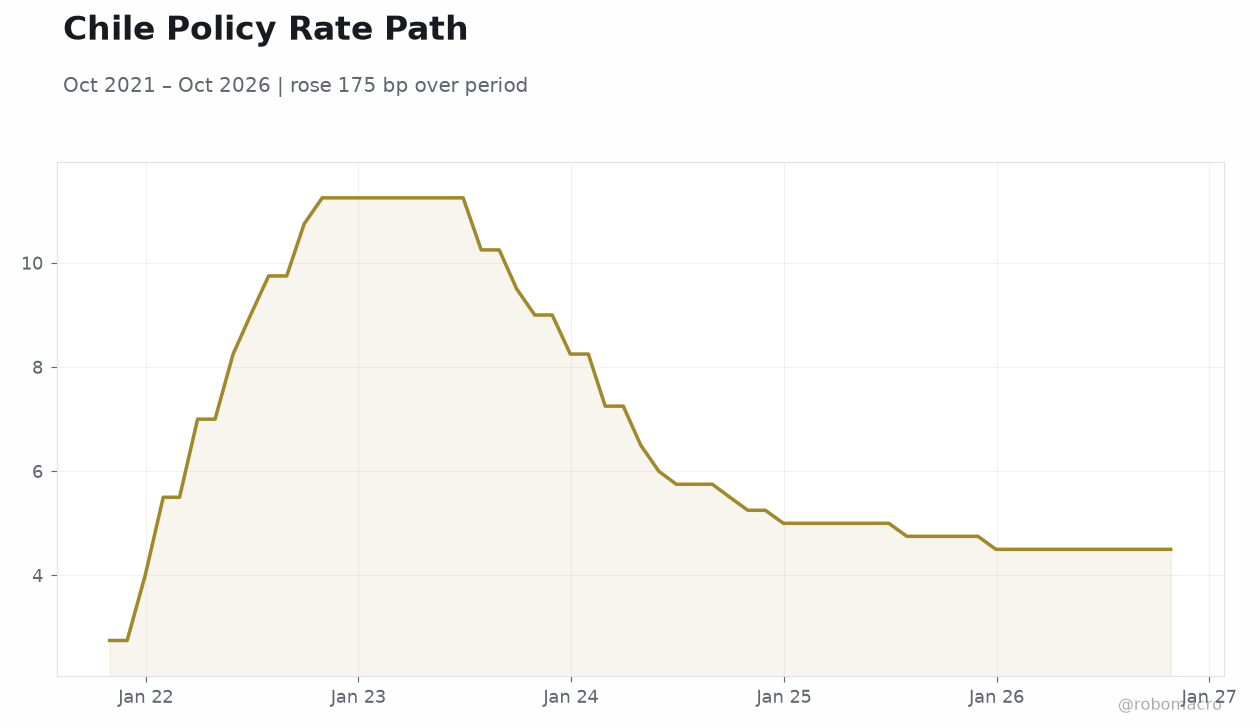 Chile Policy Rate Path | Type: macro_line | BCCh Policy Rate (%): 4.5 (2026-10-27) | Range: 2.75–11.25 | Trend(5pt): 2.75,11.25,6.5,4.75,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
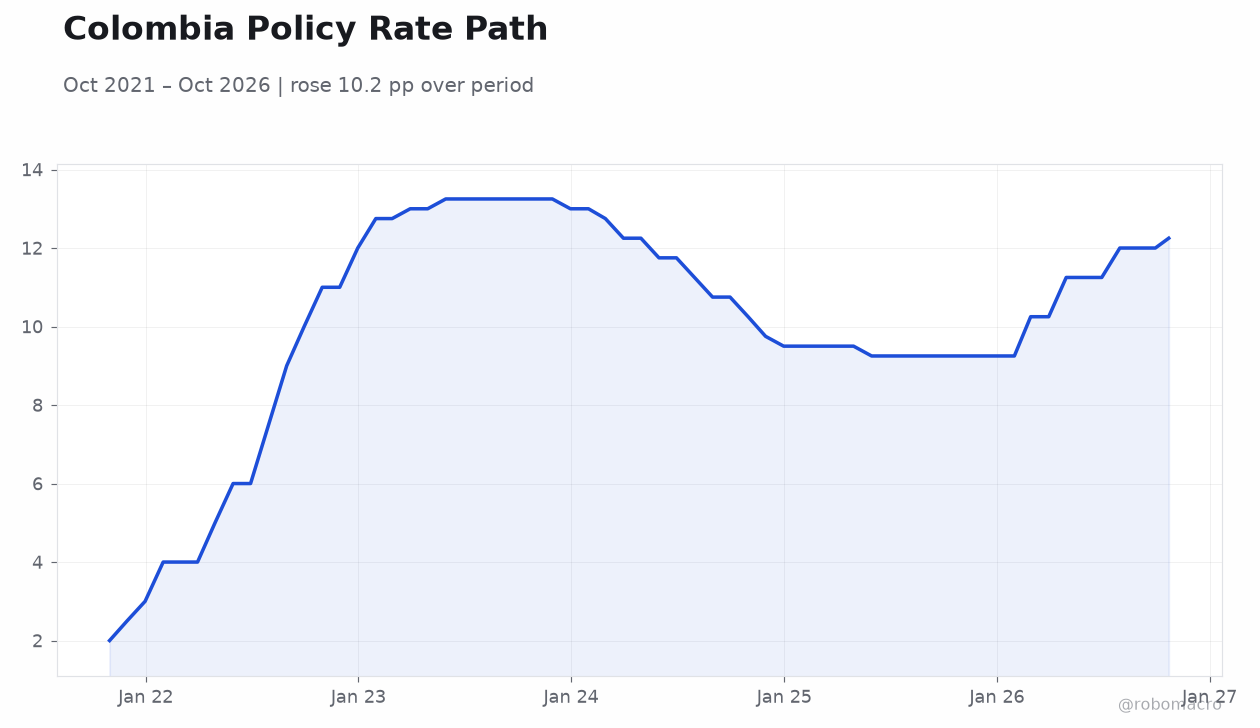
| Central Bank Interest Rate Decision | 12.25 | - | 14:00 |
| Friday (2026-10-30) | |||
| Central Bank Interest Rate Decision | 12.25 | - | 14:00 |
- BCCh held its policy rate at 4.50% on October 27, matching consensus and extending the pause after Chile's aggressive cutting cycle
- Andean FX under broad pressure: USD/COP +0.71% to 3,172.14, USD/CLP +0.79% to 993.63, USD/PEN +0.20% to 3.45
- BanRep decision due October 30 with the rate at 12.25%; Brent's 4.80% slide to $109.79 offers marginal relief on the inflation outlook
Yesterday's Recap
The Banco Central de Chile held its policy rate at 4.50% on October 27, in line with consensus and the previous level, confirming the pause that has been in place since the December 2025 decision. The hold comes with Chilean CPI at 4.08% year-on-year as of September, still above target and limiting room for further easing after the region's most aggressive cutting cycle. Chilean equities softened, with MSCI Chile down 0.49% to 36.19, while the peso depreciated 0.79% to 993.63 per dollar amid broad dollar strength.
Peru fared worse on the equity side, MSCI Peru falling 1.02% to 84.62, with the sol edging 0.20% weaker to 3.45. Colombia was the outlier in FX, with the peso depreciating 0.71% to 3,172.14 ahead of Friday's BanRep decision, while MSCI Colombia was flat at 9.02. Copper slipped 0.85% to $6.59, a headwind for both Chile and Peru, and gold eased 0.29% to $4,039.90.
The Day Ahead
The dominant event is BanRep's rate decision on October 30 at 14:00 ET, with the policy rate currently at 12.25% following the September 30 decision and no consensus figure published. Colombia's 6.29% September CPI keeps the central bank firmly on hold in real terms, and the market will parse the statement for any signal on the timing of a first cut. No Chilean or Peruvian data releases are scheduled, leaving Andean markets to trade off the BanRep outcome and global risk sentiment.
Peruvian markets will look ahead to the BCRP's November 12 meeting, with the rate at 4.25% and September CPI at 4.55%. Chilean attention shifts to the BCCh's December 15 meeting, the next scheduled decision after this week's hold.
Other Economic Notes
Brent crude's 4.80% collapse to $109.79 is the single largest cross-asset move in the dataset and matters most for Colombia, where oil is a fiscal and external-account anchor; a sustained decline would erode export revenue even as it relieves fuel-subsidy pressure. Copper at $6.59 remains the swing variable for Chile and Peru, and the 0.85% decline reinforces the revenue risk for both mining-heavy economies. Chile's lithium agenda continues to draw policy attention as a medium-term fiscal and investment lever, though near-term price action is dominated by copper.
↓ p.2