Andeans Macro Daily(Beta Mode)
BanRep Hike Eyed as Chile Holds, Copper Slides
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
| MSCI Chile | 35.51 | -1.88% |
| MSCI Peru | 83.73 | -1.05% |
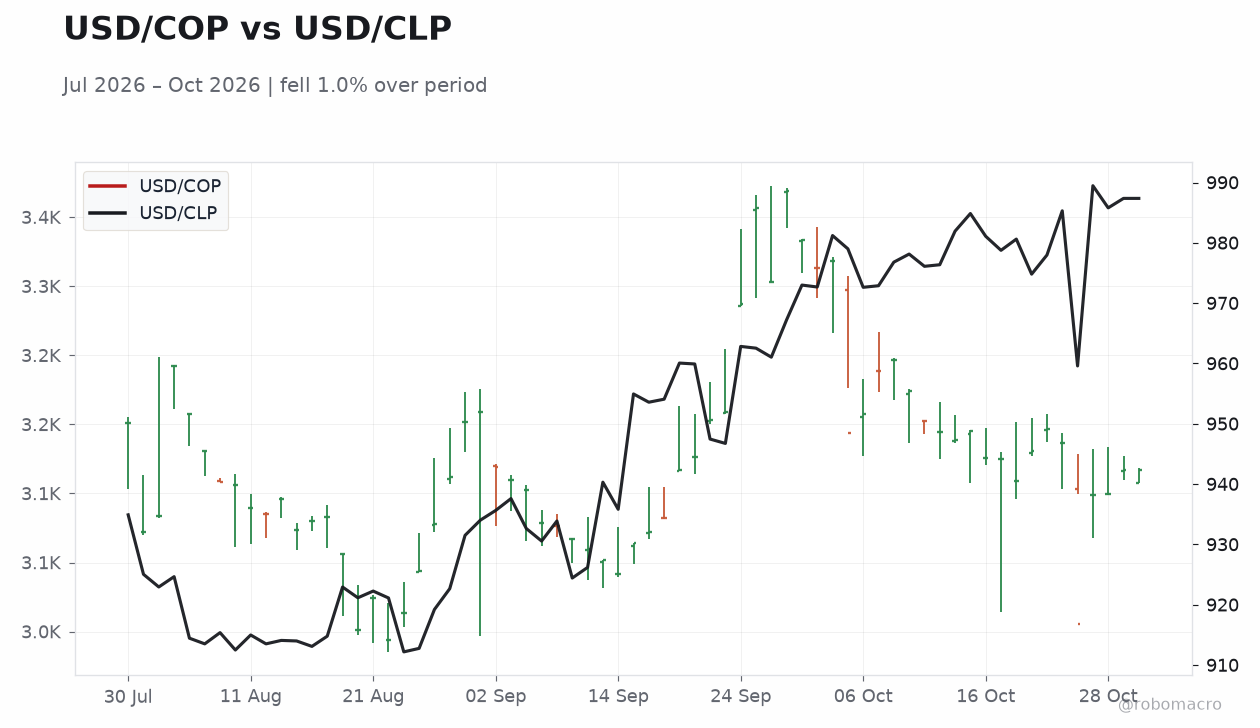
| USD/COP | 3,167.30 | +0.02% |
| USD/CLP | 987.37 | +0.16% |
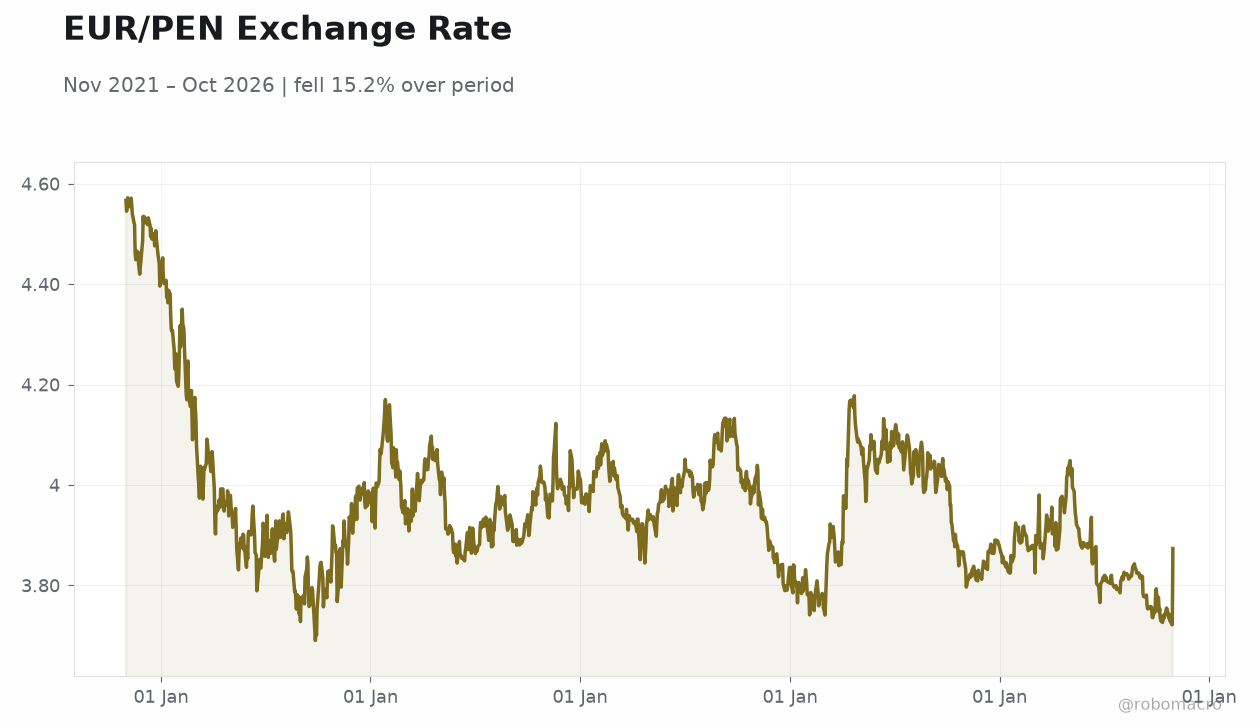
| USD/PEN | 3.46 | +0.23% |
| Copper | 6.51 | -1.07% |
| Gold | 3,994.50 | -0.92% |
| Brent Crude | 113.51 | -1.19% |
| Bitcoin | 77,297.29 | -0.61% |
| Colombia 10Y Govt Yield | - | - |
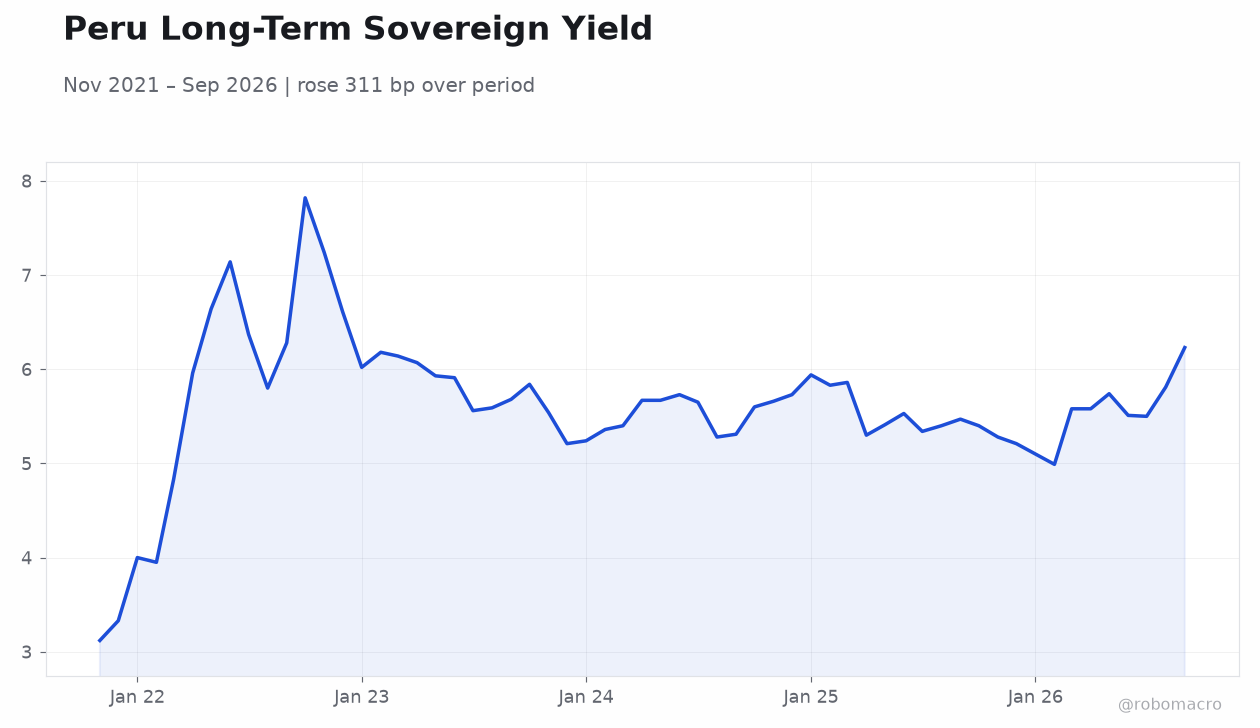
| Peru 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
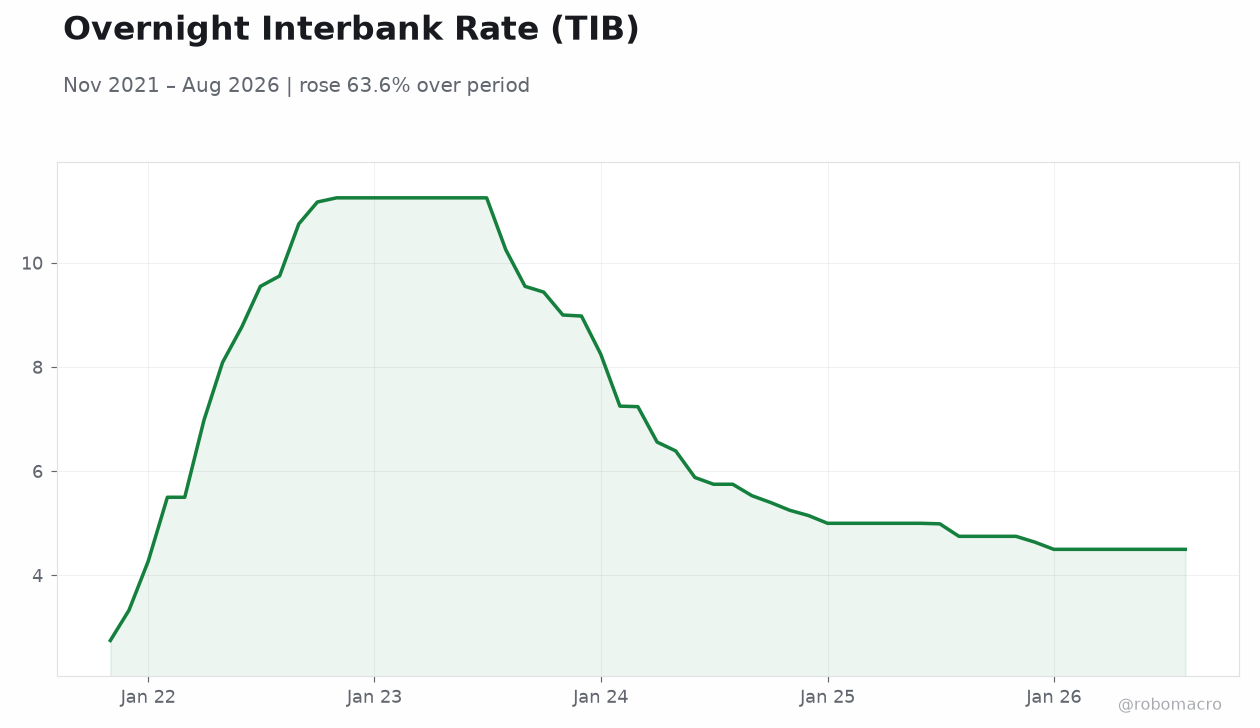
| Central Bank Interest Rate Decision | 4.50 | 4.50 | 4.50 |
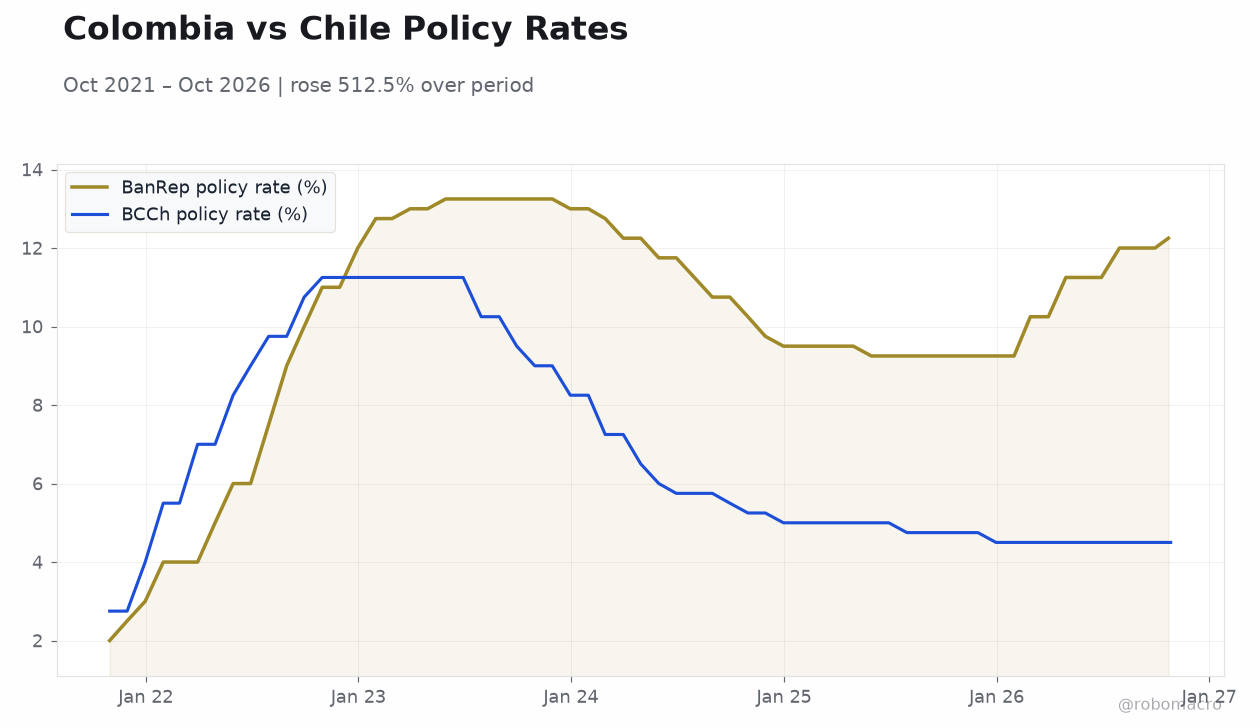 Colombia vs Chile Policy Rates | Type: macro_line | BanRep policy rate (%): 12.25 (2026-10-23) | Range: 2–13.25 | Trend(5pt): 2,12.75,12.25,9.25,12.25 | BCCh policy rate (%): 4.5 (2026-10-27) | Range: 2.75–11.25 | Trend(5pt): 2.75,11.25,6.5,4.75,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Central Bank Interest Rate Decision | 12.25 | 12.25 | 14:00 |
- BanRep is expected to raise its policy rate to 12.50% from 12.25% at today's decision, extending Colombia's hawkish stance amid 6.29% CPI.
- BCCh held at 4.50% on October 27 as an oil shock freezes the cutting cycle and Chilean activity stalls; MSCI Chile fell 1.88%.
- Copper dropped 1.07% to $6.51/lb and Brent fell 1.19% to $113.51, pressuring CLP and PEN while Andean equities softened.
Yesterday's Recap
The BCCh held its policy rate at 4.50% on October 27, in line with consensus, confirming the pause in Chile's easing cycle as an oil-price shock collides with stalling activity. Chilean assets bore the brunt of the risk-off tone: MSCI Chile fell 1.88% and the peso weakened 0.16% to 987.37 per dollar. Peru fared little better, with MSCI Peru down 1.05% and USD/PEN up 0.23% to 3.46 as copper slid 1.07% to $6.51/lb.
Colombia was the outlier, with MSCI Colombia flat and USD/COP essentially unchanged at 3,167.30 (+0.02%) ahead of today's BanRep decision. Regional sentiment was capped by softer commodity prices — Brent down 1.19% to $113.51 and gold off 0.92% — even as the oil shock itself remains the key inflation risk for the bloc. Peruvian and Colombian 10-year yields were unchanged on the day.
The Day Ahead
All eyes are on BanRep's rate decision at 14:00 ET, with consensus pointing to a 25 bp hike to 12.50% from 12.25% — a move that would underscore Colombia's position as the most hawkish central bank in the Andean bloc. The decision carries high impact for COP and the local curve, and the accompanying statement will be scrutinized for guidance on the pace of further tightening given CPI at 6.29%. No Chilean or Peruvian data releases are scheduled for today, leaving flows driven by the BanRep outcome and commodity price action.
Tomorrow's calendar is empty, so today's decision will set the tone into the weekend. Watch COP sensitivity and any spillover into regional rates.
Other Economic Notes
The oil shock is emerging as the dominant macro theme for the Andean bloc, with Chile's rate-cut cycle frozen precisely as its economy begins to contract — a stagflationary combination that limits BCCh's room to maneuver. Colombia's persistent inflation, at 6.29% YoY, keeps BanRep anchored in restrictive territory even as growth concerns build. Peru remains the relative anchor of stability, with CPI at 4.06% and a policy rate of 4.25%, though its currency and equity market remain hostage to copper prices.
Mining sector developments — including Capstone Copper's record quarterly adjusted EBITDA of $358 million and the Mantoverde Optimized Project tie-in — underline copper's centrality to Chilean and Peruvian fiscal and external accounts. Chile's lithium agenda remains a medium-term theme, but near-term attention is squarely on energy costs and inflation pass-through.