Argentina Macro Daily(Beta Mode)
BCRA Lowers Growth Forecasts as Poverty Climbs
Market Snapshot
| Asset | Level | Change |
|---|---|---|
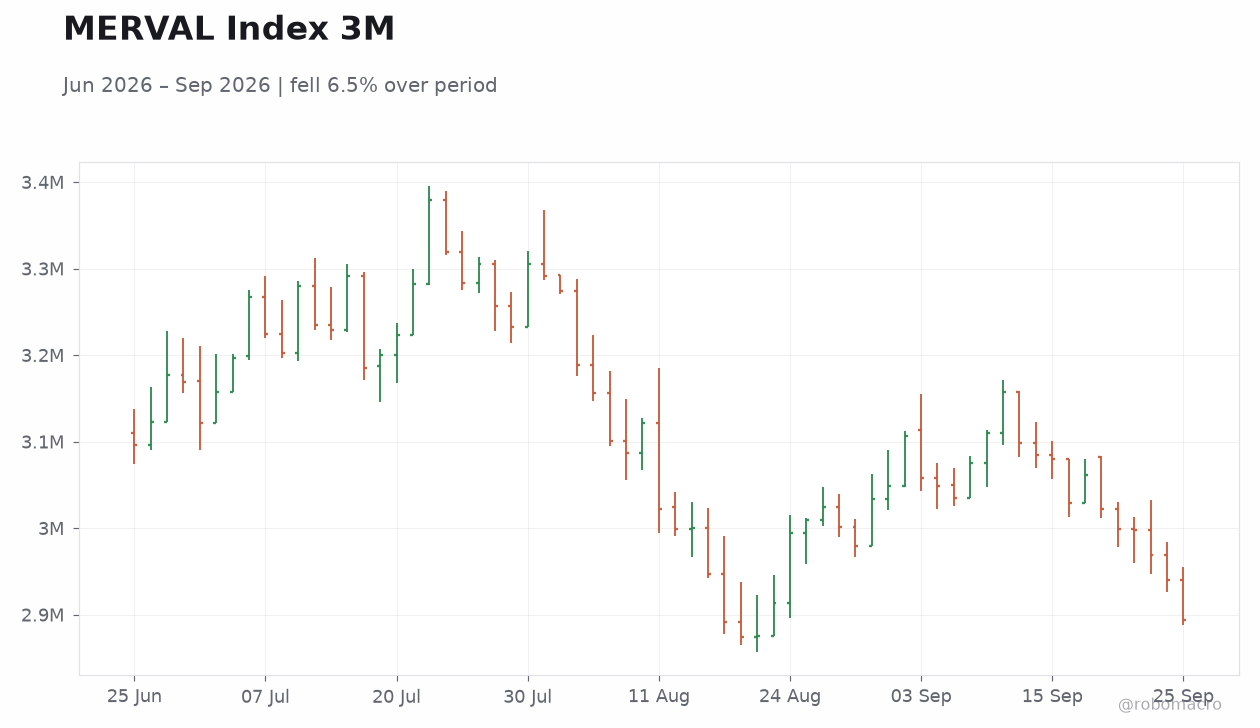
| MERVAL | 2,893,751.00 | -1.57% |
| USD/ARS | 1,524.50 | +0.31% |
| EUR/ARS | 1,736.16 | +0.43% |
| Gold | 4,176.10 | -3.36% |
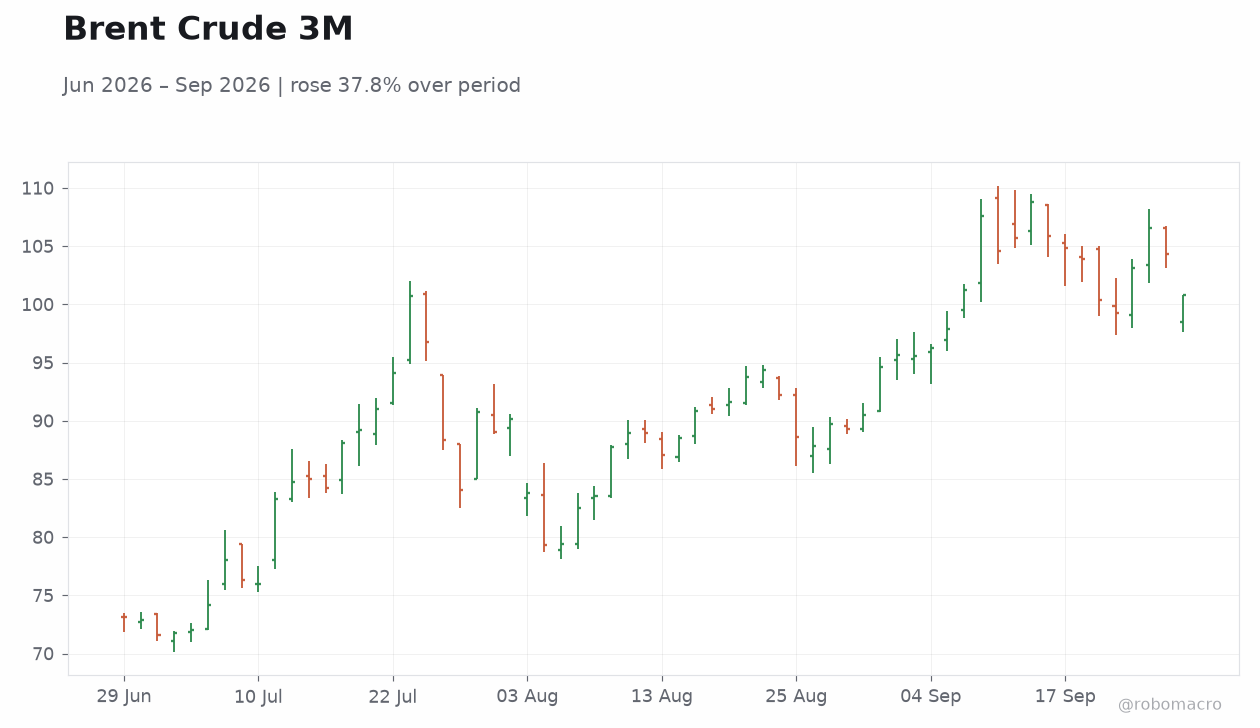
| Brent Crude | 100.75 | -3.42% |
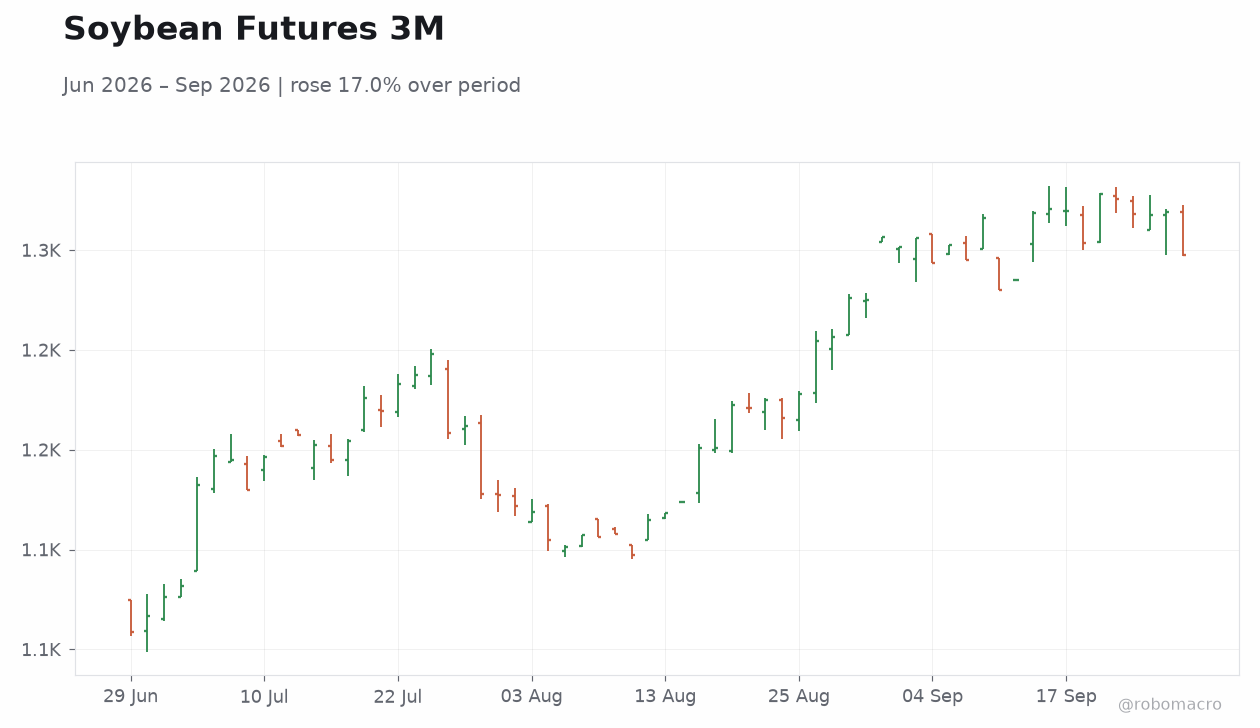
| Soybean | 1,297.50 | -1.63% |
| Bitcoin | 82,713.53 | -2.07% |
| Argentina 10Y | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
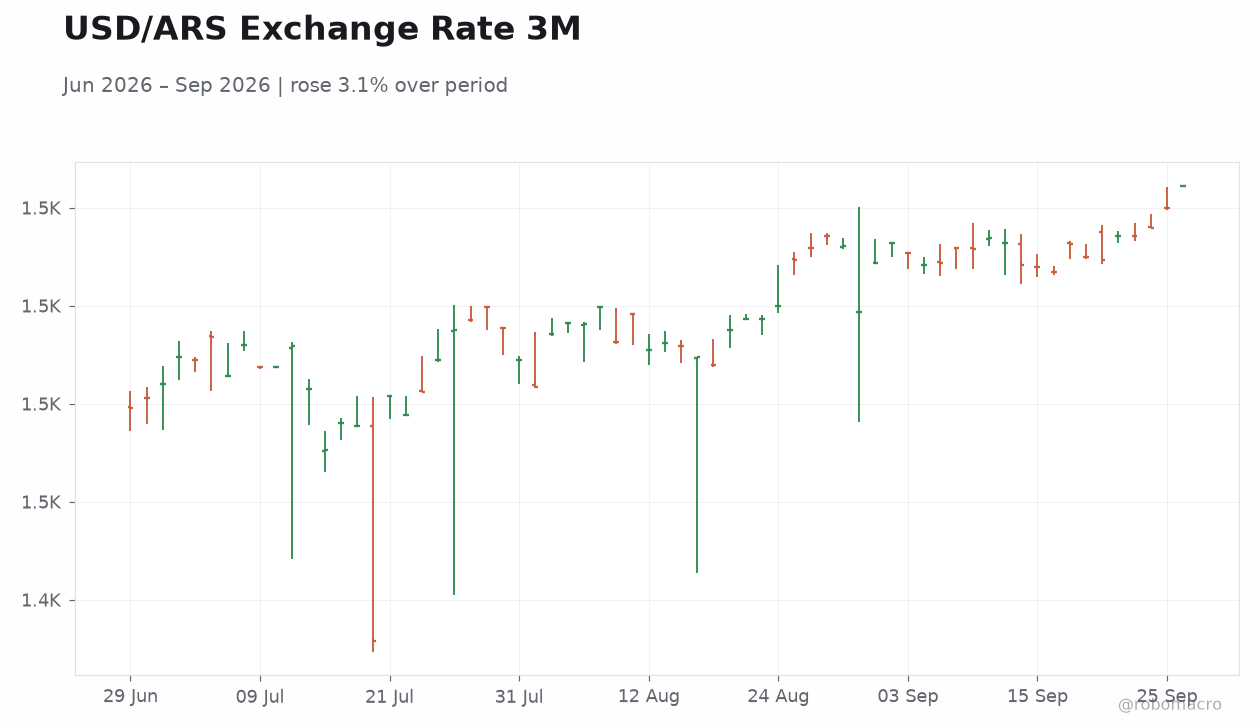 USD/ARS Exchange Rate 3M | Type: market_hloc | USD/ARS: 1524 (2026-09-28) | Range: 1432–1524 | Trend(6pt): 1479,1482,1491,1511,1520,1524
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- MERVAL fell 1.57% while USD/ARS rose 0.31% to 1,524.50 amid thin trading.
- Central Bank lowered growth projections; poverty rate reached 32.3% in H1 2026.
- Argentina 10-year yields near 10% attract buyers despite election risks and 33.8% CPI YoY.
Yesterday's Recap
Equity and commodity markets closed lower while the peso weakened modestly. The MERVAL index fell 1.57% to 2,893,751. USD/ARS rose 0.31% to 1,524.50 and EUR/ARS gained 0.43% to 1,736.16.
Gold declined 3.36% to 4,176.10, Brent Crude dropped 3.42% to 100.75, and Soybean futures eased 1.63% to 1,297.50. Bitcoin fell 2.07% to 82,713.53. The most recent official data showed Argentina’s poverty rate rising to 32.3% in the first half of 2026 from 28.2% previously, with extreme poverty increasing to 7.5% from 6.3%.
Child poverty reached 44.5%. The Central Bank lowered its growth forecasts, pointing to a more cautious outlook for activity and inflation.
The Day Ahead
The calendar shows no data releases or events scheduled for 28 or 29 September. Markets will focus on any follow-up statements from the Central Bank after its downward revision to growth forecasts. Investors continue to monitor soybean export volumes and fiscal consolidation progress under the IMF programme.
Peso liquidity and bond flows remain key watchpoints given the absence of fresh prints. Attention may shift to global commodity prices that directly affect Argentina’s trade balance. With no near-term indicators due, positioning will hinge on external drivers such as Brent Crude and soybean futures, both of which posted notable declines yesterday.
Other Economic Notes
Argentina’s electric-vehicle market expanded 873% year-to-date, contributing to the one-million EV milestone across Latin America. The poverty increase and the Central Bank’s downward revision to growth forecasts remain the dominant domestic themes. Fiscal consolidation efforts continue to anchor investor attention alongside soybean export performance.
Higher 33.8% CPI YoY keeps real interest-rate calculations central to portfolio decisions. Bond buyers are drawn to double-digit yields despite political risks ahead of elections. The combination of softer growth projections and elevated poverty metrics underscores the challenges facing policymakers as they balance inflation control with social stability.