Argentina Macro Daily(Beta Mode)
MERVAL Slides 3.3% on Quiet Calendar
Market Snapshot
| Asset | Level | Change |
|---|---|---|
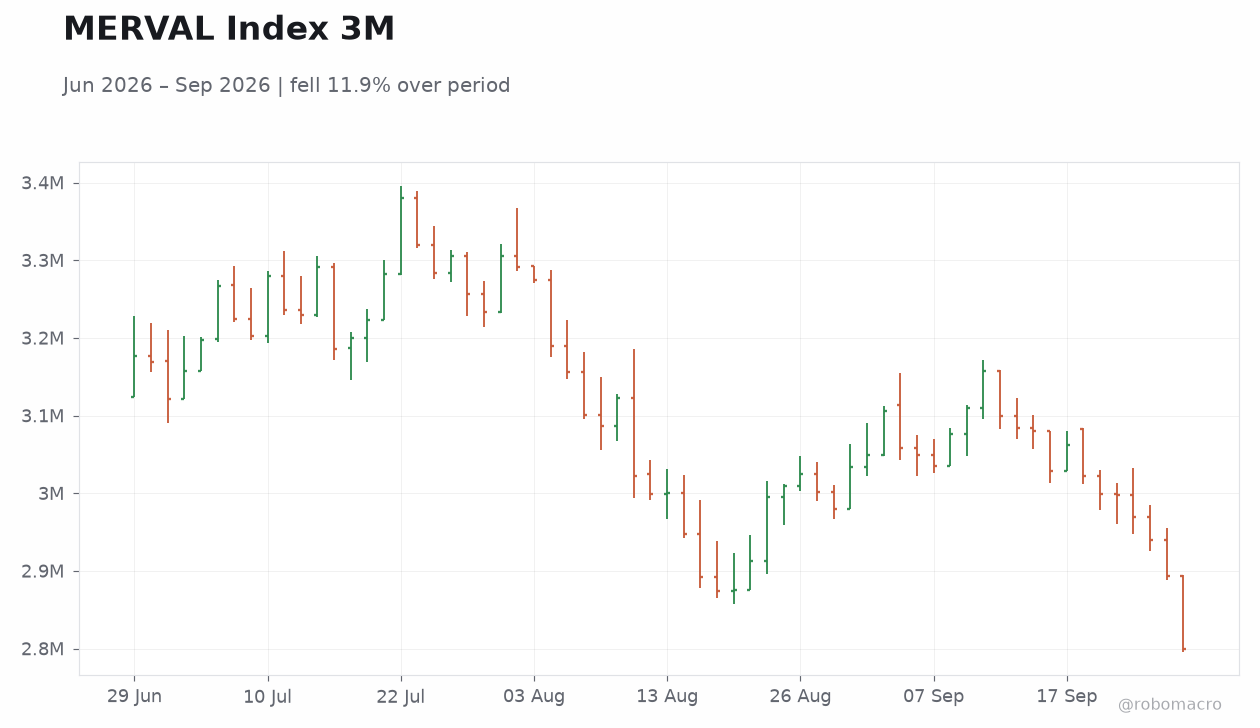
| MERVAL | 2,798,925.00 | -3.28% |
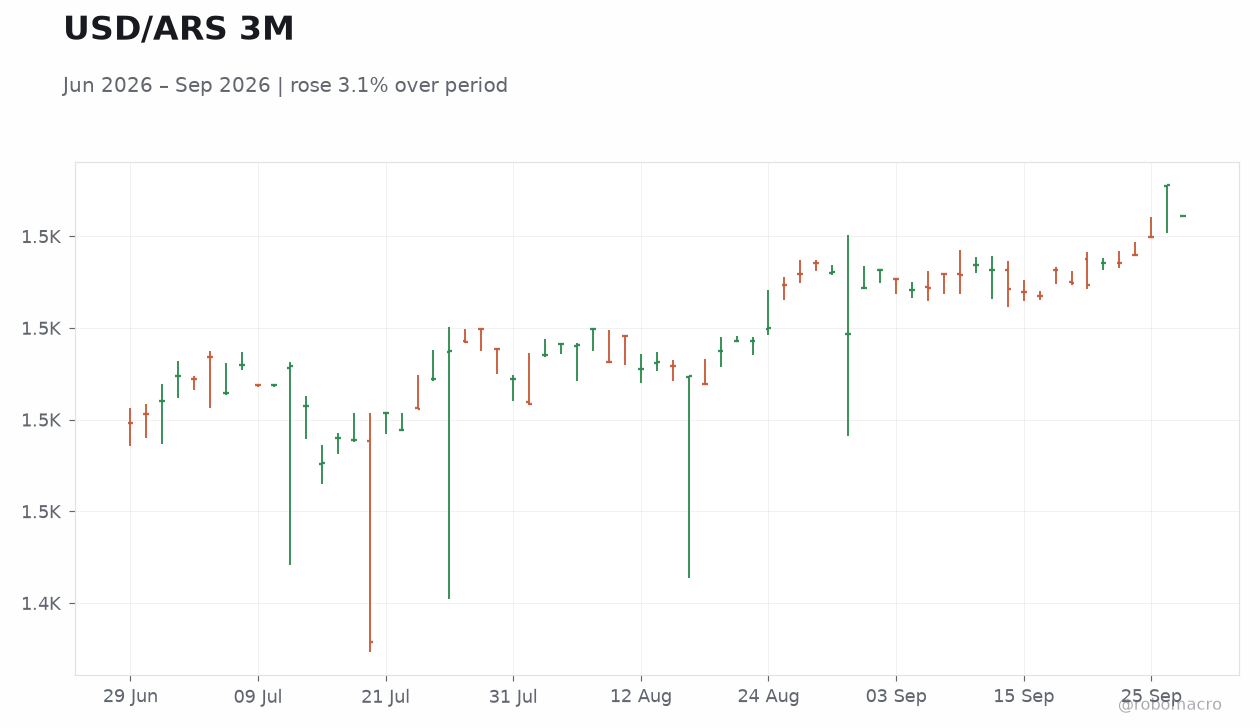
| USD/ARS | 1,524.50 | -0.43% |
| EUR/ARS | 1,732.94 | -0.52% |
| Gold | 4,169.40 | +0.02% |
| Brent Crude | 97.90 | -7.01% |
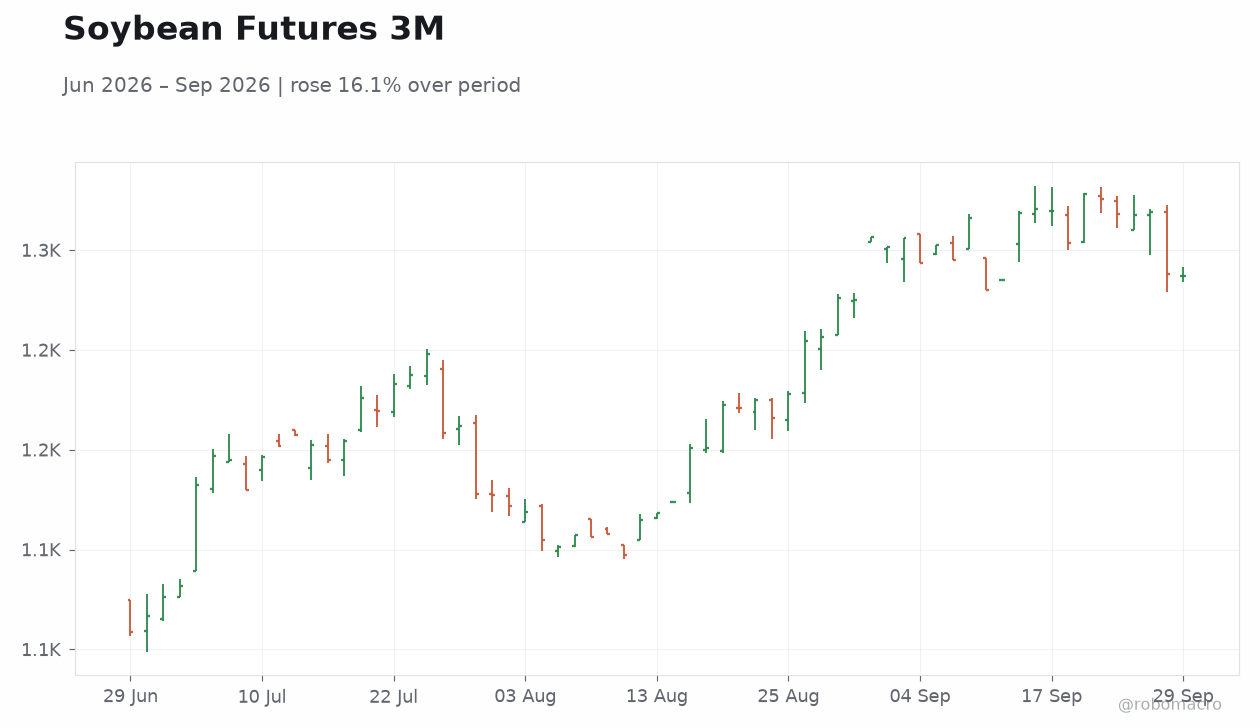
| Soybean | 1,286.75 | -0.12% |
| Bitcoin | 83,761.29 | +0.31% |
| Argentina 10Y | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
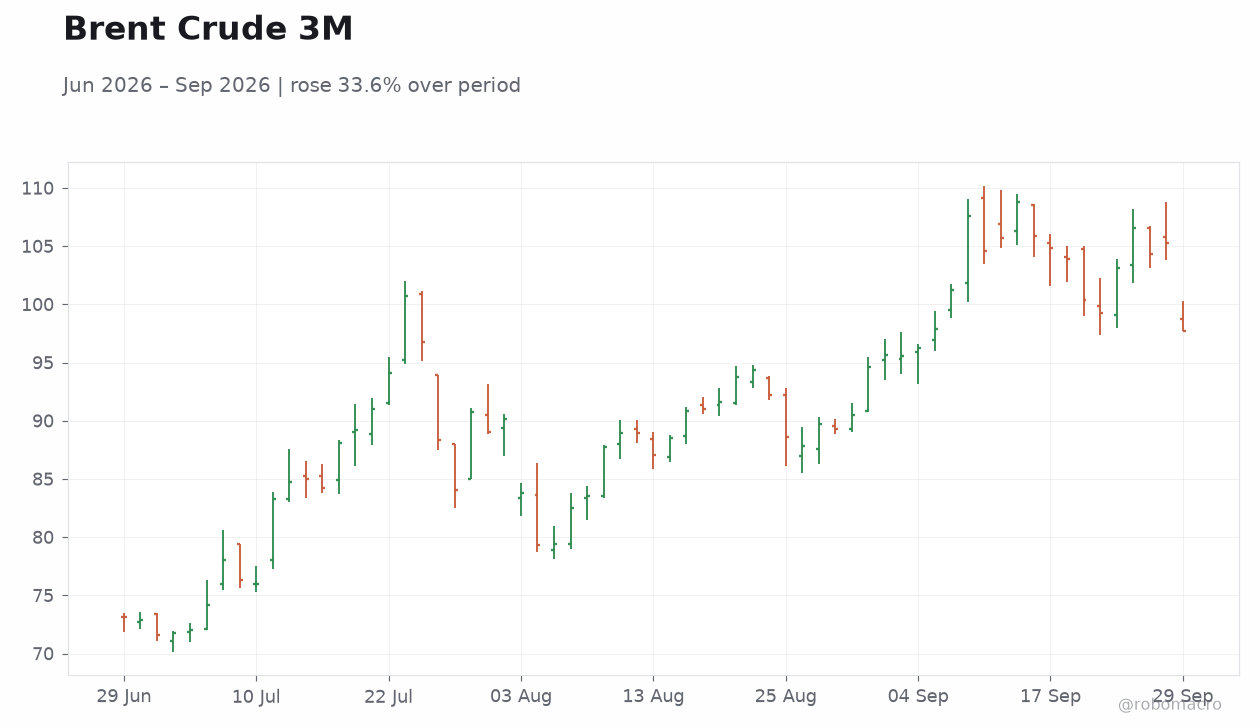 Brent Crude 3M | Type: market_hloc | USD/bbl: 97.75 (2026-09-29) | Range: 71.57–108.8 | Trend(5pt): 73.15,94.07,87.07,96.28,97.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- MERVAL fell 3.28% to 2,798,925 while USD/ARS eased 0.43% to 1,524.50 amid zero data releases.
- Revolut secured BCRA approval to acquire Banco Cetelem Argentina ahead of its 2027 launch.
- President Milei issued a two-week ultimatum to the UK over Falkland Islands oil exploration.
Yesterday's Recap
Equity and FX markets closed lower on September 28 with no economic data prints to shift expectations. The MERVAL index declined 3.28% to 2,798,925.00 while USD/ARS slipped 0.43% to 1,524.50 and EUR/ARS dropped 0.52% to 1,732.94. Brent Crude led commodity moves with a 7.01% decline to 97.90, pressuring export-linked sentiment.
Soybean futures edged down 0.12% to 1,286.75. Revolut received BCRA approval to purchase Banco Cetelem Argentina from BNP Paribas, clearing a regulatory hurdle for its planned 2027 entry. President Javier Milei set a two-week deadline for the UK to halt the Sea Lion oilfield project in the Falklands, threatening legal action otherwise.
Argentina 10Y yields were unavailable. The calendar recorded zero events, so no inflation, activity or fiscal prints emerged to alter consensus views or BCRA policy expectations.
The Day Ahead
No data releases or policy events are scheduled for September 29 or 30. Markets will continue to digest the Revolut approval and Milei’s Falklands ultimatum. Attention remains on soybean export flows and fiscal consolidation progress under the IMF programme.
Peso liquidity conditions and reserve accumulation will stay in focus ahead of the October calendar. Global commodity prices, particularly Brent and soybeans, will influence ARS volatility. Investors await any follow-up statements from BCRA on foreign fintech entry.
The absence of prints keeps focus on external drivers such as commodity prices and capital-flow sensitivity.
Other Economic Notes
Argentina’s CPI YoY stood at 33.5% as of August 31 according to OECD data, underscoring persistent but decelerating price pressures. Fiscal consolidation efforts continue to anchor IMF programme compliance amid limited domestic data flow. Soybean export revenues remain central to reserve rebuilding and current-account dynamics.
Foreign direct investment interest is evident in the Revolut approval, signalling selective regulatory openness. Real wage trends and unemployment data will be monitored closely once releases resume. The Revolut decision aligns with efforts to modernise the financial sector while maintaining oversight of capital flows.