Argentina Macro Daily(Beta Mode)
Milei’s Falklands Threat Weighs on Markets
Market Snapshot
| Asset | Level | Change |
|---|---|---|
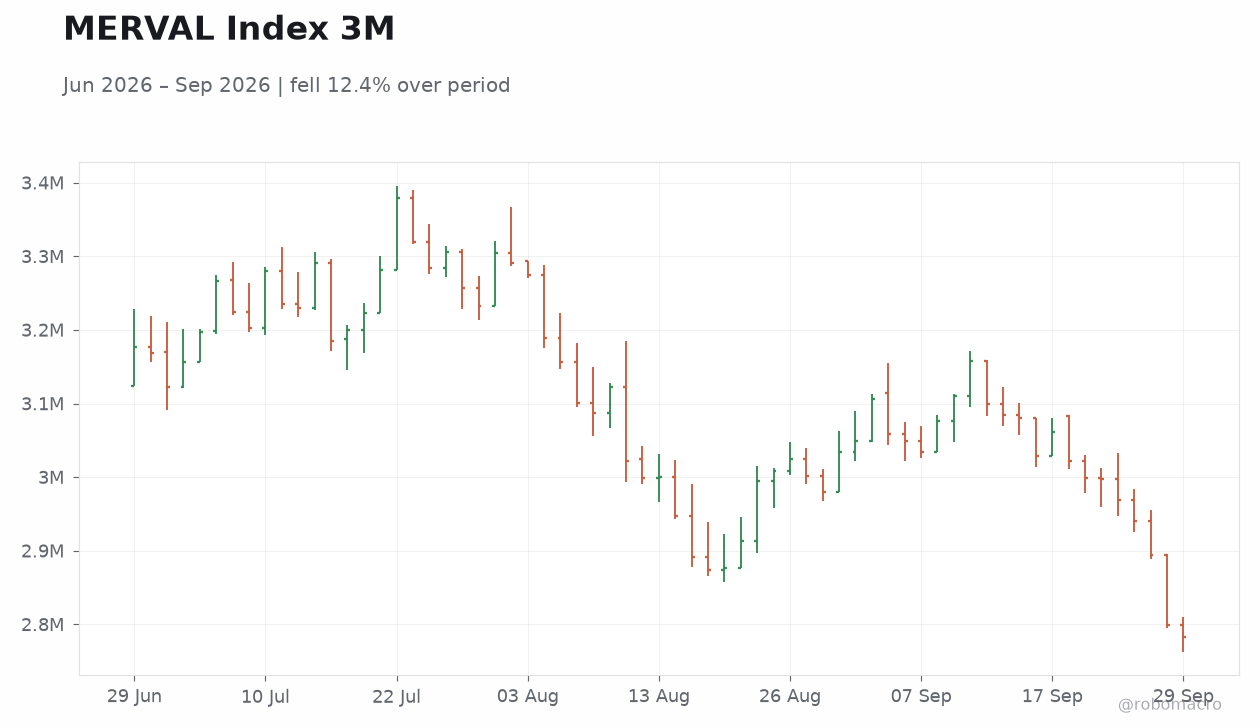
| MERVAL | 2,782,561.00 | -0.58% |
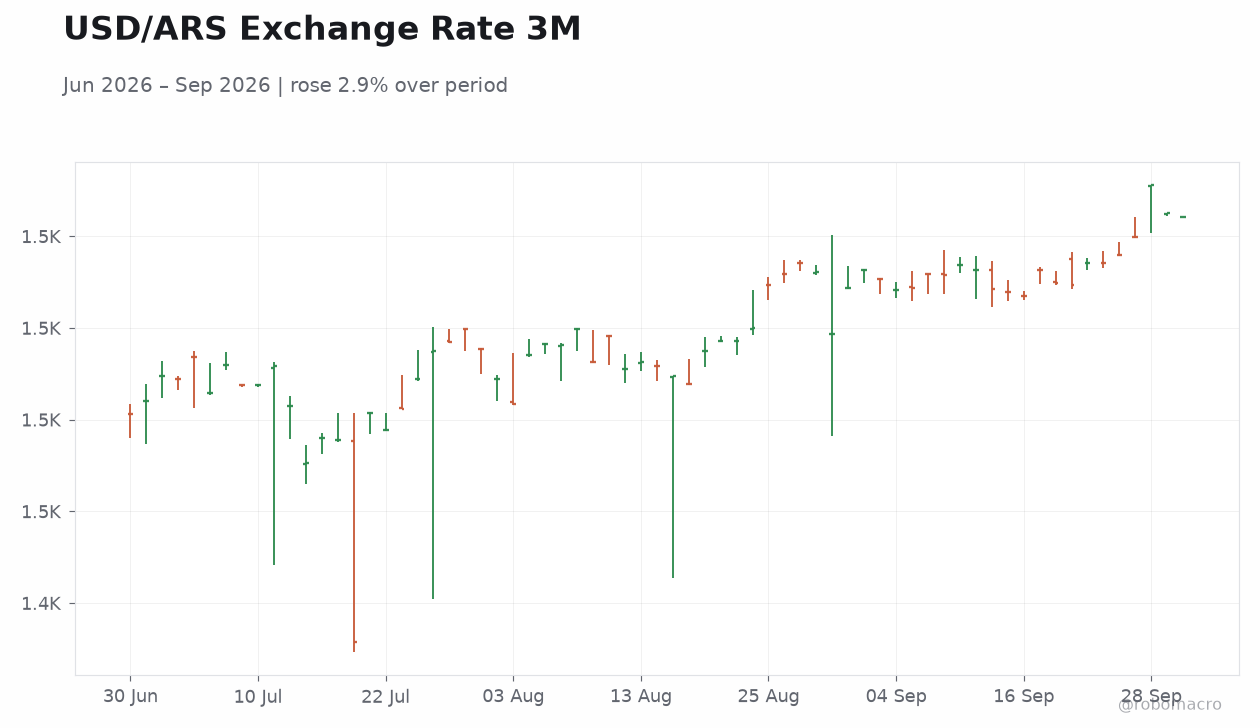
| USD/ARS | 1,524.25 | -0.05% |
| EUR/ARS | 1,727.71 | -0.36% |
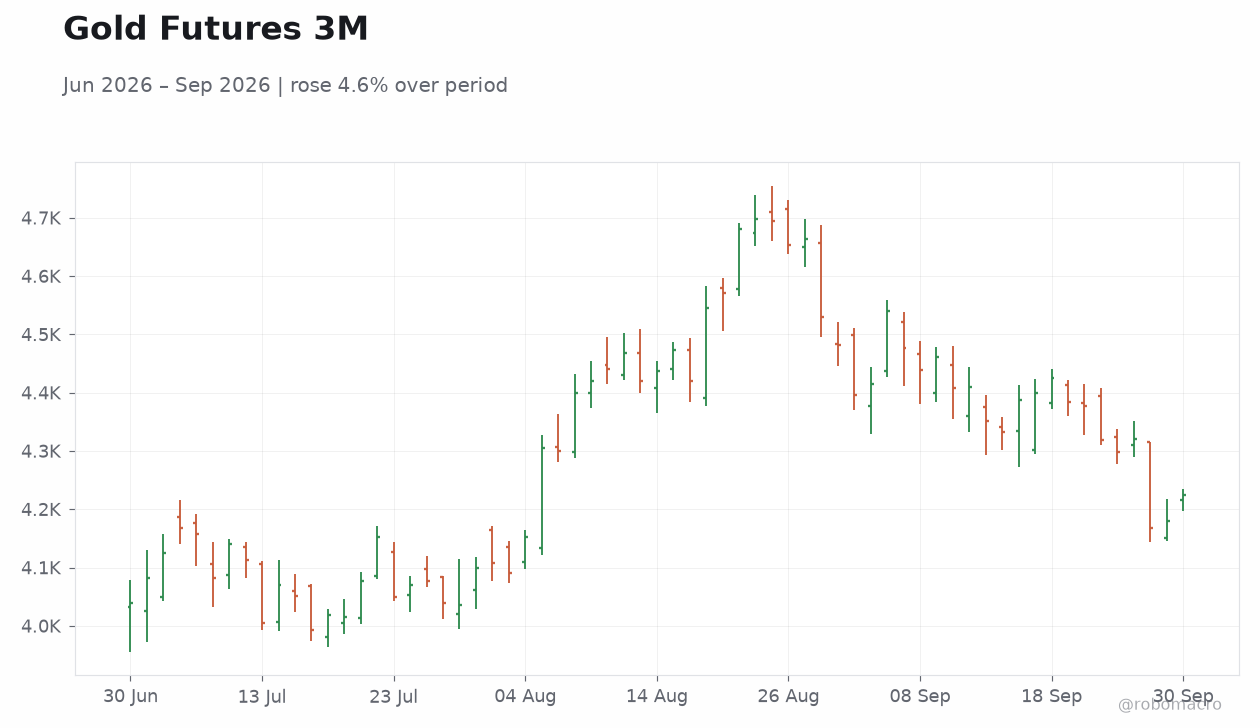
| Gold | 4,224.40 | +1.07% |
| Brent Crude | 96.99 | -5.46% |
| Soybean | 1,300.00 | +0.17% |
| Bitcoin | 83,185.42 | -0.52% |
| Argentina 10Y | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
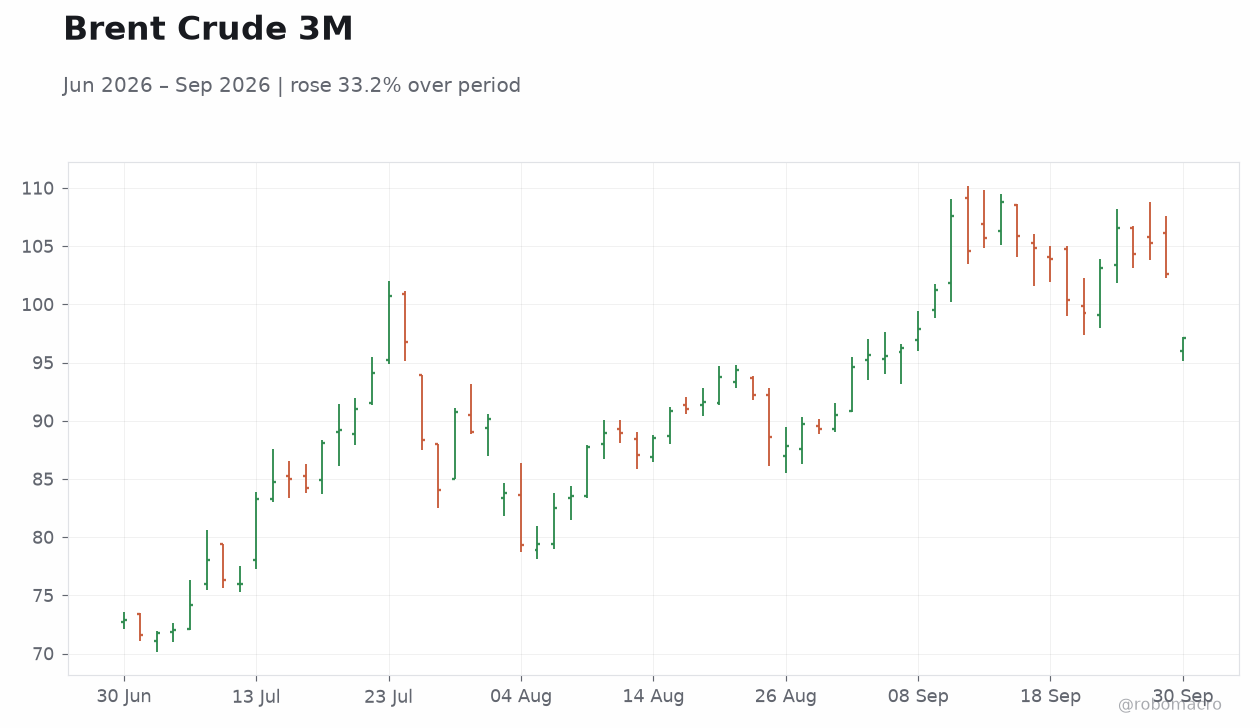 Brent Crude 3M | Type: market_hloc | USD per Barrel: 97.14 (2026-09-30) | Range: 71.57–108.8 | Trend(5pt): 72.92,100.7,88.52,97.92,97.14
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- MERVAL slips 0.58% as Brent crude plunges 5.46%
- USD/ARS holds near 1,524.25 with limited movement
- No data prints leave CPI YoY at 33.5% as latest benchmark
Yesterday's Recap
Equity and FX markets posted modest declines on September 29. The MERVAL index closed at 2,782,561.00, down 0.58%. USD/ARS traded at 1,524.25, easing 0.05%, while EUR/ARS finished at 1,727.71, down 0.36%.
Commodity prices diverged sharply, with gold rising 1.07% to 4,224.40 and Brent crude falling 5.46% to 96.99. Soybean prices edged 0.17% higher to 1,300.00. No economic releases occurred, leaving markets without fresh inflation or activity prints to reassess BCRA policy paths.
President Milei issued a two-week ultimatum to the UK over the Sea Lion oilfield project in the Falklands, threatening legal action and highlighting ongoing sovereignty tensions that could affect energy investment flows.
The Day Ahead
No macroeconomic releases or policy events are scheduled for September 30. The calendar remains empty for October 1 as well. Traders will monitor soybean export volumes and any updates on IMF programme disbursements amid ongoing fiscal consolidation efforts.
Peso liquidity conditions and reserve accumulation trends will stay in focus given the absence of fresh data. Market participants await any Milei administration statements on trade policy or bilateral energy disputes that could influence capital flows.
Other Economic Notes
Soybean export revenues remain central to reserve rebuilding and peso stability. Fiscal consolidation continues to anchor investor sentiment, with primary balance targets under close scrutiny. The 33.5% CPI YoY reading from August underscores persistent price pressures that limit room for BCRA easing.
External financing conditions and IMF reviews will determine the pace of reserve accumulation and debt servicing capacity. Domestic equity performance continues to track commodity price swings and political signals on investment frameworks.
Global Macro News
Australia's central bank raised its cash rate to a 15-year high, citing materialised inflation risks and tightening global financial conditions that could spill into emerging-market funding costs. Asian equities rose as prospects for near-term Federal Reserve rate hikes diminished, supporting risk appetite for assets such as the MERVAL. ↓ p.2