RoboMacro ResearchAlso todaySee the Commodities Daily

Argentina Macro Daily(Beta Mode)

October 13, 2026 robomacro.com

Peso Steady, Merval Slips as Eyes Turn to BCRA

MERVAL2,828,027.00-0.16%
USD/ARS1,516.50+0.00%
EUR/ARS1,694.89-0.32%
Gold4,211.00+0.49%

Market Snapshot

AssetLevelChange
MERVAL2,828,027.00-0.16%
USD/ARS1,516.50+0.00%
EUR/ARS1,694.89-0.32%
Gold4,211.00+0.49%
Brent Crude105.15-1.41%
Soybean1,280.50-0.56%
Bitcoin83,450.64+2.06%
Argentina 10Y--

Prior Economic Events

Data Prior Cons Actual
No events available
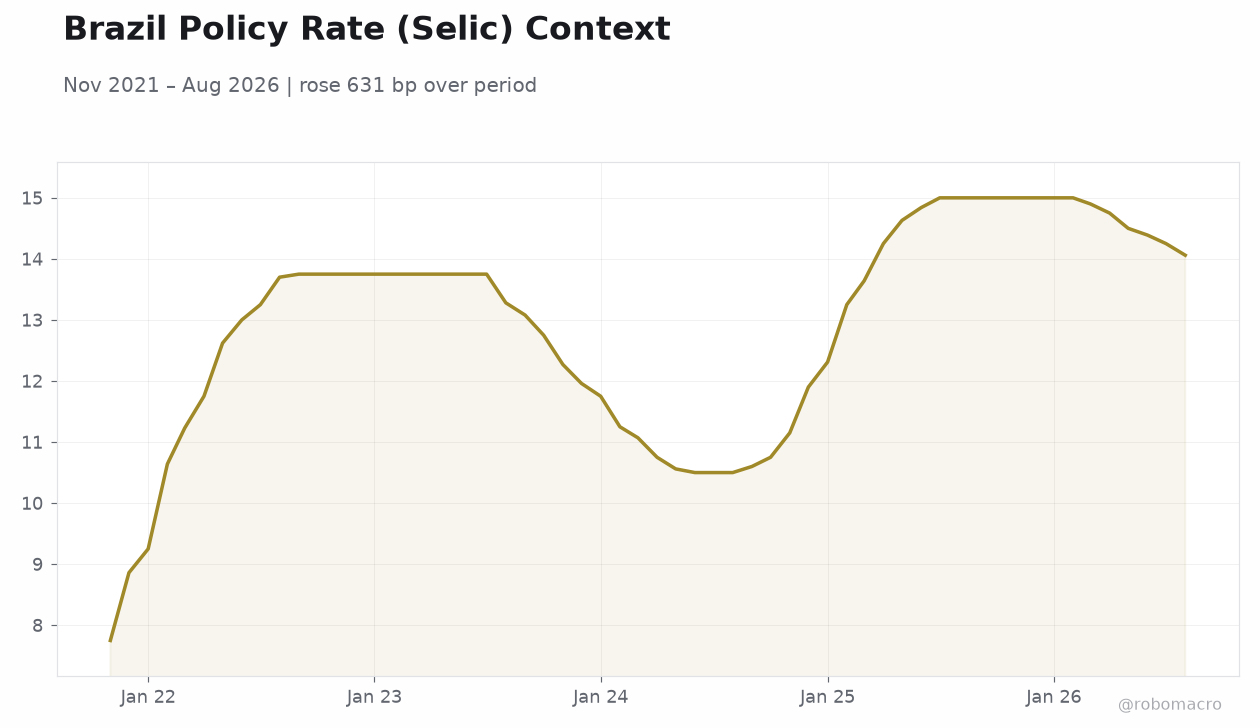
Brazil Policy Rate (Selic) ContextBrazil Policy Rate (Selic) Context | Type: macro_line | Selic Rate (%): 14.06 (2026-08-01) | Range: 7.75–15 | Trend(6pt): 7.75,13.75,11.07,14.63,14.25,14.06

Today's Economic Events

Data Prior Cons Time
No events available
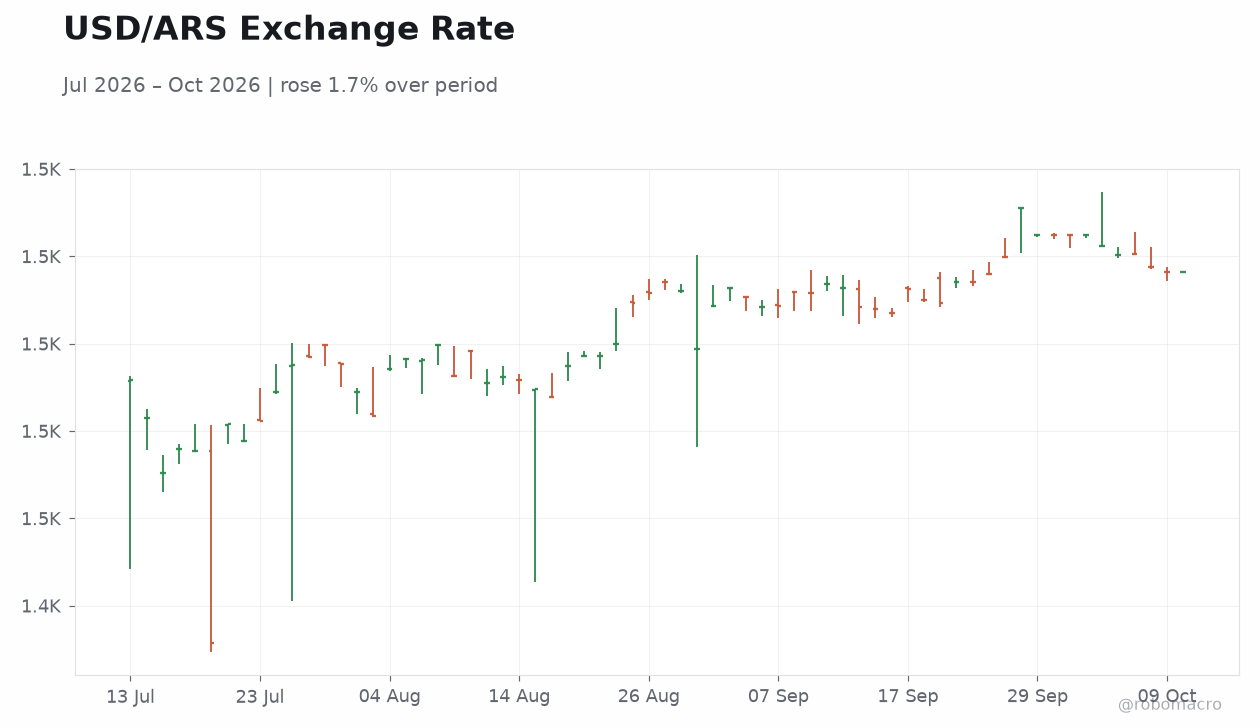
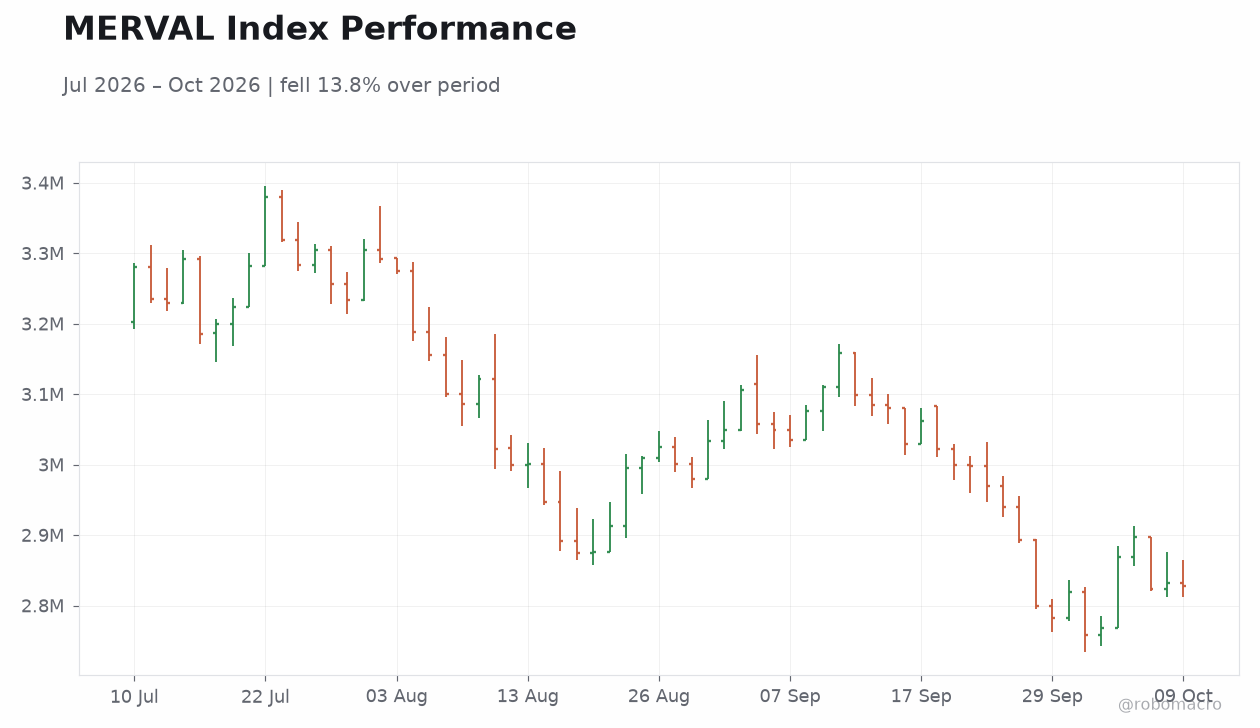
  • USD/ARS held flat at 1,516.50 while the Merval eased 0.16% to 2,828,027 in a quiet session with no scheduled data releases.
  • Soybeans fell 0.56% to $1,280.50, a marginal headwind for Argentina's export-led fiscal consolidation story.
  • Global risk tone improved as Goldman strategists upgraded equities and Bitcoin rallied 2.06%, though hawkish central bank chatter from the Fed, BoE, and RBA kept EM sentiment selective.

Yesterday's Recap

Monday's calendar carried no scheduled Argentine statistical releases, leaving the tape to speak for itself. The Merval closed marginally lower at 2,828,027, down just 0.16%, suggesting investors are holding positions rather than rotating aggressively. The peso was equally calm, with USD/ARS unchanged at 1,516.50, a stability that will be welcomed by officials managing the crawling peg and rebuilding reserves.

The euro weakened against the peso, with EUR/ARS down 0.32% to 1,694.89, reflecting dollar strength broadly rather than any Argentina-specific dynamic. In commodities central to the Argentine trade balance, Brent crude fell 1.41% to $105.15, a mixed signal for the energy account, while soybeans slipped 0.56% to $1,280.50, trimming the dollar value of the harvest still being shipped. Gold rose 0.49% to $4,211, and Bitcoin jumped 2.06% to $83,450, indicating appetite for risk assets persisted even as the local equity index lagged.

With no prints to digest, attention now shifts squarely to the data calendar later this week.

The Day Ahead

The calendar for Tuesday and Wednesday shows no confirmed statistical releases, which argues for a liquidity-driven session where the peso and bonds take their cues from global dollar dynamics and commodity prices. Traders should watch the wholesale FX market for signs of central bank intervention, as BCRA accumulation targets under the IMF programme remain the key intermediate goal even on quiet days. Any movement in the Merval will likely be driven by earnings-related news flow and index rebalancing rather than macro catalysts.

Soybean and corn futures deserve attention given their outsized role in export tax receipts and reserve accumulation. The absence of prints also raises the importance of secondary indicators: overnight rates, the interbank peso market, and bond secondary turnover in instruments like the Bonar and Global series. Positioning into the next CPI print, which last showed 33.5% year-on-year for August, will be the dominant medium-term trade.
Page 1

Argentina Macro Daily(Beta Mode)

October 13, 2026 robomacro.com
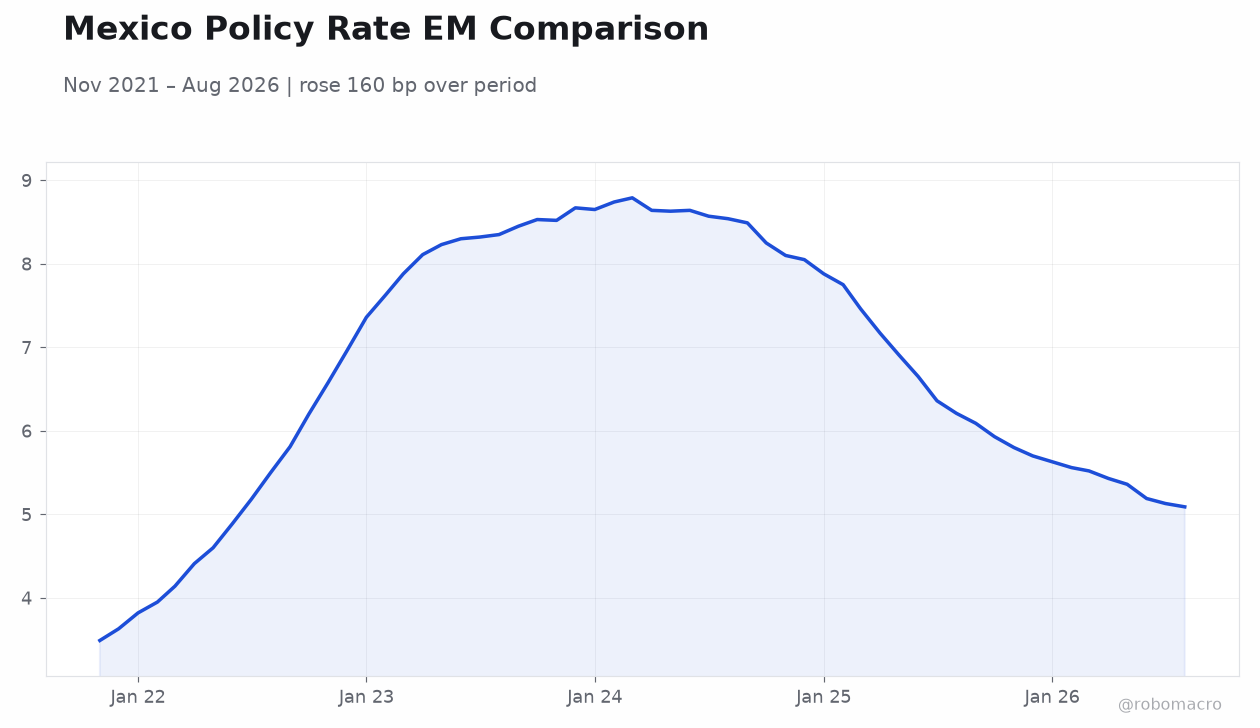
Mexico Policy Rate EM Comparison Mexico Policy Rate EM Comparison | Type: macro_line | Banxico Rate (%): 5.09 (2026-08-01) | Range: 3.49–8.79 | Trend(6pt): 3.49,7.36,8.79,6.91,5.13,5.09
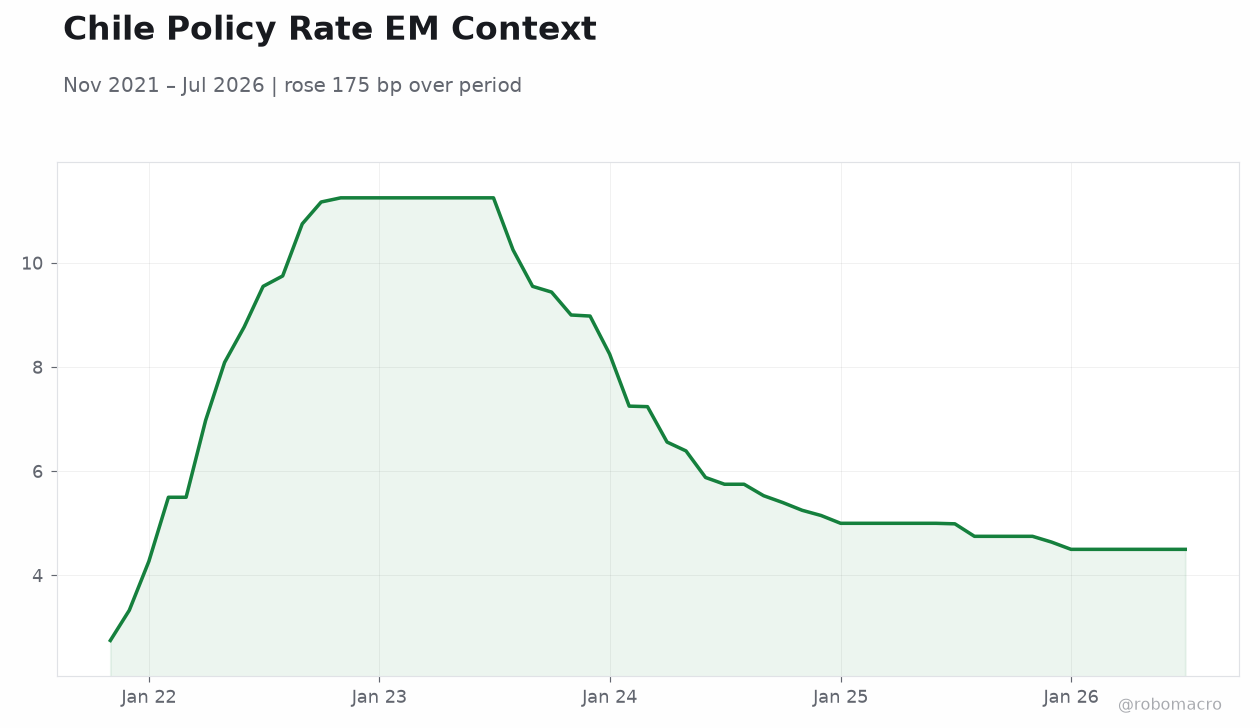
Chile Policy Rate EM Context Chile Policy Rate EM Context | Type: macro_line | Policy Rate (%): 4.5 (2026-07-01) | Range: 2.75–11.25 | Trend(5pt): 2.75,11.25,7.24,5,4.5
USD/ARS Exchange Rate USD/ARS Exchange Rate | Type: market_hloc | ARS per USD: 1516 (2026-10-13) | Range: 1432–1531 | Trend(6pt): 1492,1494,1512,1513,1516,1516
MERVAL Index Performance MERVAL Index Performance | Type: market_hloc | Index Level: 2.828e+06 (2026-10-09) | Range: 2.759e+06–3.38e+06 | Trend(5pt): 3.28e+06,3.274e+06,3.025e+06,3.062e+06,2.828e+06

Other Economic Notes

Argentina's disinflation trajectory remains the central macro achievement of the current policy mix, with August CPI at 33.5% year-on-year confirming a steady glide path from the highs of the stabilisation programme. Fiscal consolidation continues to anchor the IMF review calendar, with the primary surplus target underpinning confidence in the adjustment. The export engine, led by soybeans at $1,280.50 and the broader agricultural complex, faces a softer price environment after Monday's 0.56% decline, a reminder that fiscal revenue tied to retenciones moves with the commodity tape.

Meanwhile, the Iguazu Falls closure due to El Niño flooding is a minor but tangible hit to tourism-related dollar inflows, a small line item in the current account that nonetheless illustrates how climate volatility touches even niche external accounts.

Global Macro News

The global backdrop is turning more hawkish at the margins, with consequences for EM carry trades including Argentina. The Fed's hawkish tilt lifted the dollar and forced a 2.9% slide in the Colombian peso, a cautionary tale for regional currencies. The Bank of England's Megan Greene advocated further rate hikes, while RBA minutes flagged lingering upside inflation risks, and the Bank of Japan signalled readiness for faster tightening.

This synchronised hawkishness supports the dollar, complicating life for peso stability even as USD/ARS held flat at 1,516.50. ↓ p.3

Sponsored by Arbitrage Search
Page 2

Argentina Macro Daily(Beta Mode)

October 13, 2026 robomacro.com

Continuation

Global Macro News (continued)

On the risk-on side, Goldman Sachs strategists upgraded global equities on earnings strength, and BlackRock returned to bonds after six years, signalling a potential rotation that could benefit high-carry sovereign debt. Indonesia's new central bank chief emphasised policy autonomy, echoing a theme relevant to BCRA credibility. India's central bank moved to curb corporate hedging against rupee weakness, another example of EM authorities managing currency pressure.

BCRA Watch

With no formal communications on the calendar, the BCRA's implicit stance must be read from operations rather than statements. The flat USD/ARS print at 1,516.50 suggests the crawling peg is being managed smoothly within its band, and the absence of volatility implies no urgent need for intervention. The Bank's dual mandate, disinflation consistent with 33.5% August CPI and reserve accumulation under the IMF programme, argues for maintaining a restrictive monetary stance even as inflation decelerates.

Markets should watch for any adjustment to the pace of the crawling peg, which would be the first concrete signal of a shift toward greater exchange rate flexibility. Secondary-market yields on peso-denominated instruments remain the best real-time gauge of expectations for the policy rate path. For now, the message is continuity: fiscal dominance is fading, the BCRA is rebuilding its balance sheet, and the hurdle rate for peso assets remains attractive in real terms.

Any commentary accompanying the next inflation print will be scrutinised for hints on the timing of the first meaningful rate cut. Until then, expect the Bank to let the high real rate do the work of anchoring expectations while sterilising peso liquidity to defend the disinflation glide path.

Sponsored by Arbitrage Search
Page 3