Argentina Macro Daily(Beta Mode)
Milei Reforms Spur Energy Export Boom
Market Snapshot
| Asset | Level | Change |
|---|---|---|
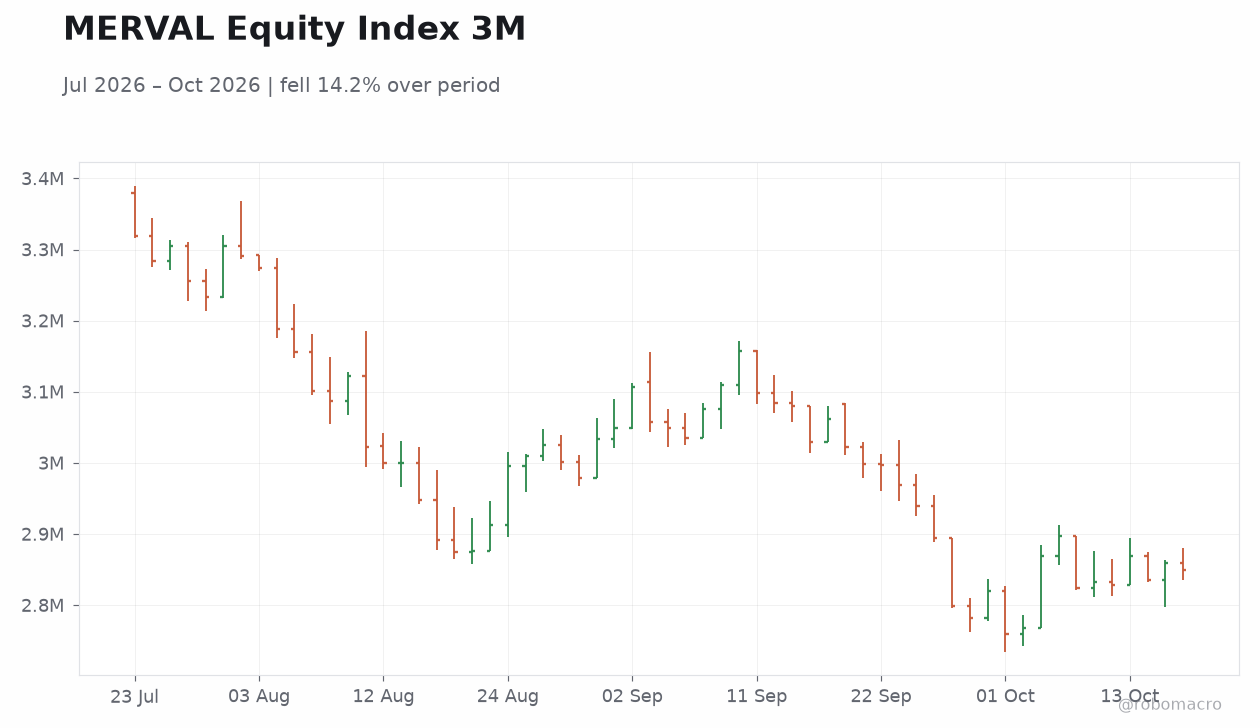
| MERVAL | 2,848,945.00 | -0.35% |
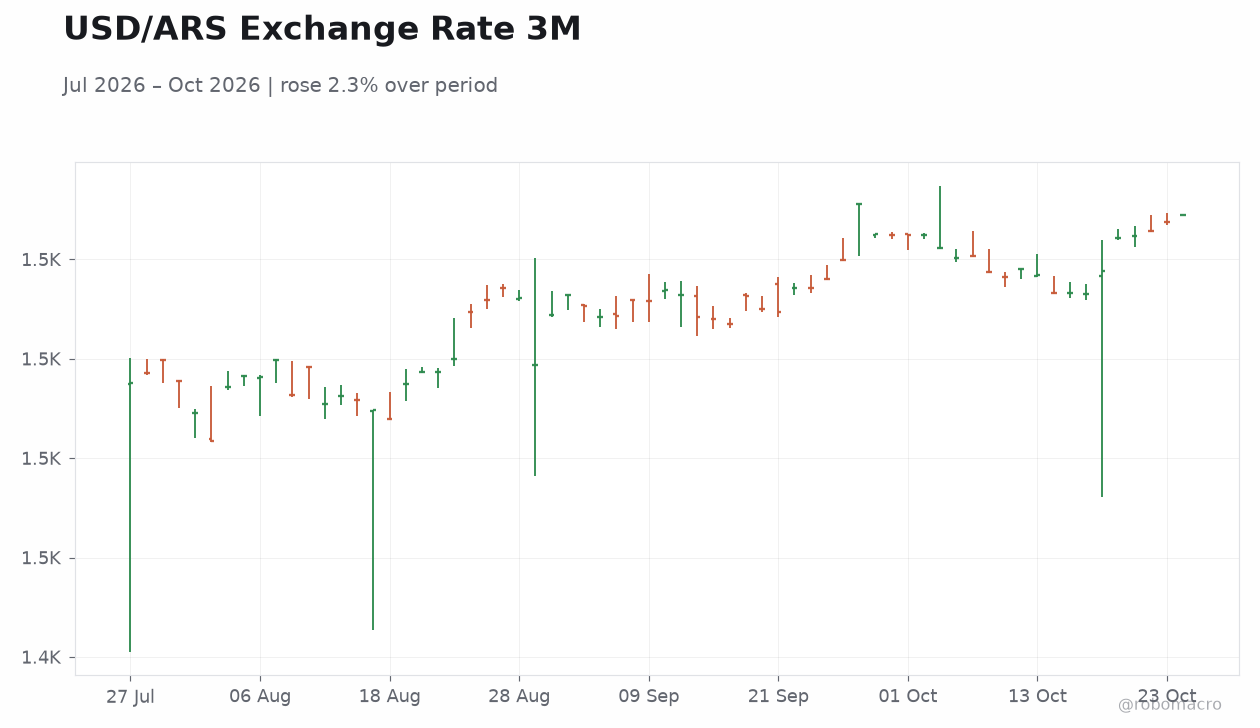
| USD/ARS | 1,529.00 | +0.10% |
| EUR/ARS | 1,716.46 | +0.14% |
| Gold | 4,029.70 | +0.54% |
| Brent Crude | 109.66 | -6.05% |
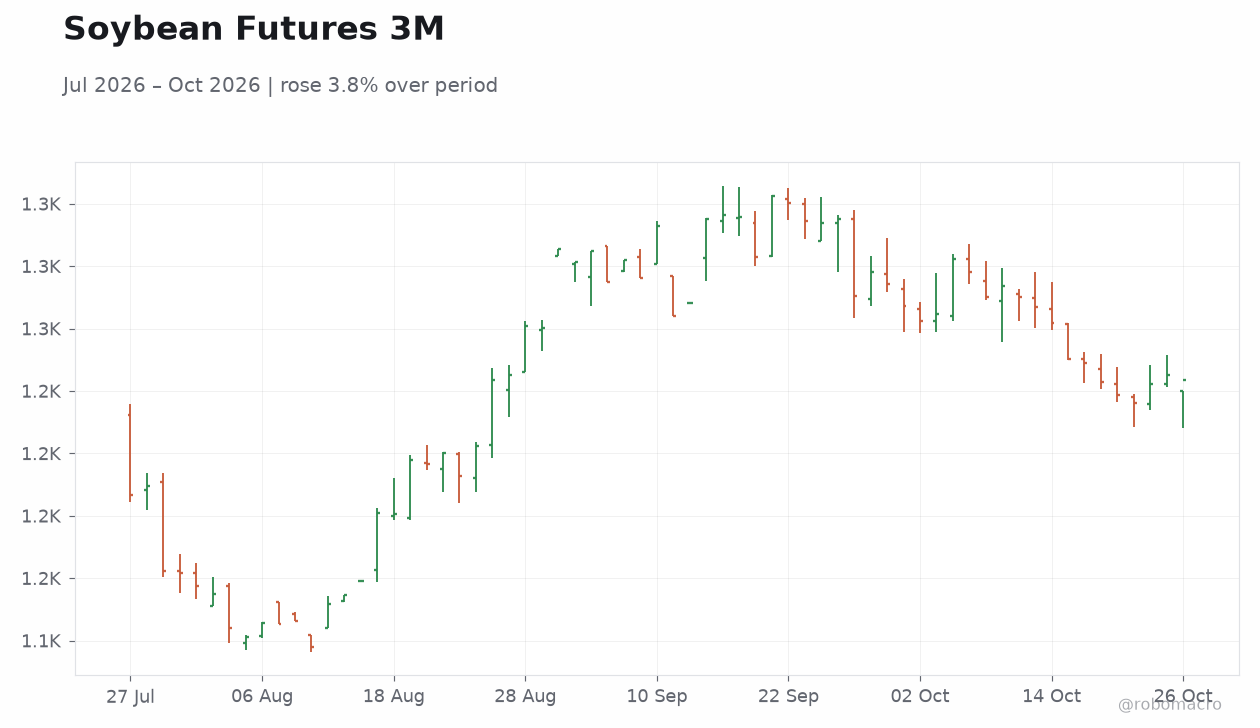
| Soybean | 1,254.25 | -0.18% |
| Bitcoin | 80,160.68 | +0.17% |
| Argentina 10Y | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
 Brent Crude Oil 3M | Type: market_hloc | Brent USD/bbl: 109.7 (2026-10-26) | Range: 79.36–116.7 | Trend(5pt): 88.36,91.02,107.6,102.2,109.7
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- MERVAL slips 0.35% as peso edges weaker on thin volumes
- CPI at 33.4% YoY confirms ongoing disinflation path
- Global rate decisions raise EM capital-flow risks for Argentina
Yesterday's Recap
Equity markets closed lower with the MERVAL index declining 0.35% to 2,848,945 amid quiet trading and no major data prints. The peso posted modest losses as USD/ARS advanced 0.10% to 1,529.00 while EUR/ARS rose 0.14%. Brent crude’s 6.05% drop to 109.66 weighed on commodity-linked sentiment despite soybean prices holding near 1,254.25.
Authorities dropped the investigation into President Milei’s crypto-related social-media post, removing a political overhang and supporting risk appetite. The Bloomberg analysis underscored two distinct Argentinas emerging under Milei, with inflation tamed and fresh investment flowing into energy and export sectors. Gold’s 0.54% gain to 4,029.70 offered a partial offset for local portfolios.
Bitcoin’s small advance to 80,160.68 reflected broader crypto stabilization after the Milei news.
The Day Ahead
Attention shifts to fiscal-consolidation updates and trade-balance figures expected later this week. Soybean export proceeds will dictate near-term reserve accumulation and peso support. Investors await any BCRA commentary on reserve-management tactics ahead of month-end flows.
Energy-project financing announcements could reinforce the investment narrative highlighted in recent coverage. Broader Milei reform momentum remains the dominant driver for sentiment, with no calendar events scheduled to shift the baseline outlook. Peso stability will hinge on sustained export receipts and continued adherence to IMF targets.
Other Economic Notes
The 33.4% YoY CPI reading through September reinforces the disinflation trajectory that has underpinned market confidence. Fiscal tightening continues to target primary surpluses, freeing resources for debt service and reserve rebuilding. Export-oriented sectors, especially energy and agriculture, stand to benefit from improved access to foreign capital under the current policy mix.
IMF program compliance stays central to medium-term debt sustainability and renewed market access. These domestic anchors limit spillovers from external volatility while the administration advances structural opening.