RoboMacro ResearchAlso todaySee the US Macro Daily

Argentina Macro Daily(Beta Mode)

November 10, 2026 robomacro.com

Pope Rebukes Milei as Peso, Merval Slip

MERVAL2,848,945.00-0.35%
USD/ARS1,545.25+0.05%
EUR/ARS1,733.93+0.71%
Gold4,108.90-0.14%

Market Snapshot

AssetLevelChange
MERVAL2,848,945.00-0.35%
USD/ARS1,545.25+0.05%
EUR/ARS1,733.93+0.71%
Gold4,108.90-0.14%
Brent Crude90.39-2.35%
Soybean1,194.75+1.06%
Bitcoin74,237.50-1.31%
Argentina 10Y--

Prior Economic Events

Data Prior Cons Actual
No events available
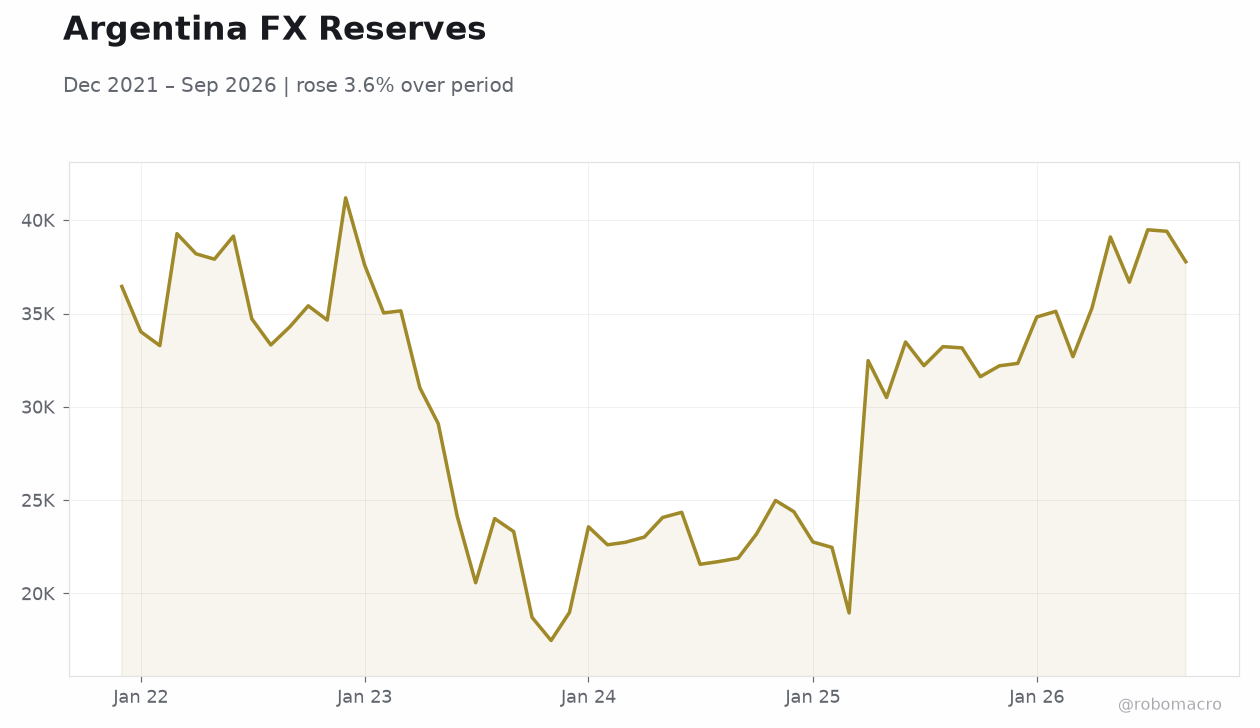
Argentina FX ReservesArgentina FX Reserves | Type: macro_line | FX Reserves (USD): 3.777e+04 (2026-09-01) | Range: 1.748e+04–4.12e+04 | Trend(6pt): 3.645e+04,3.503e+04,2.302e+04,3.347e+04,3.941e+04,3.777e+04

Today's Economic Events

Data Prior Cons Time
No events available
  • Pope Leo XIV publicly criticizes Milei's austerity program during Argentina visit, injecting political risk into the reform narrative
  • Merval edges down 0.35% to 2,848,945 while the official peso holds near 1,545 per dollar despite broad dollar strength
  • Soybean futures gain 1.06% as India's oilmeal imports shift toward Argentine supply, offering a modest export-revenue tailwind

Yesterday's Recap

Argentine markets opened the week on a defensive footing, with the Merval shedding 0.35% to close at 2,848,945 points as investors weighed political noise against the macro consolidation story. The official USD/ARS rate held essentially flat at 1,545.25, a 0.05% move that underscores how tightly the crawling peg is being managed even as the dollar firms globally. The euro strengthened 0.71% against the peso to 1,733.93, reflecting broad greenback dynamics rather than idiosyncratic Argentina flow.

Argentina's 10-year sovereign yield was not quoted in the latest data feed, leaving investors to lean on secondary-market color and the recent compression trend. Soybean futures rose 1.06% to 1,194.75, a constructive signal for the Rosario crush complex and the export dollars that underpin BCRA reserve accumulation. Brent crude fell 2.35% to 90.39, trimming imported energy costs and offering marginal relief to the trade balance.

The dominant non-market event was Pope Leo XIV's pointed critique of Milei's austerity, which framed the political backdrop for the session.

The Day Ahead

The domestic calendar is empty for November 10, with no scheduled Argentine data releases, leaving markets to trade off external drivers and political headlines. Attention centers on follow-through from the Pope's visit and whether the government adjusts its communication on the social cost of fiscal adjustment. Traders will watch the official FX window for any acceleration in the crawling peg and monitor parallel-market spreads for signs of stress.

Soybean and energy price moves remain the key swing factors for export revenue and import costs. With no local prints, positioning will likely be driven by global risk appetite and US rate expectations ahead of midweek data.

Other Economic Notes

The disinflation trajectory remains the anchor of the macro story, with CPI at 33.4% year-on-year as of September, a level that keeps real-rate policy firmly restrictive. Fiscal consolidation continues to run a primary surplus, but the political economy of subsidy cuts and utility tariff adjustments is becoming harder as social pressure mounts. ↓ p.2
Page 1

Argentina Macro Daily(Beta Mode)

November 10, 2026 robomacro.com
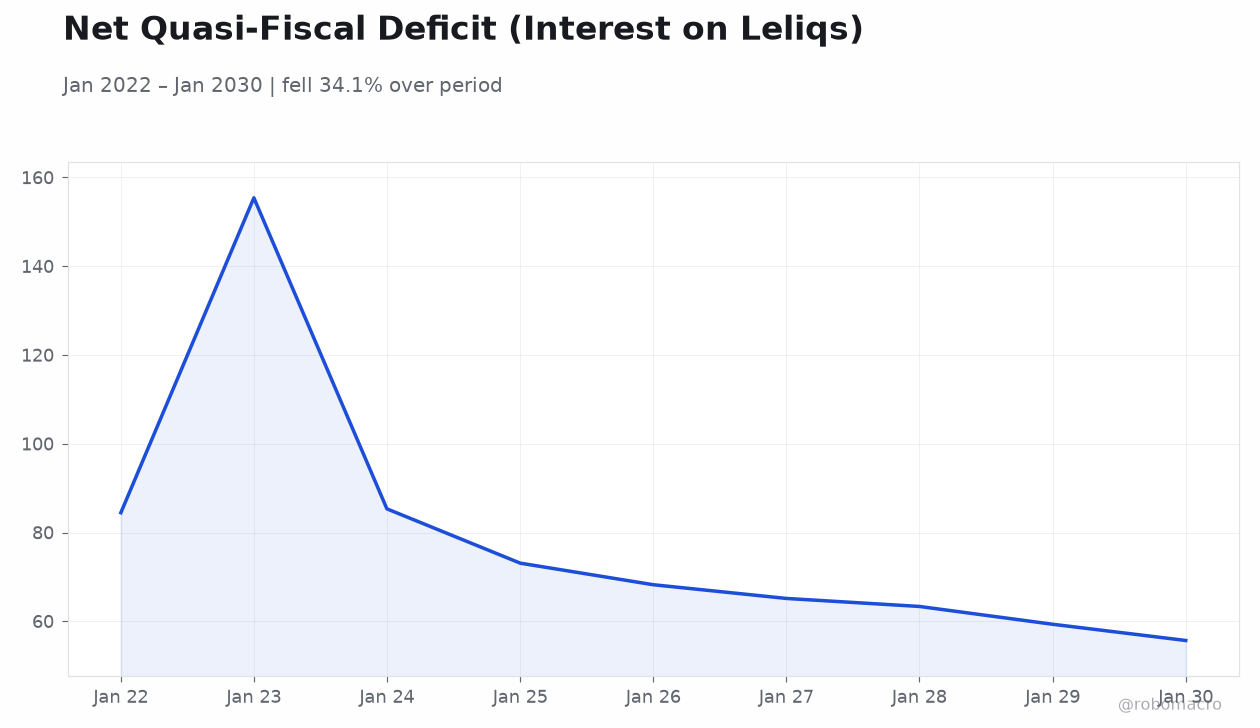
Net Quasi-Fiscal Deficit (Interest on Leliqs) Net Quasi-Fiscal Deficit (Interest on Leliqs) | Type: macro_line | Net Quasi-Fiscal Deficit (Interest on Leliqs): 55.67 (2030-01-01) | Range: 55.67–155.4 | Trend(5pt): 84.46,85.33,68.23,63.34,55.67
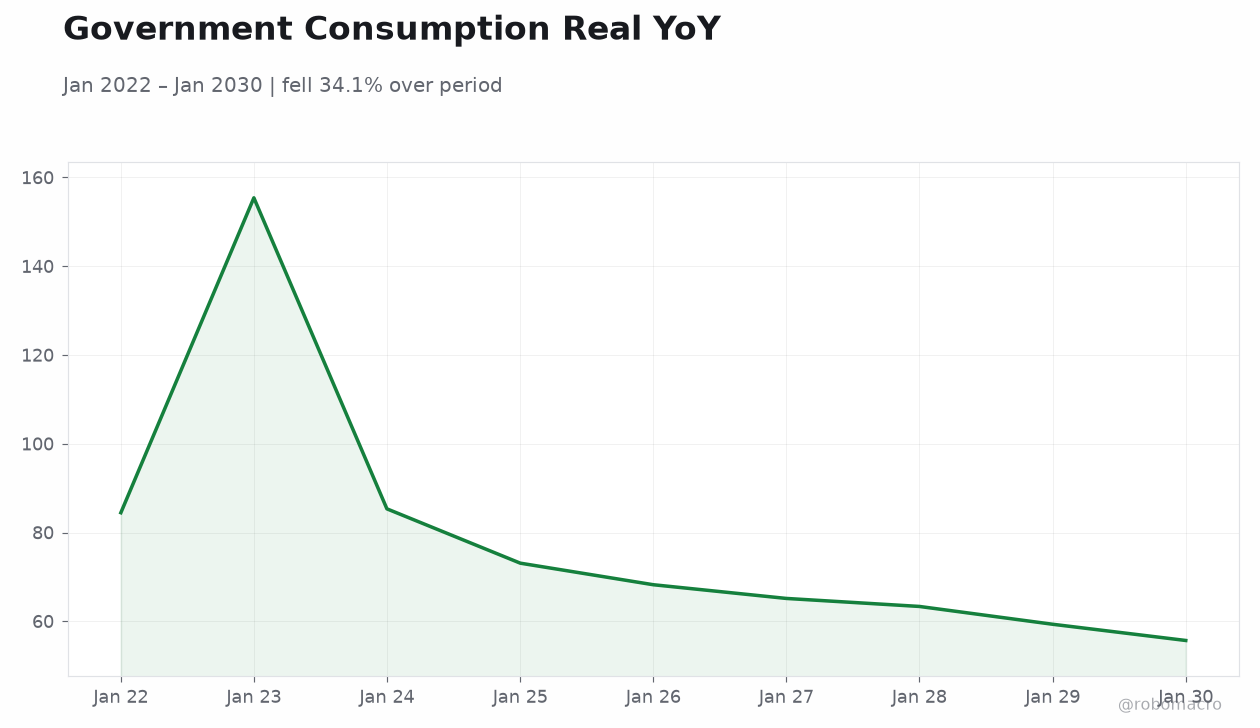
Government Consumption Real YoY Government Consumption Real YoY | Type: macro_line | Government Consumption Real YoY: 55.67 (2030-01-01) | Range: 55.67–155.4 | Trend(5pt): 84.46,85.33,68.23,63.34,55.67
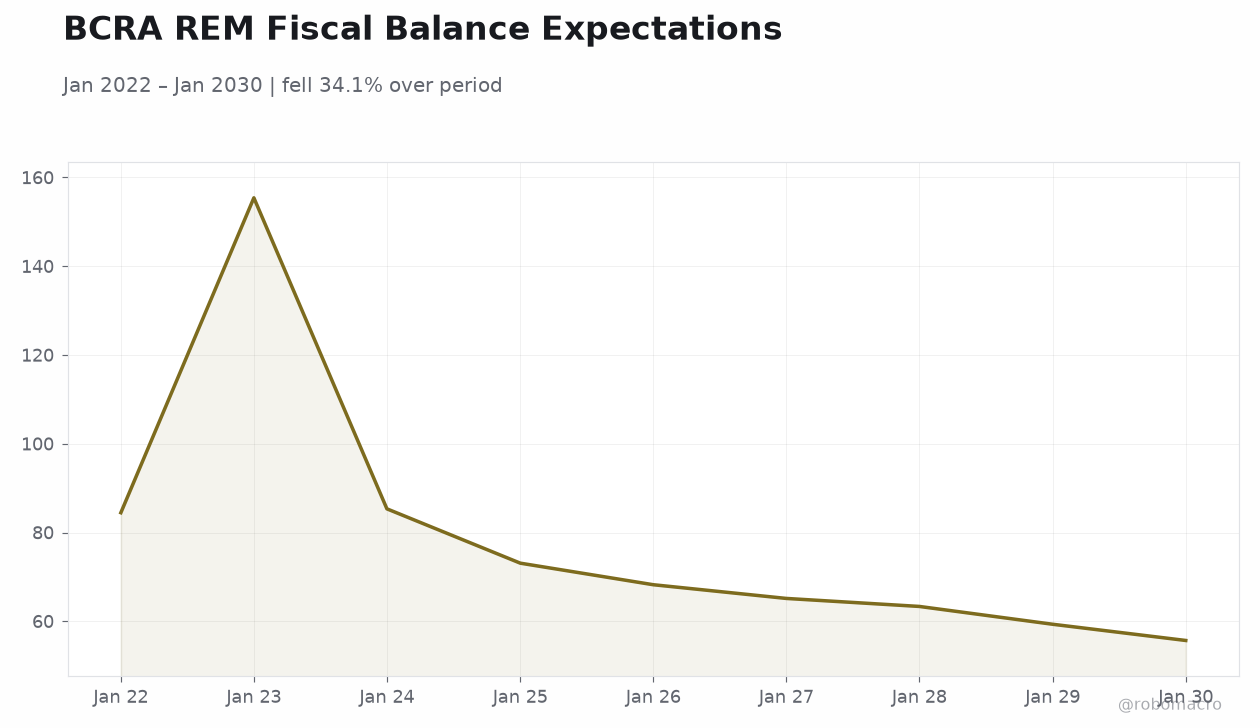
BCRA REM Fiscal Balance Expectations BCRA REM Fiscal Balance Expectations | Type: macro_line | BCRA REM Fiscal Balance Expectations: 55.67 (2030-01-01) | Range: 55.67–155.4 | Trend(5pt): 84.46,85.33,68.23,63.34,55.67
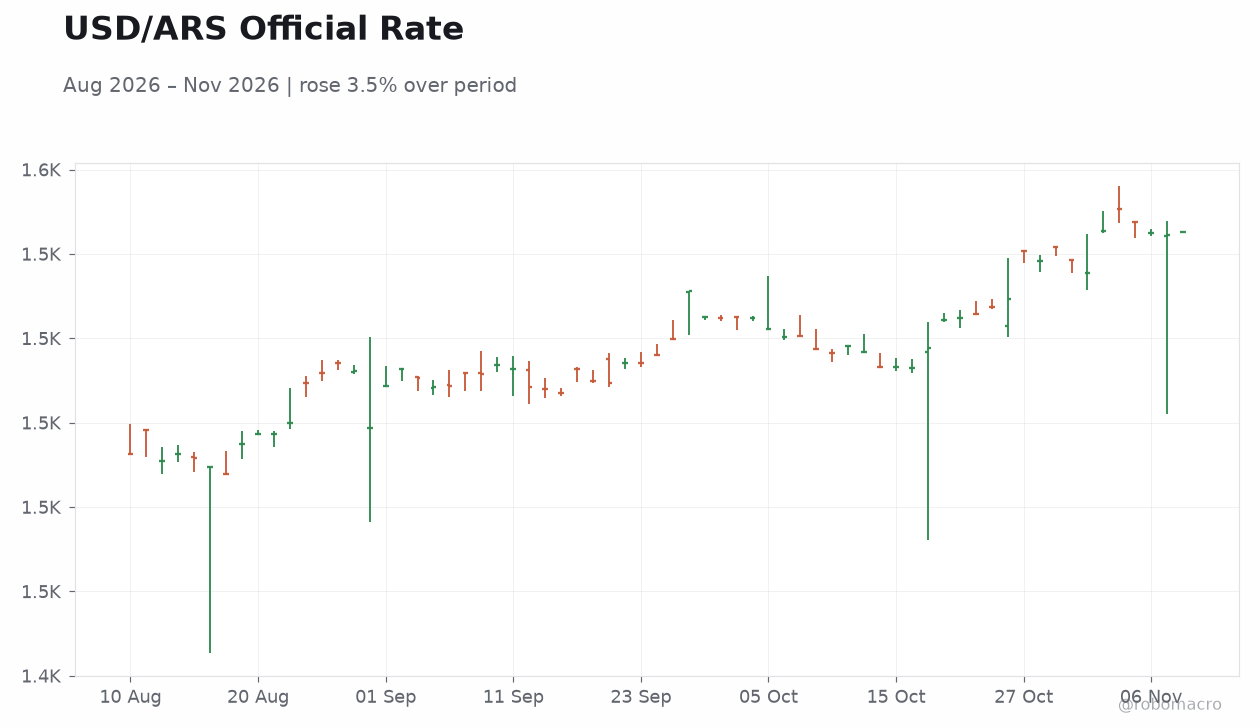
USD/ARS Official Rate USD/ARS Official Rate | Type: market_hloc | USD/ARS: 1545 (2026-11-10) | Range: 1488–1551 | Trend(6pt): 1493,1509,1514,1513,1545,1545

Other Economic Notes (continued)

Reserve accumulation through the soybean export complex remains the binding constraint on external sustainability, making the oilmeal demand shift toward Argentine supply strategically important. The Pope's intervention highlights a growing debate over the distributional costs of adjustment, which could temper the pace of further liberalization. India's oilmeal exports falling 28.5% as soymeal loses share to Brazil and Argentina is a reminder of how competitive pricing drives Argentine export volumes.

Global Macro News

Global markets are focused on the US inflation print, which is being framed as a key test for the dollar and, by extension, for peso stability. The Bank of England's Lombardelli is weighing a December rate hike amid a low-gear UK economy, while the Bank of Canada's recent hike has investors watching jobs and inflation data closely. Hungary's inflation accelerated for a third month even as its key rate held steady, a reminder that European disinflation is uneven.

Europe's largest pension manager, ABP, is ending its active equities strategy, signaling a shift toward passive allocation that could affect emerging-market equity flows. Brent's 2.35% decline reflects demand concerns, while gold eased 0.14% to 4,108.90 and Bitcoin fell 1.31% to 74,237.50, pointing to a mildly risk-off tone. For Argentina, a firmer dollar and higher US rates would tighten external conditions and complicate BCRA's reserve-building path.

Sponsored by Arbitrage Search
Page 2

Argentina Macro Daily(Beta Mode)

November 10, 2026 robomacro.com

Continuation

BCRA Watch

The Central Bank of Argentina has maintained its restrictive stance, holding the policy rate steady while allowing the crawling peg to anchor nominal FX expectations. Recent BCRA communications emphasize that disinflation toward the 33.4% CPI print remains the priority, with the monetary authority signaling no premature easing until inflation expectations converge. The Bank has leaned on reserve accumulation through the export complex and tight FX management to preserve credibility, and the flat official peso print at 1,545.25 is consistent with that controlled approach.

Forward guidance suggests the BCRA will keep real rates positive and use sterilization tools to manage liquidity as it rebuilds reserves. For markets, the implication is a continued carry-friendly environment for peso assets, but with limited room for aggressive rate cuts until fiscal and reserve metrics confirm durability. Any political noise from the Pope's critique is unlikely to shift BCRA's technocratic path, though it could affect the government's fiscal communication.

Sponsored by Arbitrage Search
Page 3