Brazil Macro Daily(Beta Mode)
Copom Minutes Spark Yield Rise
Market Snapshot
| Asset | Level | Change |
|---|---|---|
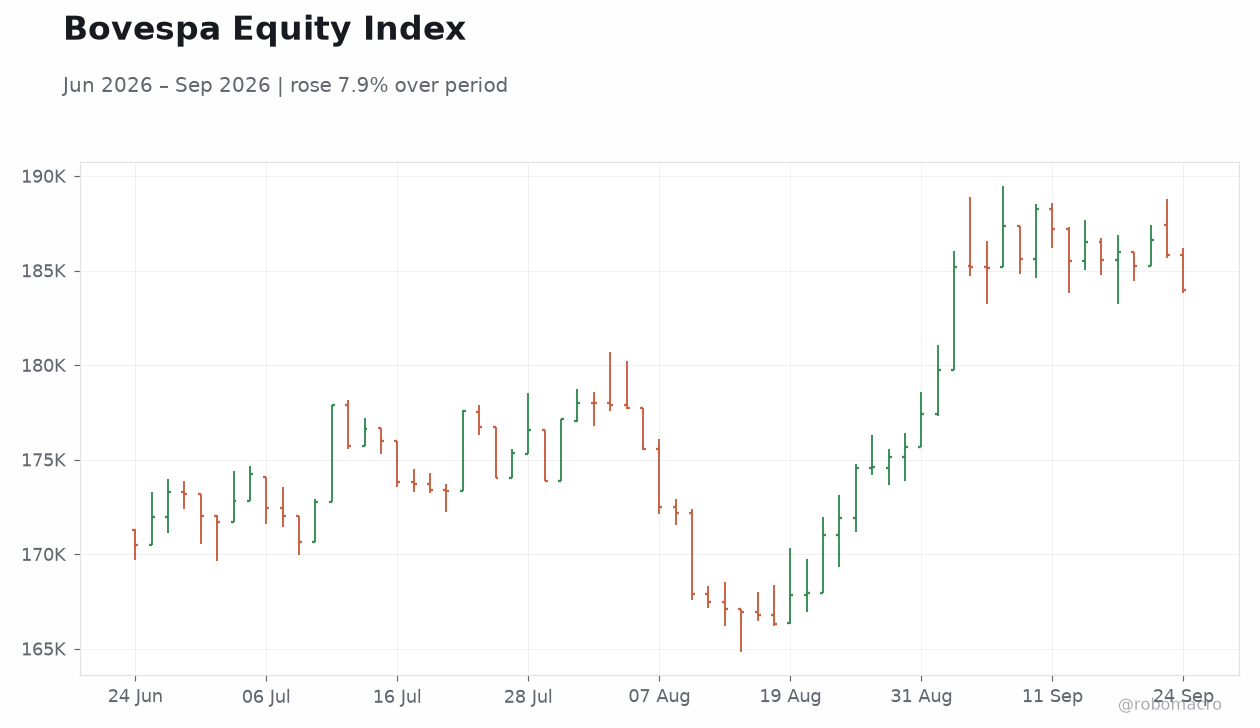
| Bovespa | 183,966.00 | -0.99% |
| USD/BRL | 5.19 | +0.48% |
| EUR/BRL | 5.91 | +0.66% |
| Vale | 13.56 | -1.88% |
| Petrobras | 20.84 | -1.42% |
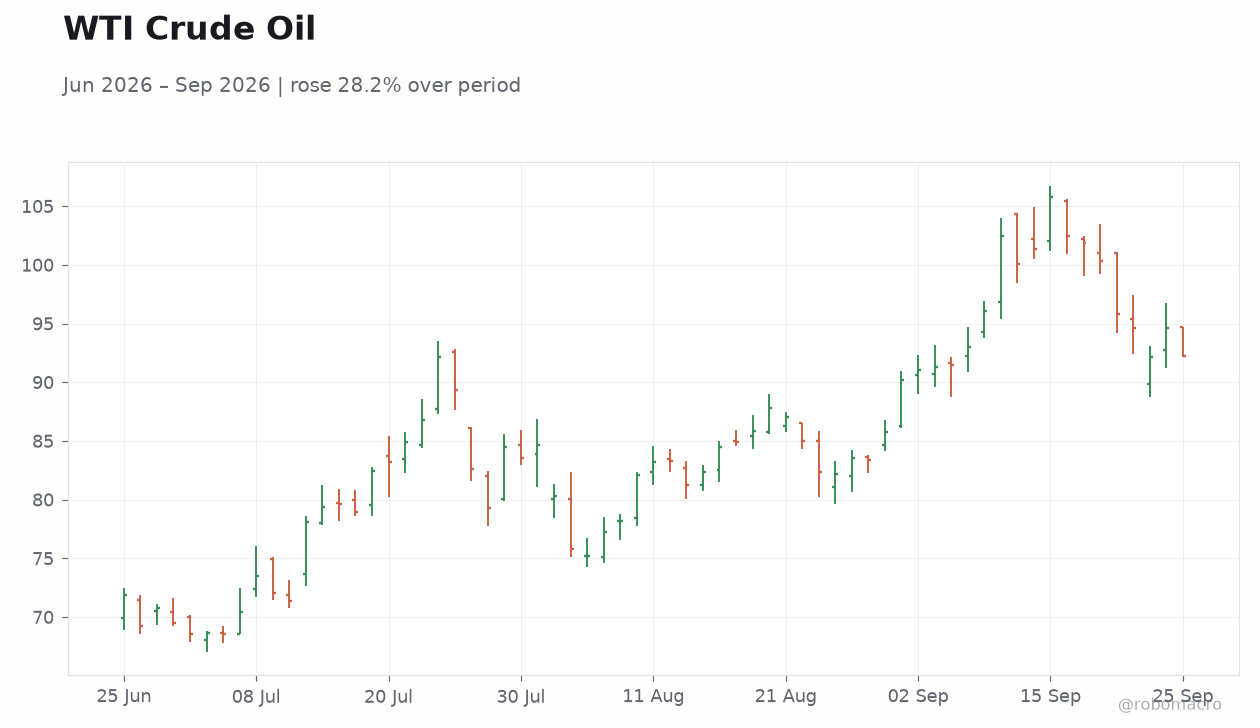
| WTI Crude | 92.28 | -2.46% |
| Gold | 4,332.30 | +0.80% |
| Bitcoin | 84,599.88 | +0.26% |
| Brazil 5Y Govt Yield | 14.11% | +3 bp |
| Brazil 10Y Govt Yield | 14.25% | +6 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BCB Copom Meeting Minutes | - | - | - |
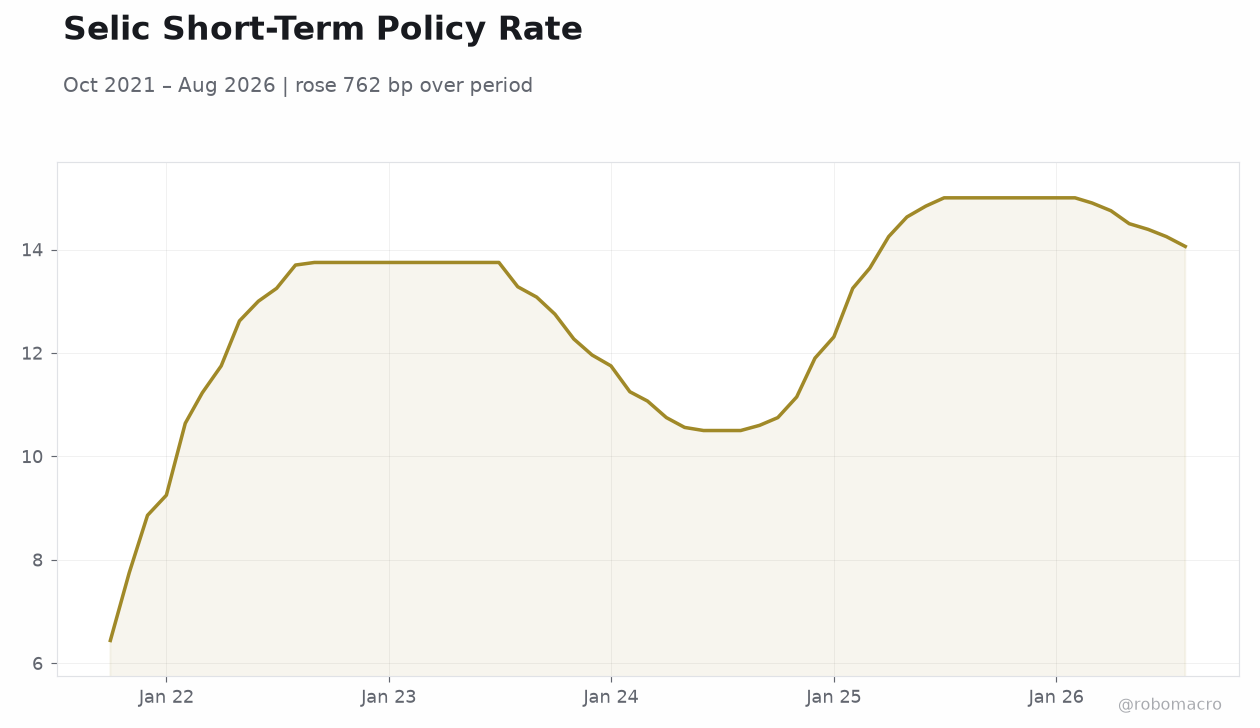 Selic Short-Term Policy Rate | Type: macro_line | Policy Rate %: 14.06 (2026-08-01) | Range: 6.44–15 | Trend(6pt): 6.44,13.75,11.25,14.25,14.39,14.06
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- BCB releases Copom minutes with no immediate policy shift
- Bovespa falls 0.99% while USD/BRL rises 0.48% to 5.19
- Brazil 10Y yield advances 6 bp to 14.25%
Yesterday's Recap
The BCB published Copom meeting minutes from 22 September, providing fresh detail on the committee’s assessment of inflation risks and the Selic path at the prevailing 13.75% rate. Markets reacted with modest pressure on fixed-income assets as the Brazil 5Y yield rose 3 bp to 14.11% and the 10Y yield increased 6 bp to 14.25%. Equities closed lower, with the Bovespa declining 0.99% to 183,966.00 amid broad selling in commodity names.
Vale dropped 1.88% to 13.56 and Petrobras fell 1.42% to 20.84 as WTI crude slid 2.46% to 92.28. The real weakened, with USD/BRL finishing at 5.19 and EUR/BRL at 5.91. Gold advanced 0.80% while Bitcoin edged 0.26% higher, reflecting limited safe-haven flows into Brazilian assets.
The Day Ahead
No scheduled economic releases or BCB speeches appear on the calendar for 25 September. Attention will therefore turn to any follow-up commentary from Copom members on the minutes and to external drivers such as commodity prices. Market participants will also monitor developments in the October presidential campaign and potential US policy signals that could affect capital flows.
With the Selic rate steady at 13.75%, investors will look for any hints on the timing of future easing once inflation prints stabilise near the 4.22% YoY level recorded in August.
Other Economic Notes
El Niño conditions are projected to add 0.5 percentage points to Brazilian inflation in 2027, raising the hurdle for the BCB’s convergence to target. Chainalysis data show Brazil leading global crypto adoption even during the recent bear market, underscoring the resilience of alternative payment channels. Chinese buyers have sharply reduced soybean imports from Brazil ahead of the Trump-Xi summit, tightening crushing margins and raising the risk of a global supply squeeze.
Petrobras has signalled willingness to reach consensus with Braskem creditors but has ruled out a unilateral capital injection, leaving the restructuring path dependent on other shareholders.
Global Macro News
Democratic US lawmakers accused the Trump administration of interfering in Brazil’s October election, prompting a sharp response from President Lula who claimed Washington seeks to “colonise” Brazilian resources. ↓ p.2