Brazil Macro Daily(Beta Mode)
Bovespa Slips Ahead of Unemployment Print
Market Snapshot
| Asset | Level | Change |
|---|---|---|
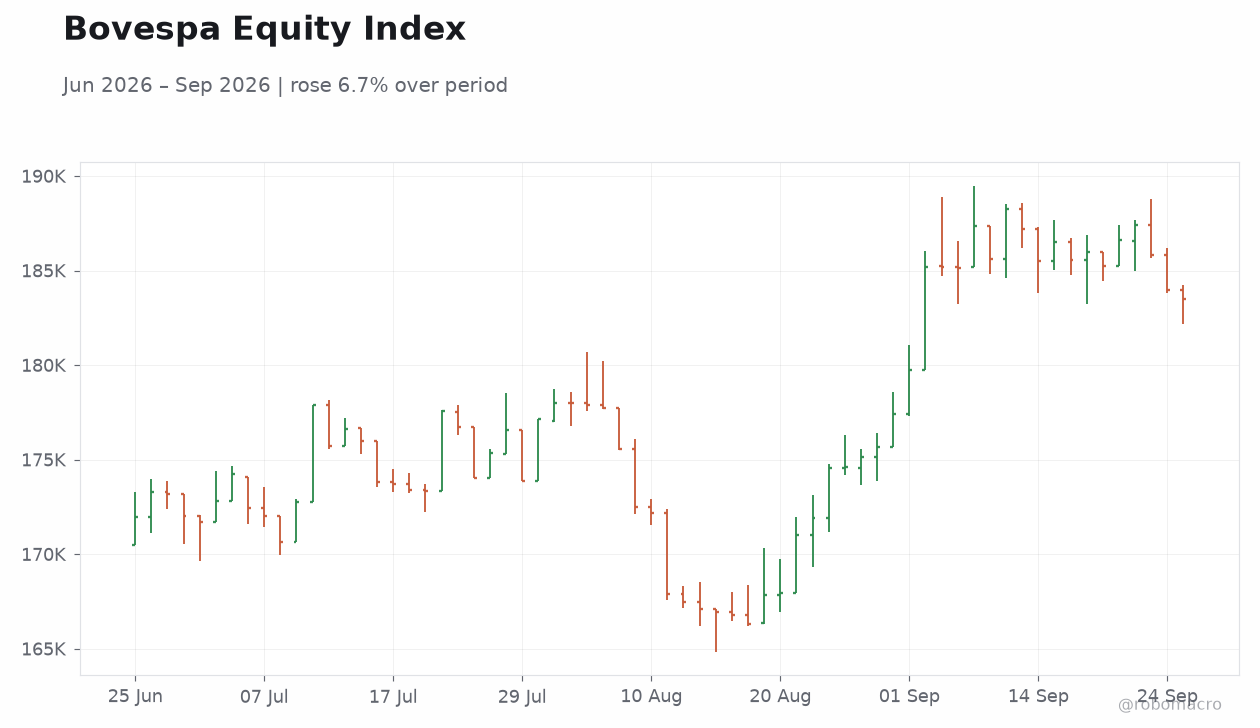
| Bovespa | 183,477.00 | -0.27% |
| USD/BRL | 5.18 | -0.12% |
| EUR/BRL | 5.90 | -0.01% |
| Vale | 13.61 | +0.37% |
| Petrobras | 20.37 | -2.26% |
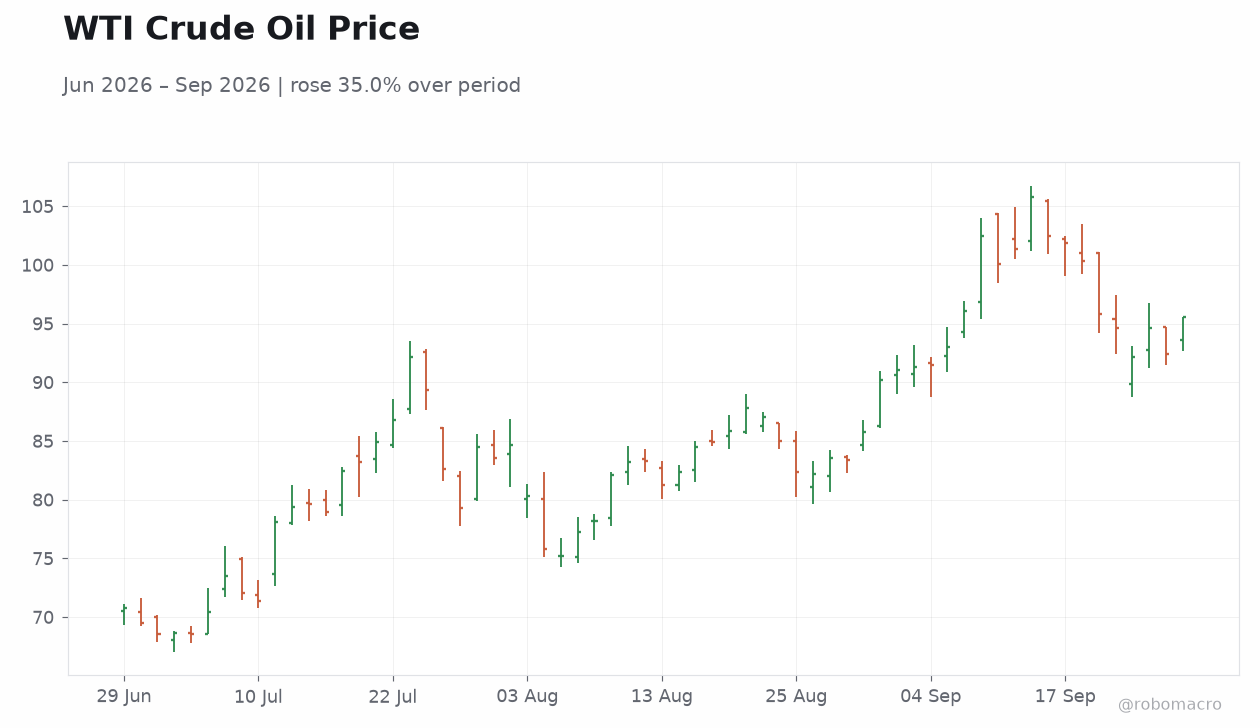
| WTI Crude | 95.45 | +3.29% |
| Gold | 4,178.40 | -3.30% |
| Bitcoin | 82,724.08 | -2.05% |
| Brazil 5Y Govt Yield | 14.09% | +1 bp |
| Brazil 10Y Govt Yield | 14.11% | -5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
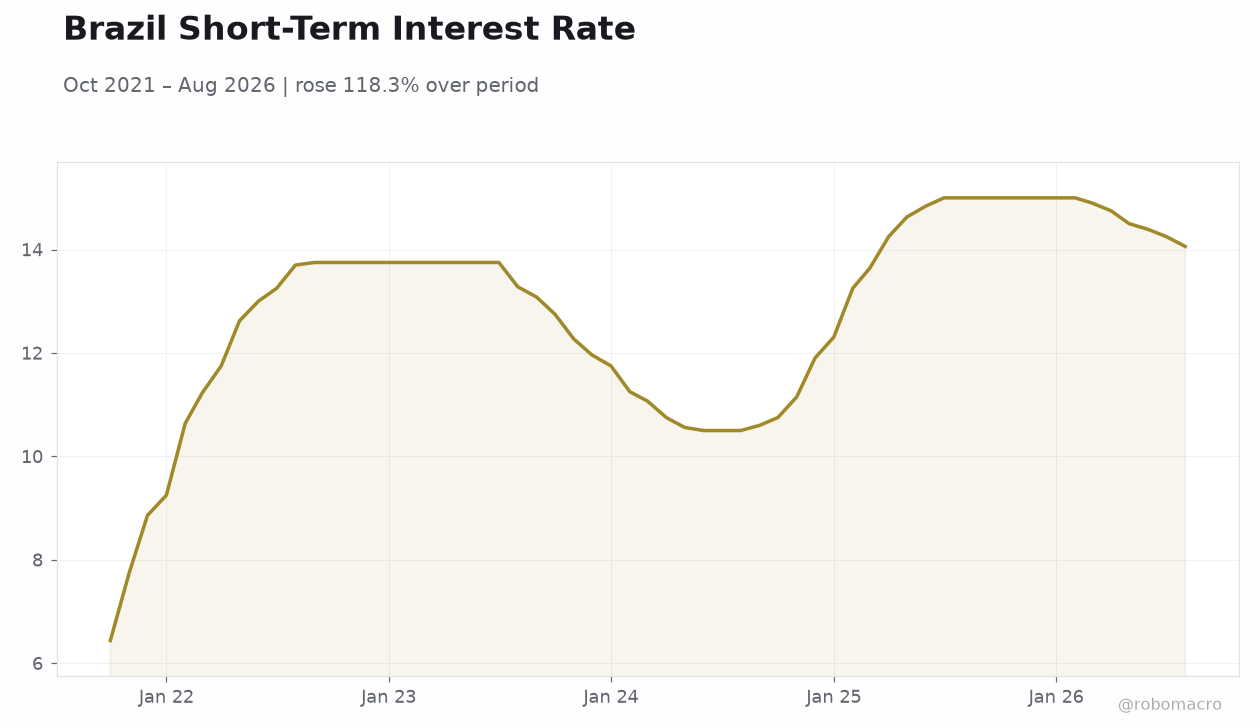 Brazil Short-Term Interest Rate | Type: macro_line | Policy Rate %: 14.06 (2026-08-01) | Range: 6.44–15 | Trend(6pt): 6.44,13.75,11.25,14.25,14.39,14.06
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Tuesday (2026-09-29) | |||
| Headline Unemployment Rate | 5.30 | - | 04:00 |
| Friday (2026-10-02) | |||
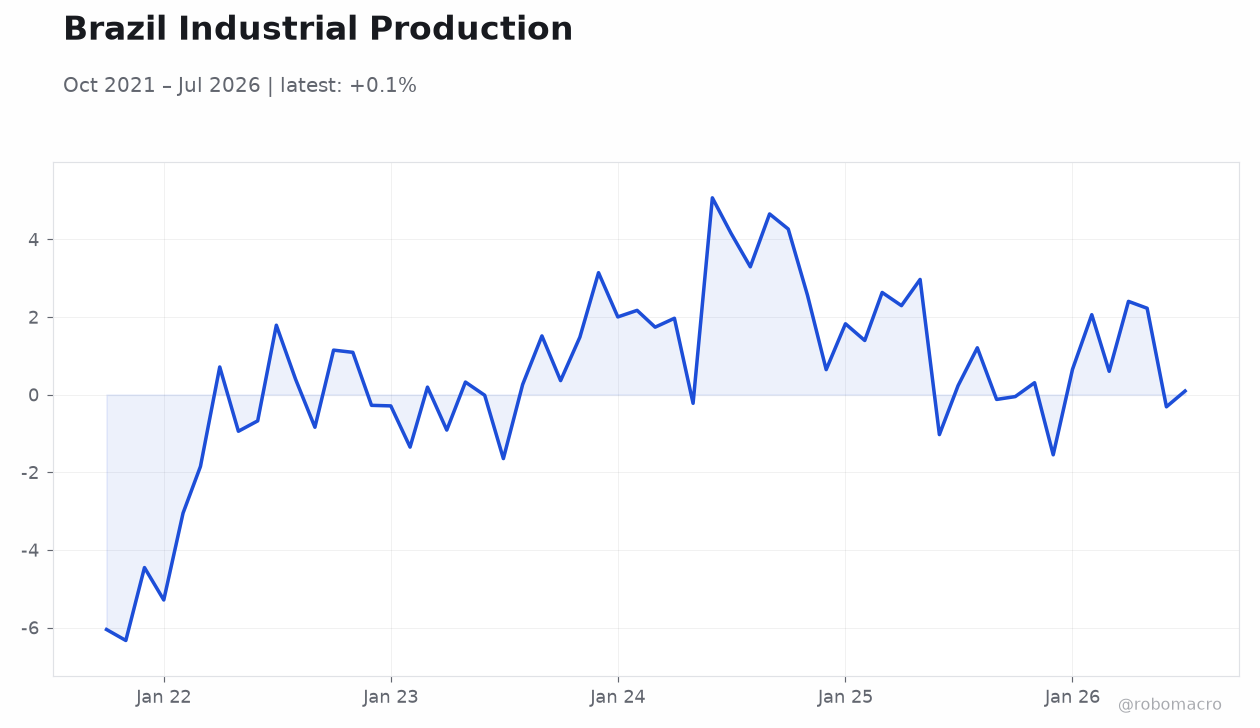
| Industrial Production Month-over-Month | 0.20 | - | 04:00 |
- Bovespa fell 0.27% to 183,477 while USD/BRL eased 0.12% to 5.18 amid mixed commodity moves.
- Headline unemployment rate due tomorrow offers first labour-market signal since last COPOM meeting.
- Selic held at 13.75% with CPI at 4.22% YoY; 10-year yield eased 5 bp to 14.11%.
Yesterday's Recap
Brazilian equities closed lower on September 27 as Bovespa declined 0.27% to 183,477.00. USD/BRL finished at 5.18 after a 0.12% drop while EUR/BRL slipped 0.01% to 5.90. Vale advanced 0.37% to 13.61 but Petrobras dropped 2.26% to 20.37.
WTI crude rose 3.29% to 95.45, supporting commodity exporters, whereas gold fell 3.30% to 4,178.40 and Bitcoin declined 2.05% to 82,724.08. The Brazil 5-year government yield rose 1 bp to 14.09% while the 10-year yield eased 5 bp to 14.11%. No economic data were released and no BCB officials spoke publicly.
Brazil’s Development Bank announced an applied research centre for sustainable development. Recent analysis linked lower inequality more closely to poverty reduction. Cost-of-living pressures weighed on households ahead of the October vote.
President Lula banned fixed-odds sports betting, calling the sector a cancer. Electric-vehicle registrations in Latin America passed one million, with Brazil holding half the fleet.
The Day Ahead
The headline unemployment rate for August prints at 04:00 ET on September 29 with the prior reading at 5.3%. Markets will scrutinise any shift in labour-market slack for clues on wage pressures ahead of the next COPOM decision. Industrial production month-over-month follows on October 2.
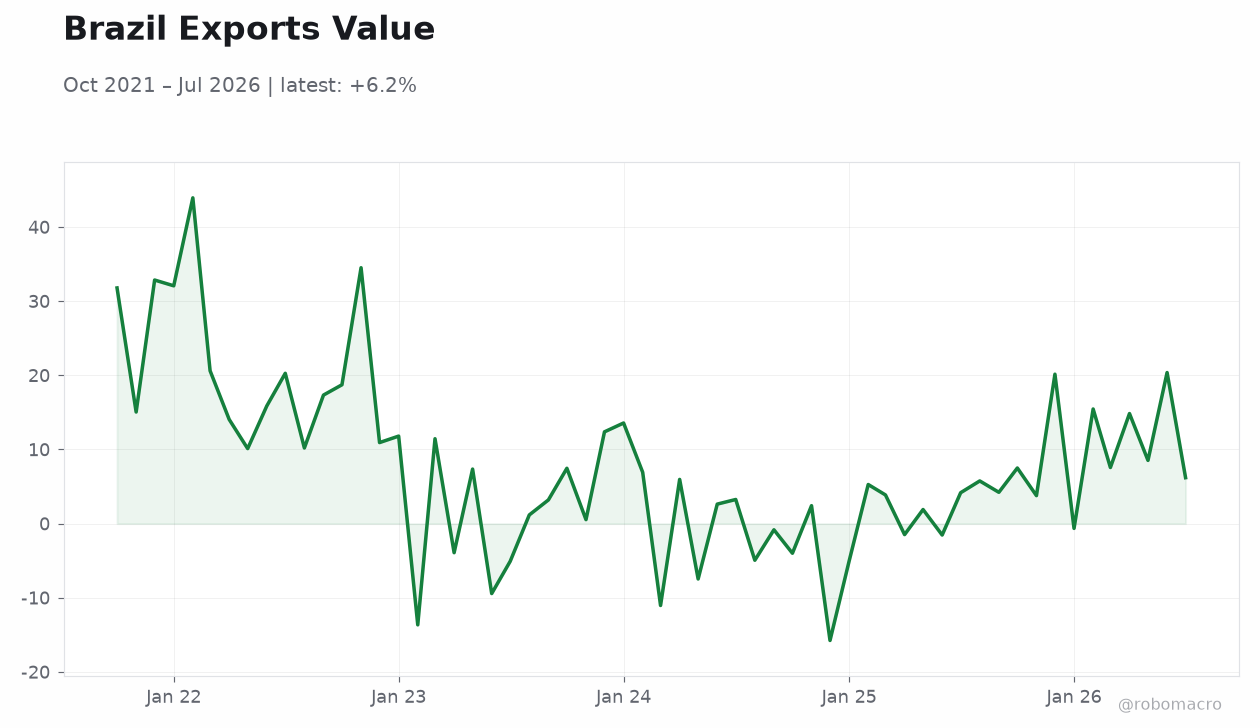
No other Brazil-specific releases or BCB speeches are scheduled in the immediate window. Participants will also monitor global oil and iron-ore prices given their direct impact on fiscal and trade balances.
Other Economic Notes
Brazil’s Development Bank launched an applied research centre focused on sustainable development projects. Recent analysis shows falling inequality has contributed more than previously estimated to the decline in poverty rates. Persistent cost-of-living pressures continue to weigh on household sentiment ahead of the October presidential vote.
President Lula’s ban on fixed-odds sports betting removes a source of household financial leakage and is expected to draw broad public support. Electric-vehicle registrations in Latin America have passed one million units, with Brazil accounting for half the regional total.