Brazil Macro Daily(Beta Mode)
BRL Weakens Ahead of Unemployment Print
Market Snapshot
| Asset | Level | Change |
|---|---|---|
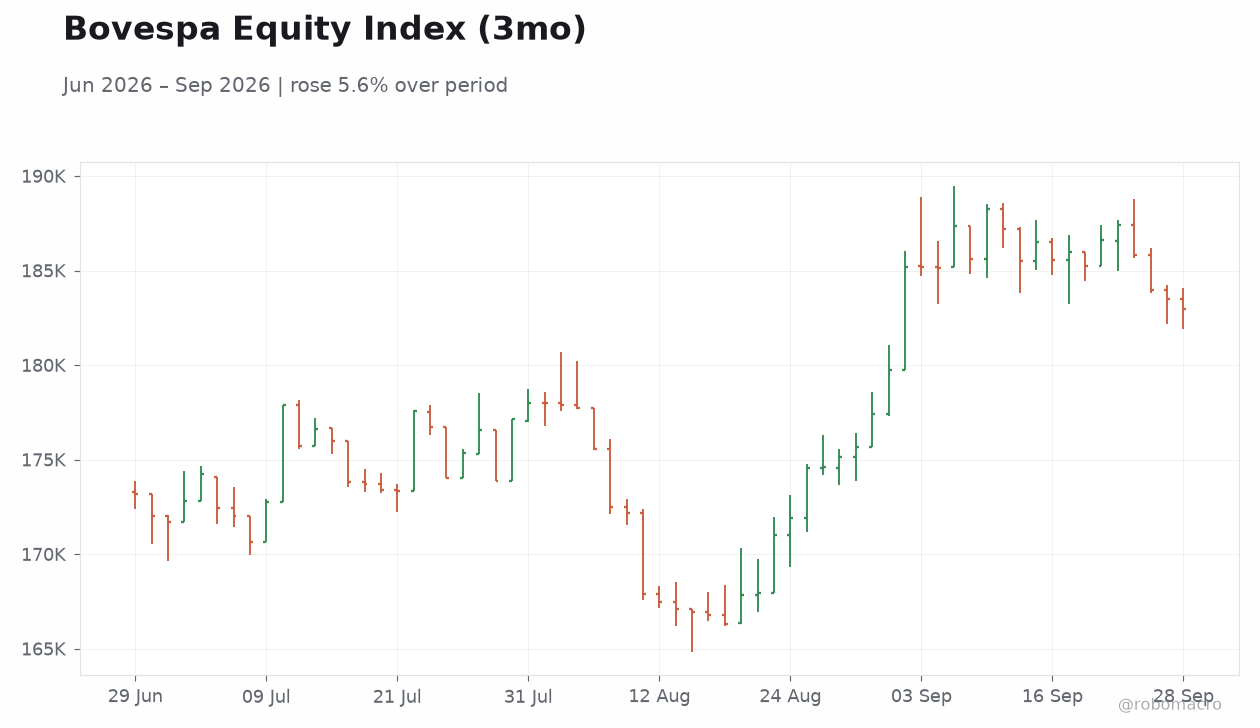
| Bovespa | 182,991.00 | -0.26% |
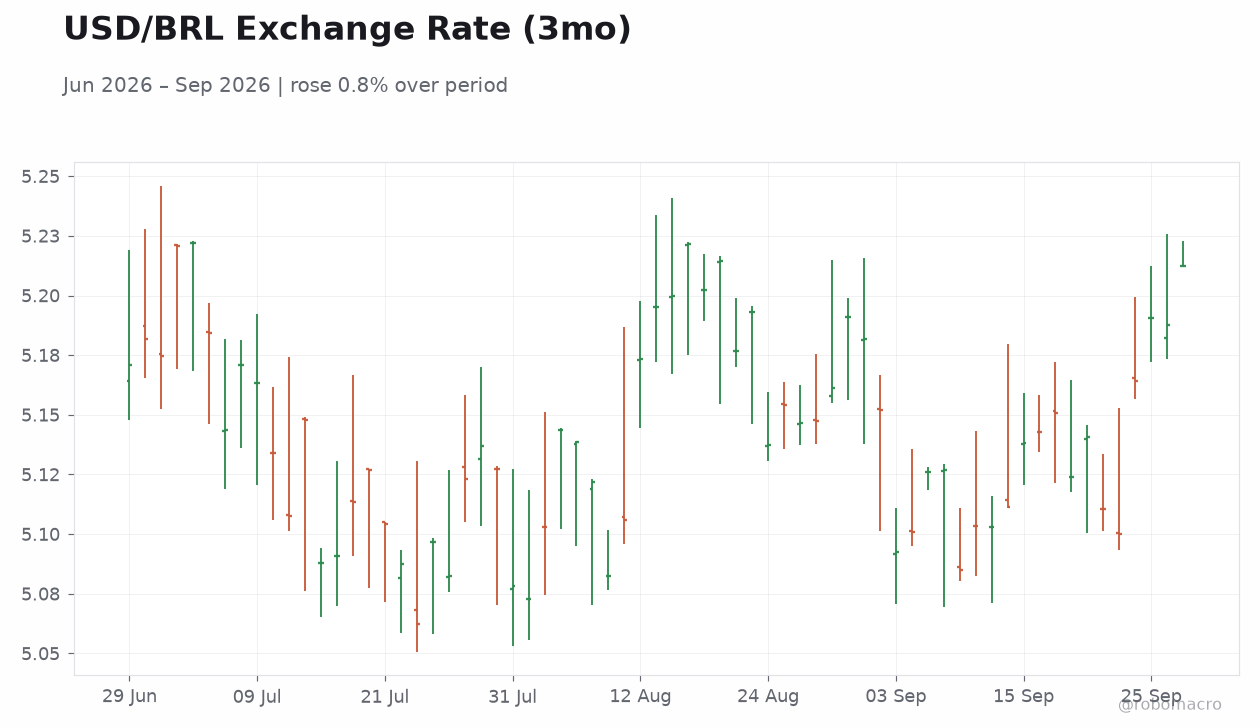
| USD/BRL | 5.21 | +0.48% |
| EUR/BRL | 5.93 | +0.52% |
| Vale | 13.59 | -0.15% |
| Petrobras | 20.65 | +1.37% |
| WTI Crude | 92.74 | +0.15% |
| Gold | 4,172.00 | +0.09% |
| Bitcoin | 83,792.73 | +0.35% |
| Brazil 5Y Govt Yield | 14.09% | +1 bp |
| Brazil 10Y Govt Yield | 14.11% | -5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
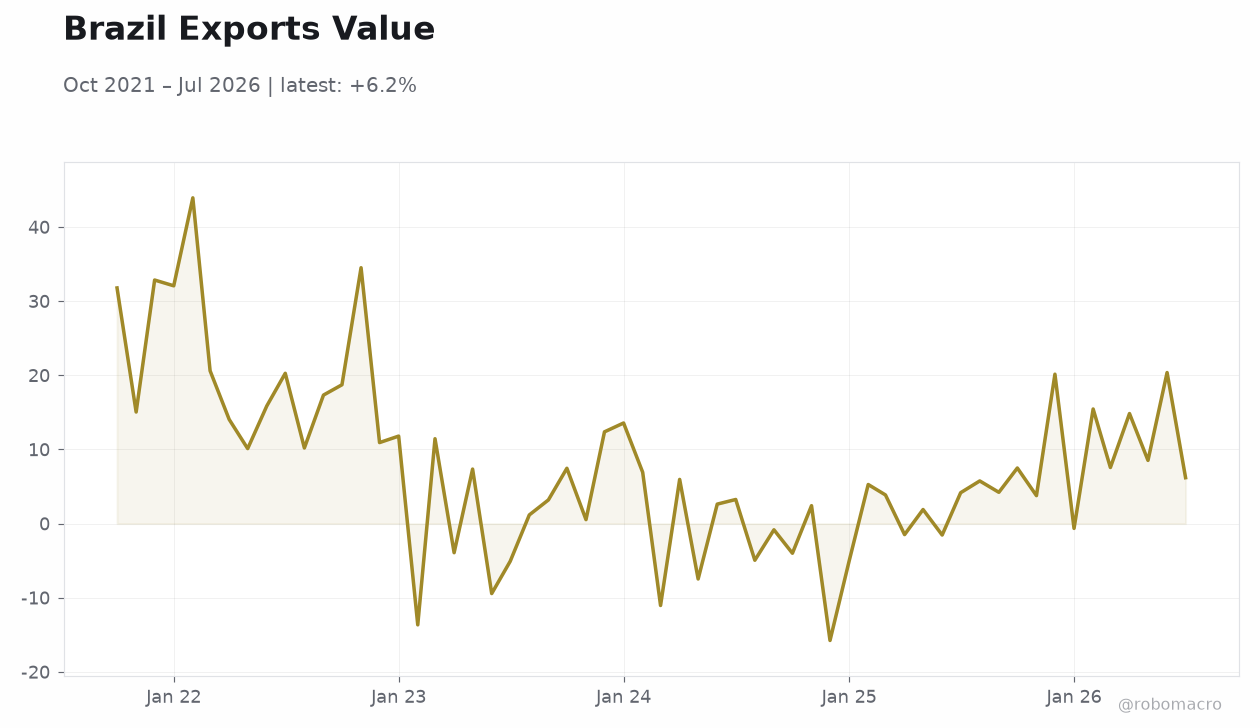 Brazil Exports Value | Type: macro_line | Exports (USD mn): 6.195 (2026-07-01) | Range: -15.76–43.94 | Trend(6pt): 31.79,10.93,6.929,-1.479,20.38,6.195
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Headline Unemployment Rate | 5.30 | - | 04:00 |
| Friday (2026-10-02) | |||
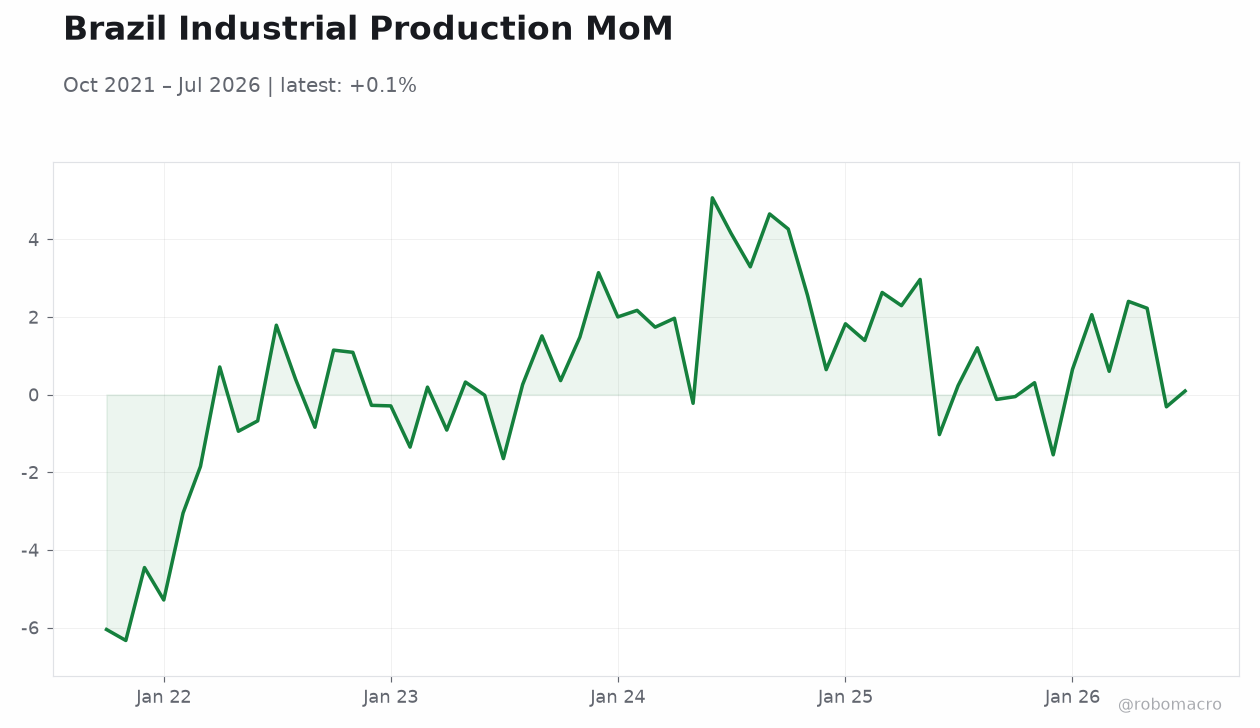
| Industrial Production Month-over-Month | 0.20 | - | 04:00 |
- Bovespa fell 0.26% to 182,991 while USD/BRL rose 0.48% to 5.21 on thin volumes.
- Headline Unemployment Rate due today with medium impact; prior print 5.3%.
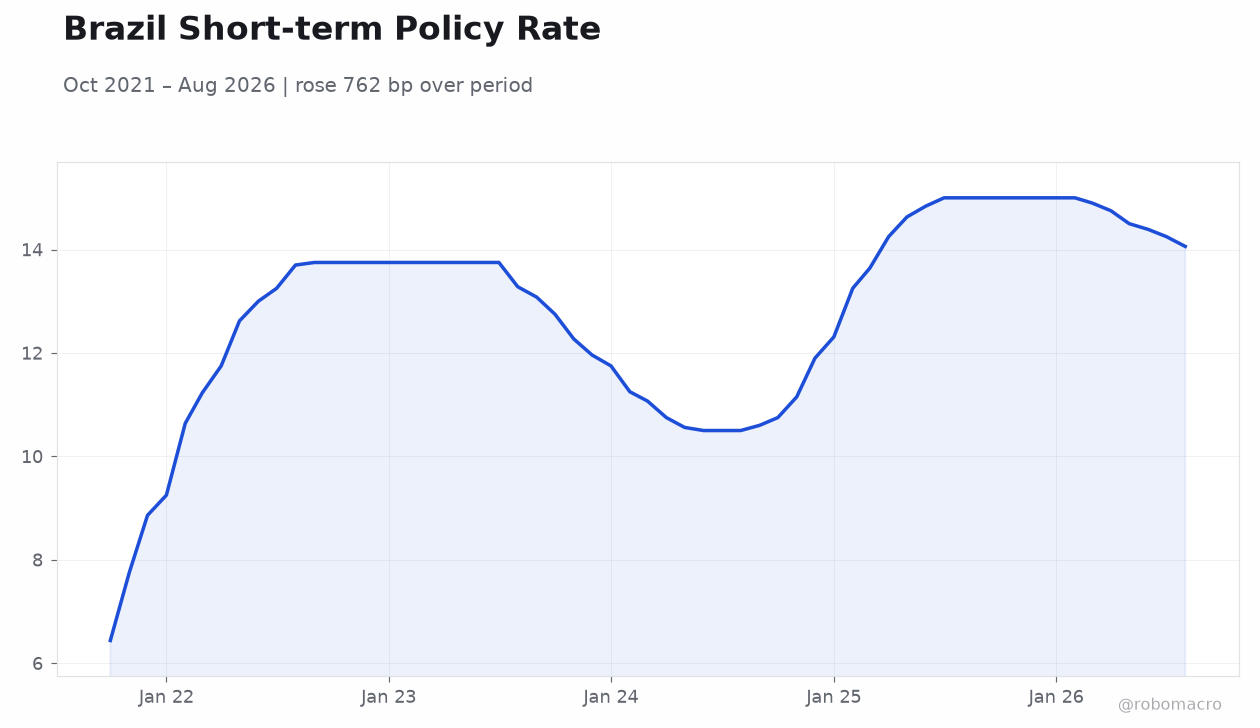
- Selic held at 13.75% with CPI at 4.22% YoY; 10-year yield eased 5 bp to 14.11%.
Yesterday's Recap
Brazilian markets closed modestly weaker on 28 September with no domestic data releases to drive price action. Bovespa declined 0.26% to 182,991 while Petrobras gained 1.37% to 20.65 and Vale slipped 0.15% to 13.59. USD/BRL climbed 0.48% to 5.21 and EUR/BRL advanced 0.52% to 5.93, reflecting broad dollar strength.
The Brazil 5-year yield rose 1 bp to 14.09% while the 10-year yield fell 5 bp to 14.11%. WTI crude edged 0.15% higher to 92.74 and gold added 0.09% to 4,172. No COPOM speeches or fiscal updates emerged to shift policy expectations.
Equity and FX moves remained contained ahead of the unemployment release.
The Day Ahead
The Headline Unemployment Rate prints at 04:00 ET today and carries medium market impact. Markets will scrutinise any shift in labour-market slack for clues on consumer resilience and wage pressures. Friday brings Industrial Production MoM, last reported at 0.2%.
Traders will also monitor global commodity prices for iron-ore and oil export signals. No BCB or fiscal events are scheduled. Positioning is expected to stay light until the labour data clarifies near-term growth momentum.
Other Economic Notes
IEDI stressed that investment must replace consumption as the primary GDP driver to sustain expansion. Brazil is weighing a potential data-centre boom against rising electricity-cost pressures that could strain the grid. MBRF Global Foods is sounding out investors for a possible junk-bond issue to refinance debt.
Nubank has opened preliminary talks to acquire UK challenger bank Monzo. The online-gambling ban has already prompted Entain to cut its full-year revenue outlook to 4-6%.
Global Macro News
Japan’s policy-rate hike to the highest level in 31 years has kept the yen weak, supporting carry-trade flows that can influence BRL volatility. UK rate-hike bets have lifted sterling, adding to broad dollar pressure that weighed on emerging-market currencies including the real. ↓ p.2