Brazil Macro Daily(Beta Mode)
Bovespa Climbs as Yields Ease on Jobs Data
Market Snapshot
| Asset | Level | Change |
|---|---|---|
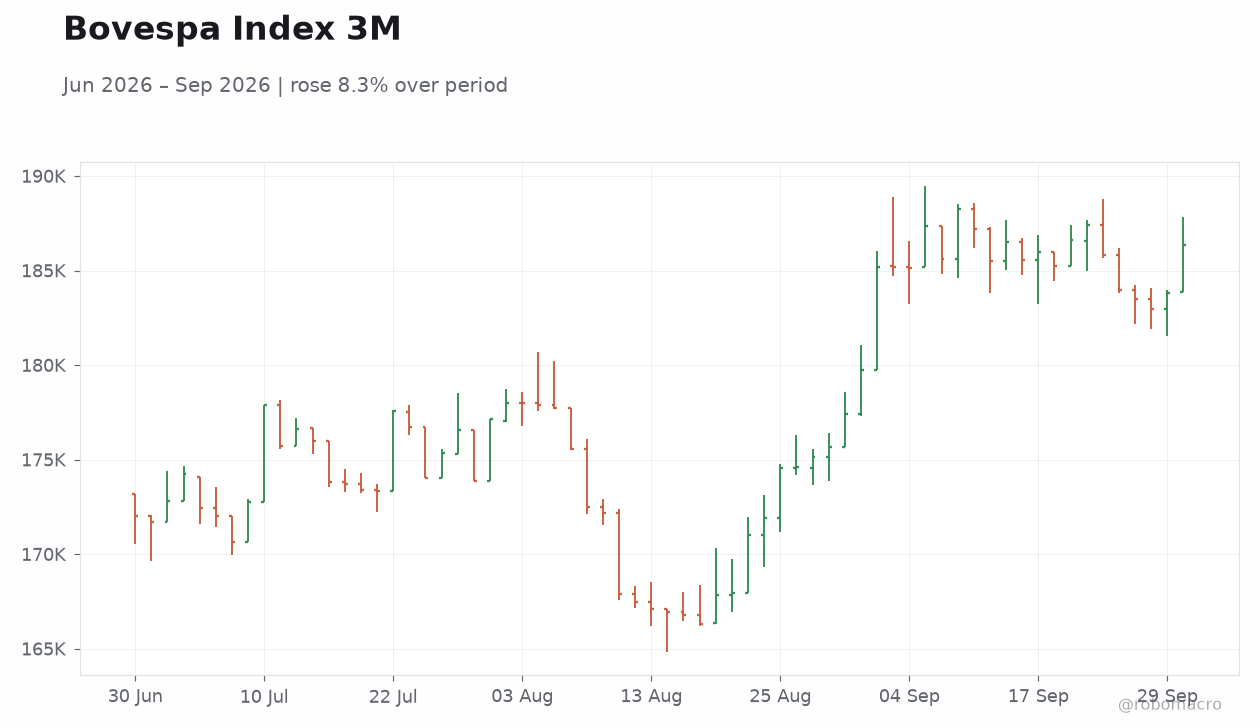
| Bovespa | 186,340.00 | +1.37% |
| USD/BRL | 5.16 | -0.78% |
| EUR/BRL | 5.83 | -1.06% |
| Vale | 13.41 | +0.83% |
| Petrobras | 20.87 | +1.07% |
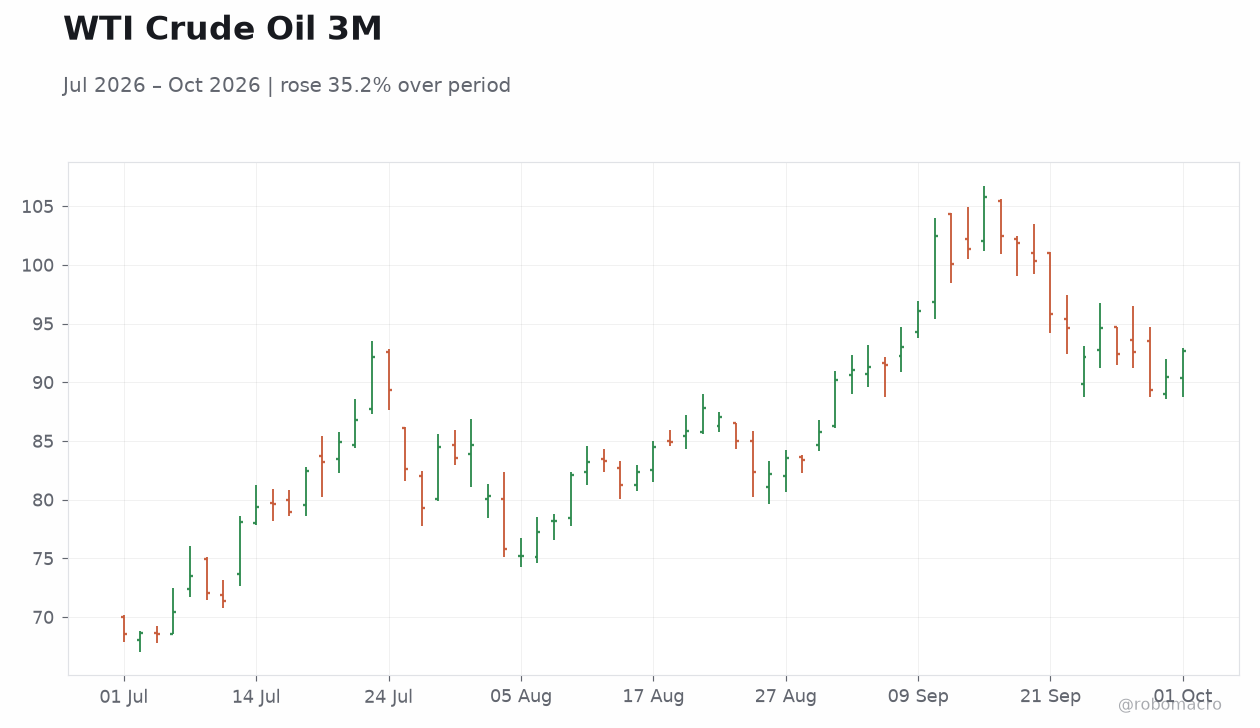
| WTI Crude | 92.80 | +2.63% |
| Gold | 4,181.30 | -0.13% |
| Bitcoin | 83,560.21 | +0.01% |
| Brazil 5Y Govt Yield | 14.06% | -5 bp |
| Brazil 10Y Govt Yield | 14.02% | -10 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Headline Unemployment Rate | 5.30 | 5.30 | 5.30 |
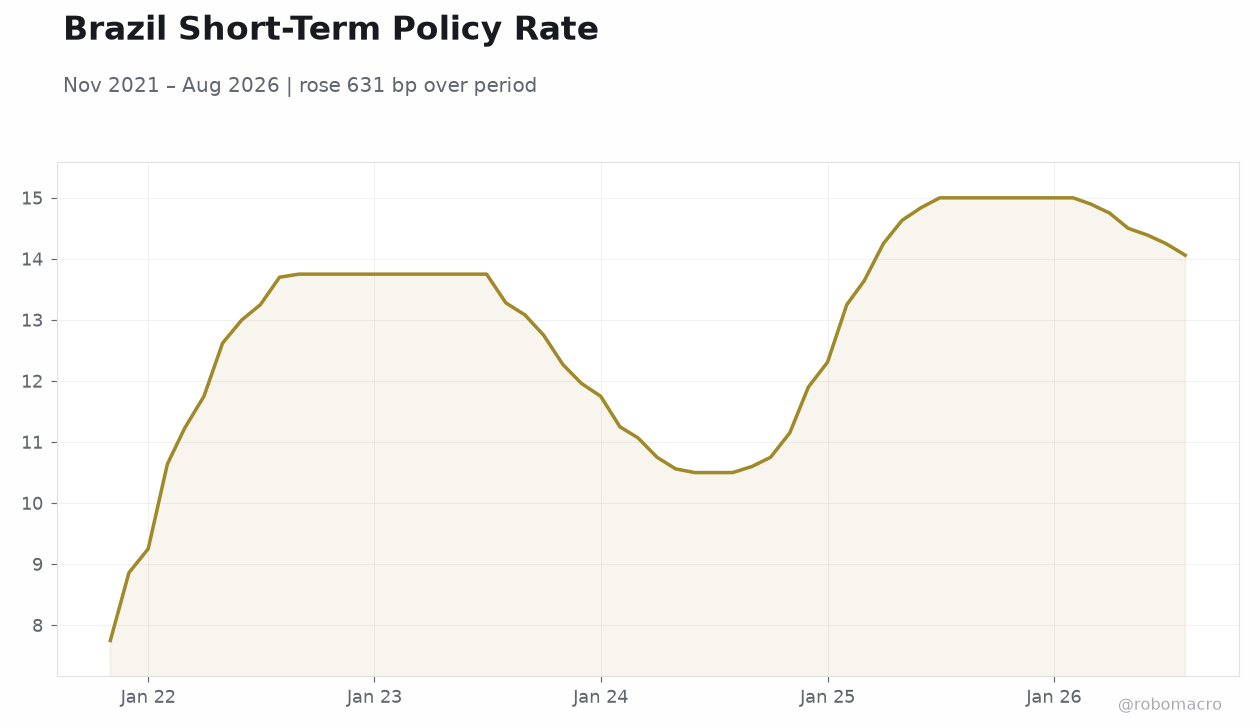 Brazil Short-Term Policy Rate | Type: macro_line | Policy Rate %: 14.06 (2026-08-01) | Range: 7.75–15 | Trend(6pt): 7.75,13.75,11.07,14.63,14.25,14.06
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Friday (2026-10-02) | |||
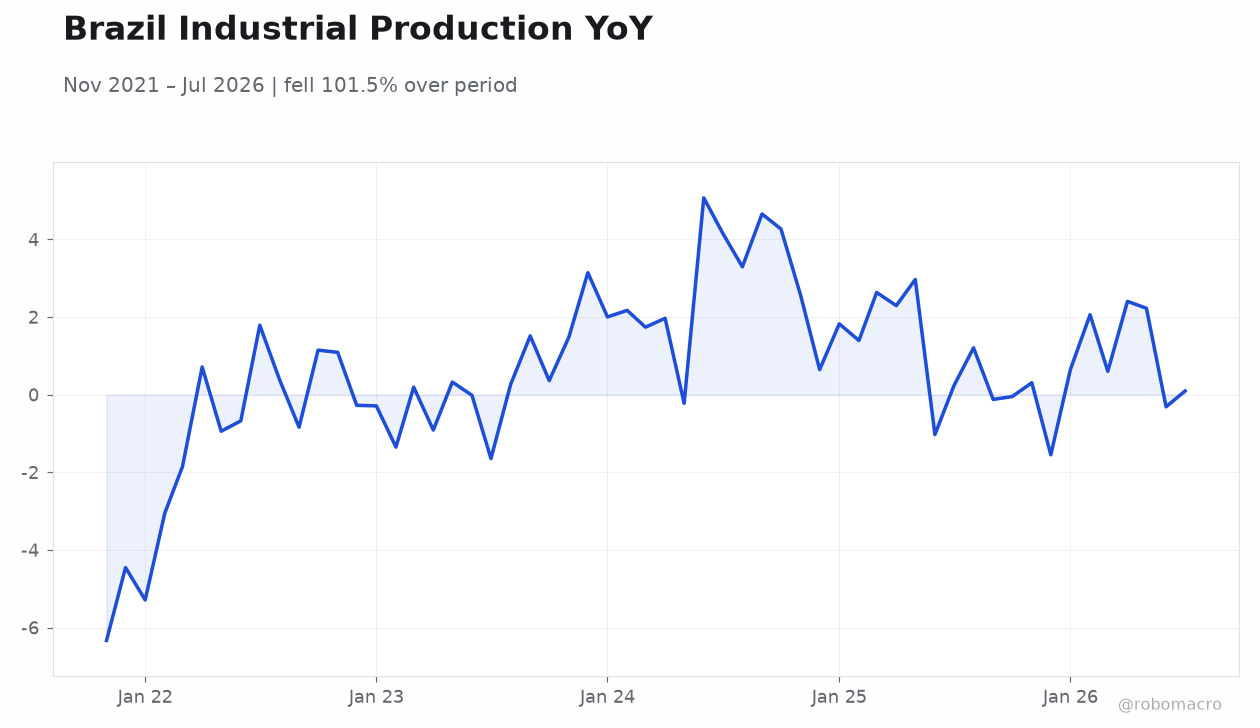
| Industrial Production Month-over-Month | 0.20 | 0.10 | 04:00 |
- Unemployment rate held at 5.3% in line with consensus.
- Bovespa rose 1.37% while USD/BRL fell 0.78% to 5.16.
- Brazil 10Y yield eased 10 bp to 14.02% as 5Y yield fell 5 bp.
Yesterday's Recap
Brazil's headline unemployment rate printed unchanged at 5.3% on September 29, matching both consensus and the prior reading and signaling steady labor-market conditions. Equity markets responded positively, with the Bovespa index closing at 186,340.00 for a 1.37% gain. The real strengthened, sending USD/BRL to 5.16 (-0.78%) and EUR/BRL to 5.83 (-1.06%).
Benchmark yields compressed, with the 5-year government yield declining 5 bp to 14.06% and the 10-year yield falling 10 bp to 14.02%. Commodity-exposed names supported the equity advance, as Vale rose 0.83% and Petrobras gained 1.07%. WTI crude climbed 2.63% to 92.80, providing an additional tailwind for Brazilian energy exporters.
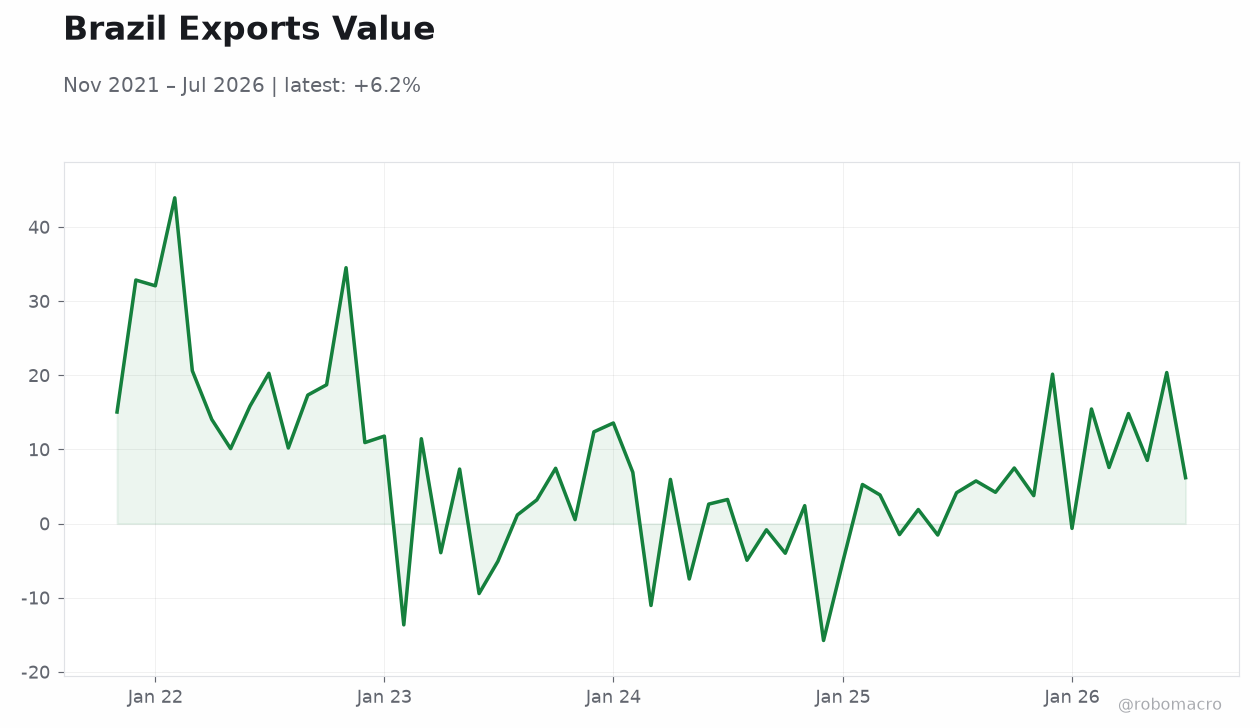
Election-related headlines and a new 55% China tariff on Brazilian beef after quota exhaustion also shaped sentiment.
The Day Ahead
No Brazilian economic releases are scheduled for October 1. Attention turns to the October 2 Industrial Production MoM print, which carries a consensus forecast of +0.1% against a prior reading of +0.2%. The data will offer the first monthly gauge of manufacturing momentum after the September labor-market release.
Markets will also monitor campaign developments ahead of the October 4 presidential vote between incumbent Luiz Inácio Lula da Silva and Flávio Bolsonaro. Any fresh polling surprises could influence currency and yield volatility. Financing news, including EMGA's EUR 100 million facility for BTG Pactual, may provide secondary support for local credit markets.
Other Economic Notes
Brazil beef exports now face a 55% tariff from China after the annual quota was exhausted, pressuring an important export revenue stream. EMGA arranged a EUR 100 million financing line for BTG Pactual from COFIDES, underscoring continued external funding access for Brazilian financial institutions. The October 4 presidential election remains the dominant domestic event, with security concerns prompting one independent outlet to suspend election coverage.
Fiscal sustainability and commodity export performance will stay in focus as the new administration takes shape.