Brazil Macro Daily(Beta Mode)
Flávio Bolsonaro Leads Lula, Bovespa Surges
Market Snapshot
| Asset | Level | Change |
|---|---|---|
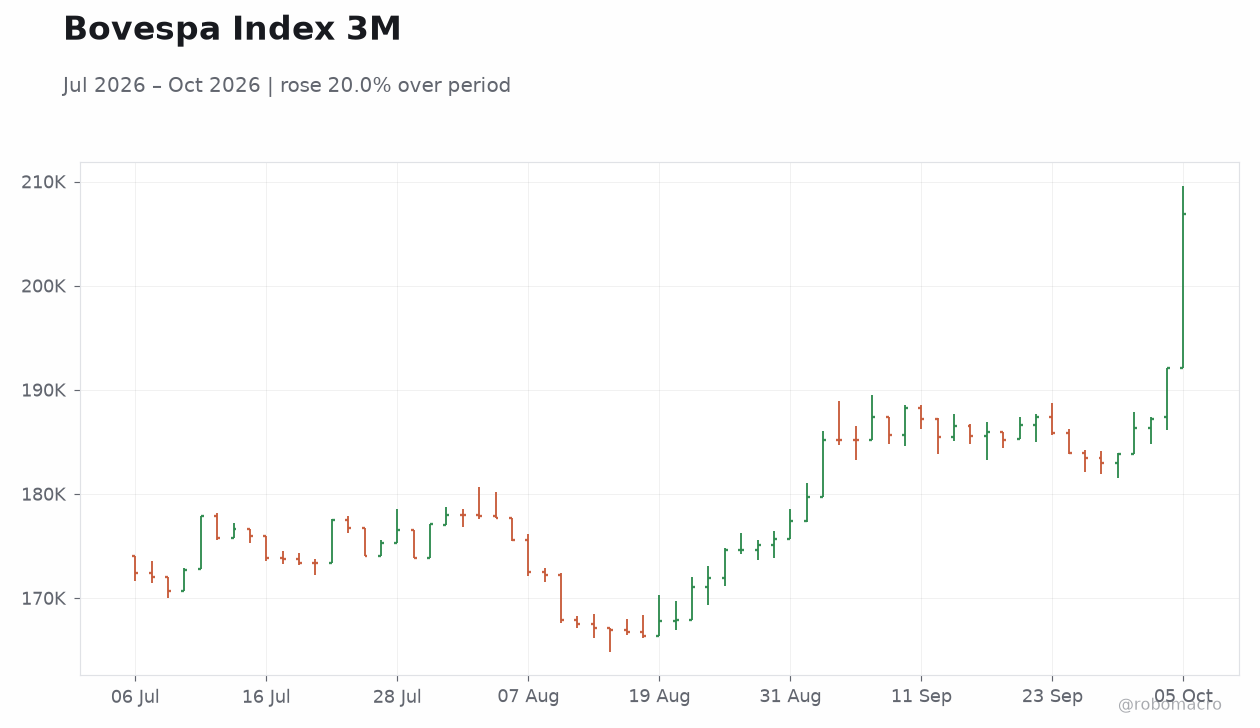
| Bovespa | 206,912.00 | +7.70% |
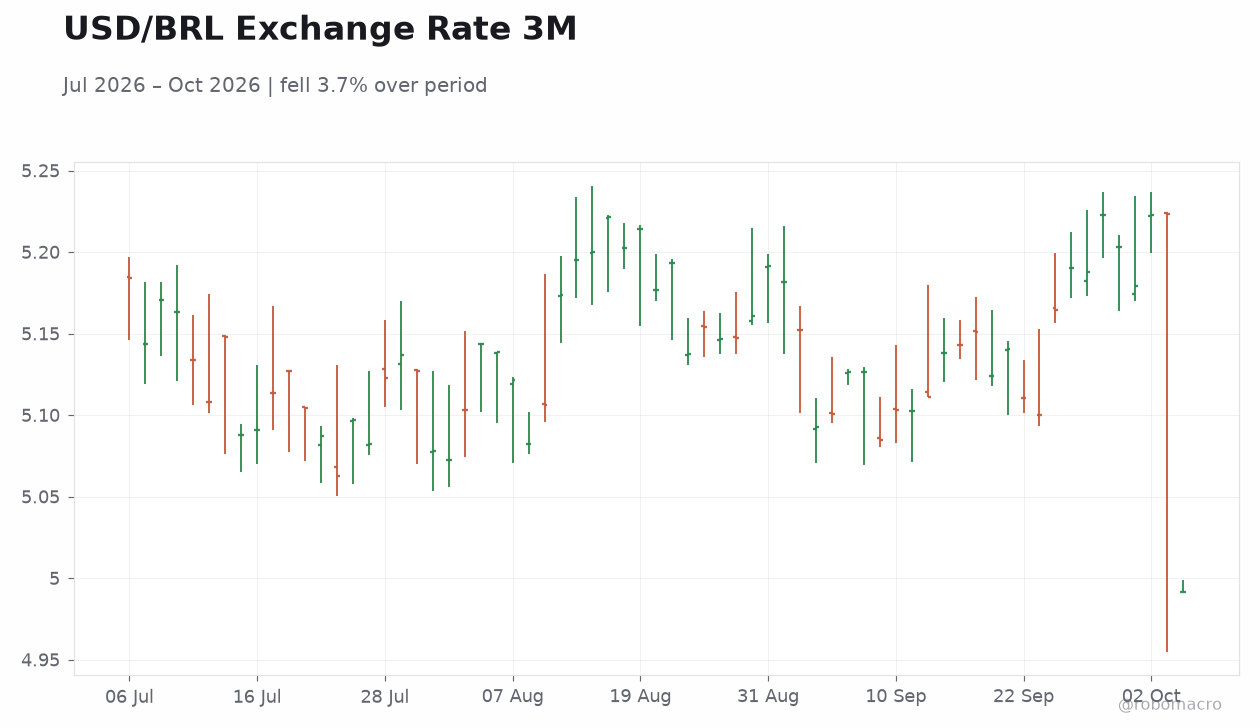
| USD/BRL | 4.99 | -4.43% |
| EUR/BRL | 5.62 | -4.33% |
| Vale | 14.15 | +2.83% |
| Petrobras | 24.14 | +11.50% |
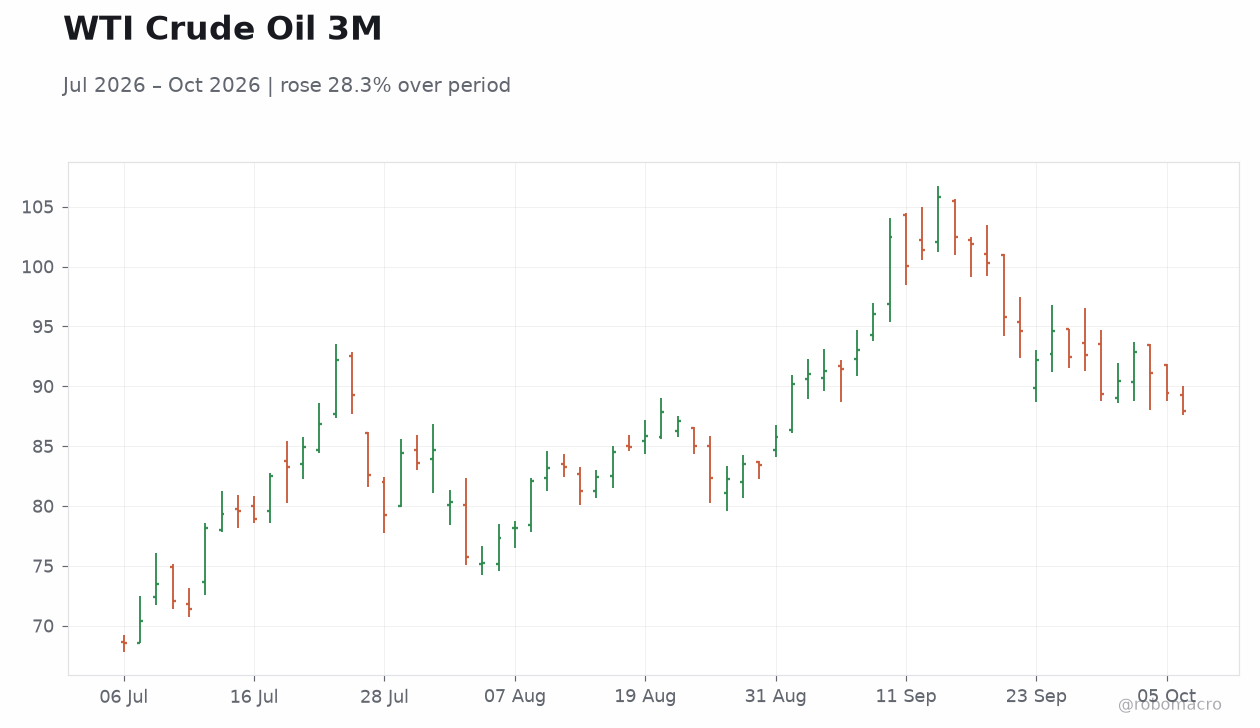
| WTI Crude | 87.99 | -1.61% |
| Gold | 4,181.40 | +0.59% |
| Bitcoin | 85,918.15 | +0.15% |
| Brazil 5Y Govt Yield | 14.11% | +5 bp |
| Brazil 10Y Govt Yield | 14.17% | +15 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| S&P Global Services PMI | 50.50 | - | 49.20 |
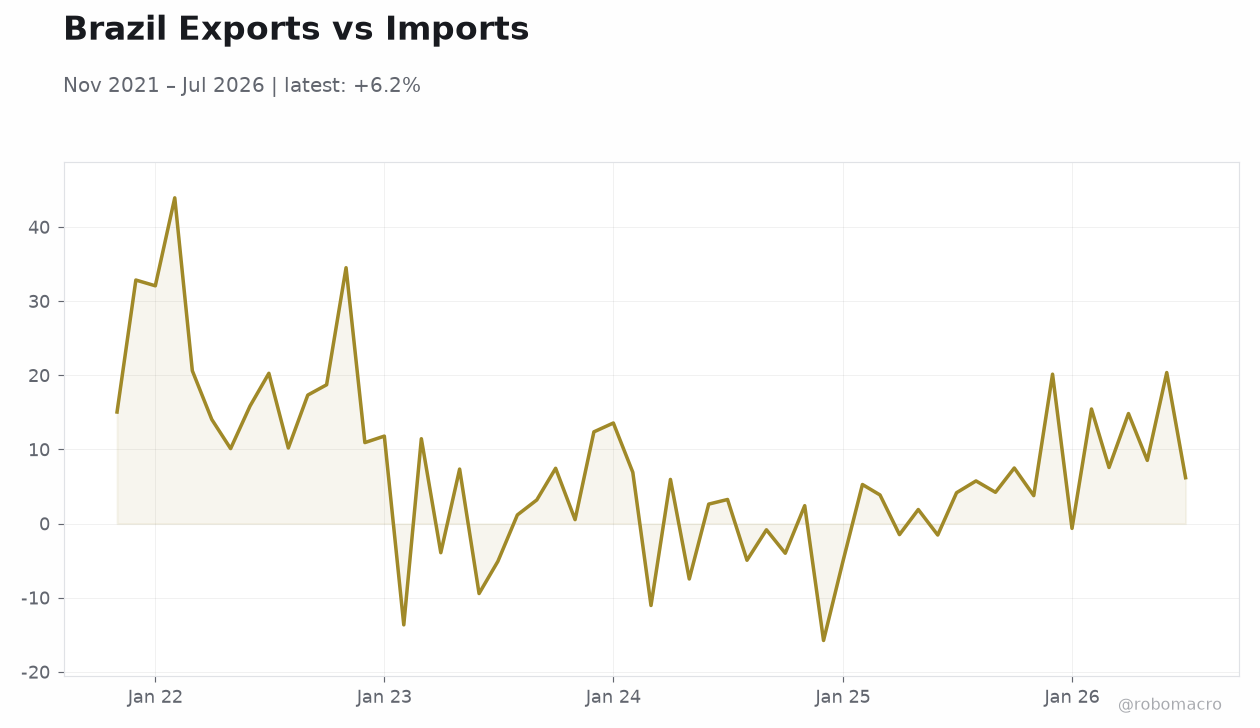 Brazil Exports vs Imports | Type: macro_line | Exports USD mn: 6.195 (2026-07-01) | Range: -15.76–43.94 | Trend(5pt): 15.05,11.81,-11.04,1.904,6.195
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Trade Balance | 7,390m | 7,190m | 14:00 |
| Friday (2026-10-09) | |||
| Inflation Rate Month-over-Month | -0.32 | 0.73 | 08:00 |
| Inflation Rate Year-over-Year | 4.22 | 4.50 | 08:00 |
- Flávio Bolsonaro leads Lula 47.03%-45.16% in first round, sending presidential race to October 25 runoff
- Bovespa jumps 7.70% to 206,912 while USD/BRL falls 4.43% to 4.99 on reduced near-term uncertainty
- Services PMI contracts to 49.2 from 50.5, signaling mild downside risk to Q4 activity
Yesterday's Recap
Brazilian assets rallied sharply after Flávio Bolsonaro posted a stronger-than-expected first-round result against incumbent Lula, sending the presidential contest to a runoff. Bovespa closed at 206,912, up 7.70%, while Petrobras surged 11.50% to 24.14 and Vale rose 2.83% to 14.15. USD/BRL dropped 4.43% to 4.99 and EUR/BRL fell 4.33% to 5.62 as investors priced lower near-term political risk.
Brazil 5Y yields rose 5 bp to 14.11% and 10Y yields climbed 15 bp to 14.17%. S&P Global Services PMI printed 49.2 versus 50.5 prior, marking the first sub-50 reading in several months and pointing to contraction in the dominant services sector. The data release had limited immediate market impact amid election-driven flows.
WTI Crude eased 1.61% to 87.99 while gold edged higher.
The Day Ahead
Brazil Trade Balance for September is due at 14:00 ET with consensus at USD 7.19 bn versus 7.39 bn prior. The print carries medium impact and will be watched for implications on the current-account balance and BRL support. No BCB speeches or COPOM minutes are scheduled.
On Friday, August inflation data will be released, with CPI MoM expected at 0.73% after -0.32% and CPI YoY seen at 4.50% after 4.22%. Markets will parse the prints for clues on the inflation trajectory ahead of the runoff. Focus remains on how the election outcome may shape fiscal and commodity-export policy.
Other Economic Notes
The runoff winner will confront the task of steering Brazil out of economic crisis amid elevated real yields and still-high Selic at 13.75%. Coverage has centered on potential shifts in relations with China, critical-minerals policy, and BRICS engagement under a possible Flávio Bolsonaro administration. Iron-ore and oil exporters such as Vale and Petrobras could face different demand and regulatory outlooks depending on the result.
Fiscal sustainability remains a key investor concern given the absence of new consolidation measures in the campaign. The services contraction adds mild downside risk to growth forecasts already under pressure from political transition.