RoboMacro ResearchAlso todaySee the FX Daily

Brazil Macro Daily(Beta Mode)

October 15, 2026 robomacro.com

Real Yields Ease as Confidence Beats

46.20 Business Confidence
Bovespa206,506.00-0.18%
USD/BRL5.03+0.08%
EUR/BRL5.65+0.31%
Vale13.21-1.20%

Market Snapshot

AssetLevelChange
Bovespa206,506.00-0.18%
USD/BRL5.03+0.08%
EUR/BRL5.65+0.31%
Vale13.21-1.20%
Petrobras25.94+1.73%
WTI Crude95.13+0.04%
Gold4,173.70+1.60%
Bitcoin81,266.01-0.36%
Brazil 5Y Govt Yield12.46%-2 bp
Brazil 10Y Govt Yield12.50%-7 bp

Prior Economic Events

Data Prior Cons Actual
Business Confidence Index44.90-46.20
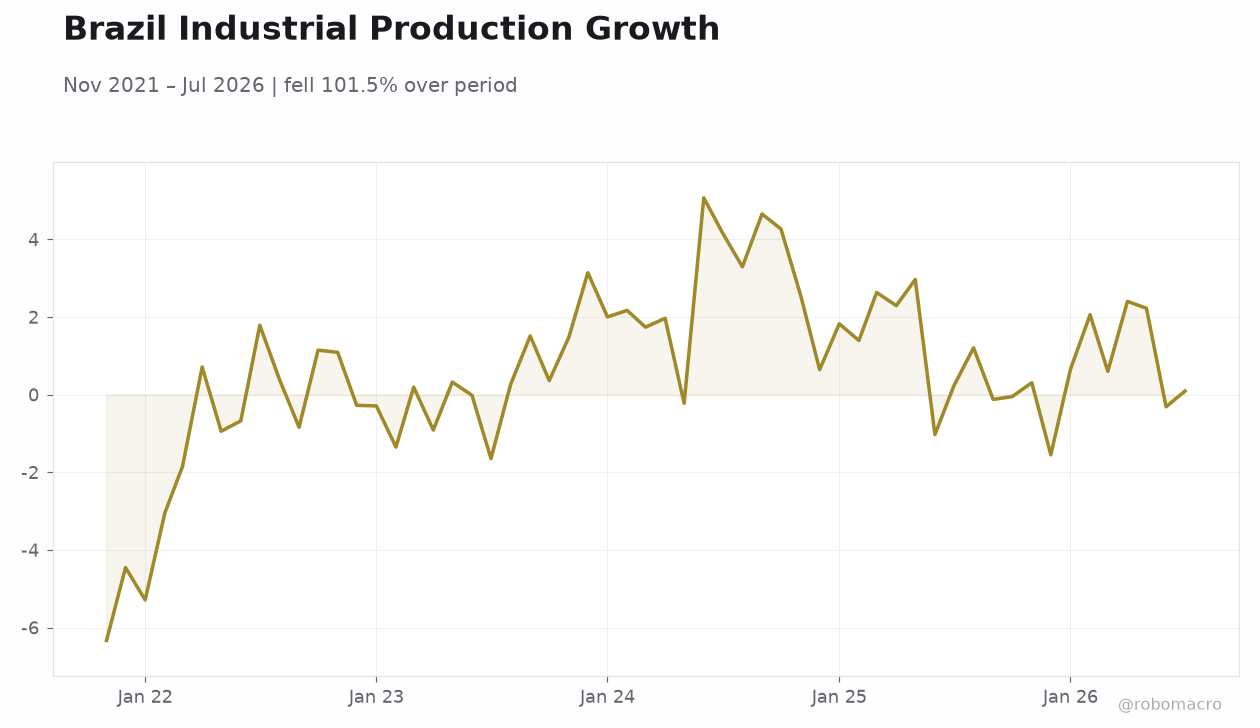
Brazil Industrial Production GrowthBrazil Industrial Production Growth | Type: macro_line | Industrial Prod YoY %: 0.09432 (2026-07-01) | Range: -6.332–5.071 | Trend(5pt): -6.332,-0.2891,1.739,2.968,0.09432

Today's Economic Events

Data Prior Cons Time
Retail Sales Month-over-Month-0.800.7008:00
  • Business confidence jumped to 46.2 from 44.9, while the 10-year yield eased 7 bp to 12.50%.
  • Petrobras led Bovespa gainers, up 1.73%, as crude held near $95.
  • Retail sales due today at 08:00 ET; consensus +0.7% m/m after -0.8% prior.

Yesterday's Recap

Brazilian risk assets found a firmer footing on Tuesday. The Bovespa closed marginally lower at 206,506, down 0.18%, but the composition of trade was constructive: Petrobras surged 1.73% and led gainers, buoyed by firm crude, while Vale lagged at -1.20% on softer iron ore sentiment. The local rates complex rallied, with the 10-year government yield easing 7 bp to 12.50% and the 5-year down 2 bp at 12.46% — a flattening that suggests growing conviction in a disinflationary path.

On the data front, the Getulio Vargas Foundation's business confidence index surprised to the upside, printing 46.2 against a prior 44.9 — a solid recovery that hints at improving sentiment among services and industry executives despite still-sub-50 territory. USD/BRL was essentially flat, edging up 0.08% to 5.03, while EUR/BRL strengthened 0.31% to 5.65 on euro-area rate dynamics. The real's stability despite a firmer dollar underscores resilient carry appeal with the Selic at 13.75%.

Gold's 1.60% jump to $4,173 offered a tailwind for the commodity complex broadly.

The Day Ahead

Today's focal point is the IBGE retail sales release at 08:00 ET, where the market looks for a 0.7% m/m rebound after the prior -0.8% contraction. A beat would reinforce the narrative that household consumption is holding up better than feared even under restrictive monetary conditions, while a miss could revive concerns about the durability of the domestic demand cycle. The retail print carries added weight this cycle given September CPI at 4.58% y/y — comfortably above the 3% target midpoint — and the BCB's stated dependence on activity data to calibrate the pace of easing.

Beyond the headline, analysts will scrutinize the split between durables and supermarkets, as well as the broader quarterly series for trend confirmation. No major auctions or central bank appearances are on the calendar, leaving the data and external markets to set the tone. Positioning into the print looks balanced after Tuesday's rates rally.

Other Economic Notes

Congress approved a constitutional amendment capping the workweek at 40 hours and banning six-day schedules, a landmark labor reform affecting up to 30 million workers that President Lula championed ahead of the October runoff. ↓ p.2
Page 1

Brazil Macro Daily(Beta Mode)

October 15, 2026 robomacro.com
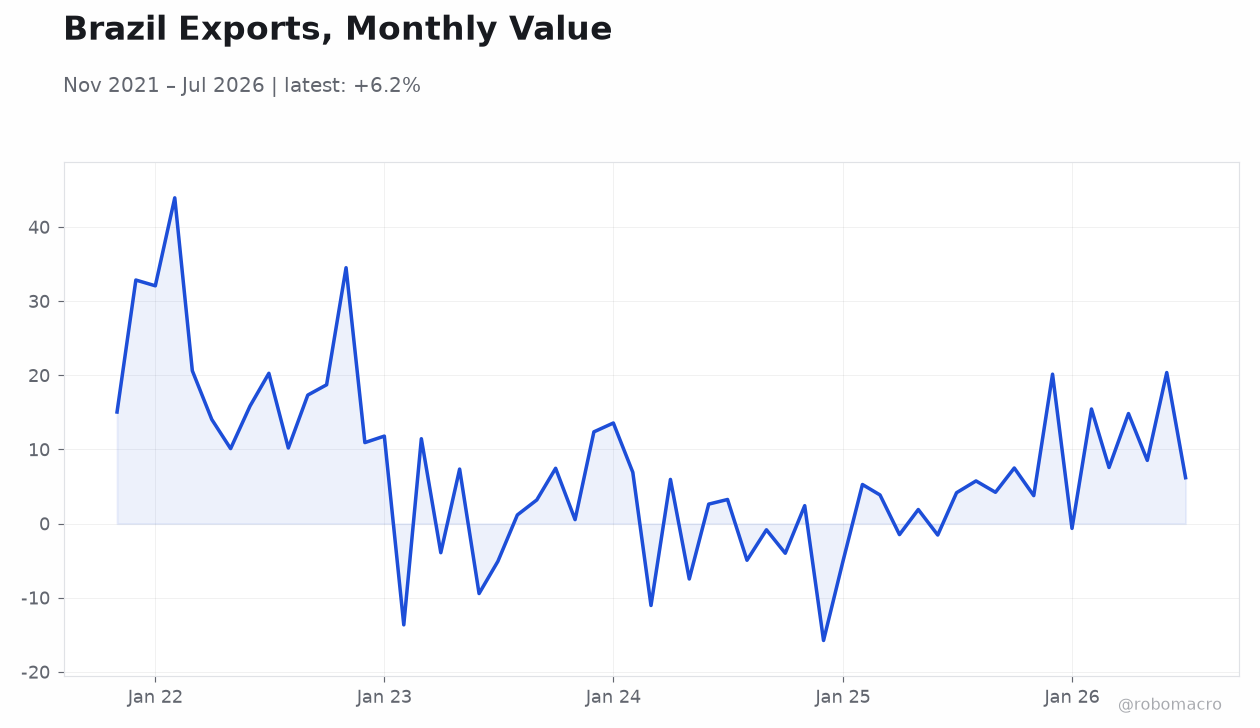
Brazil Exports, Monthly Value Brazil Exports, Monthly Value | Type: macro_line | Exports USD mn: 6.195 (2026-07-01) | Range: -15.76–43.94 | Trend(5pt): 15.05,11.81,-11.04,1.904,6.195
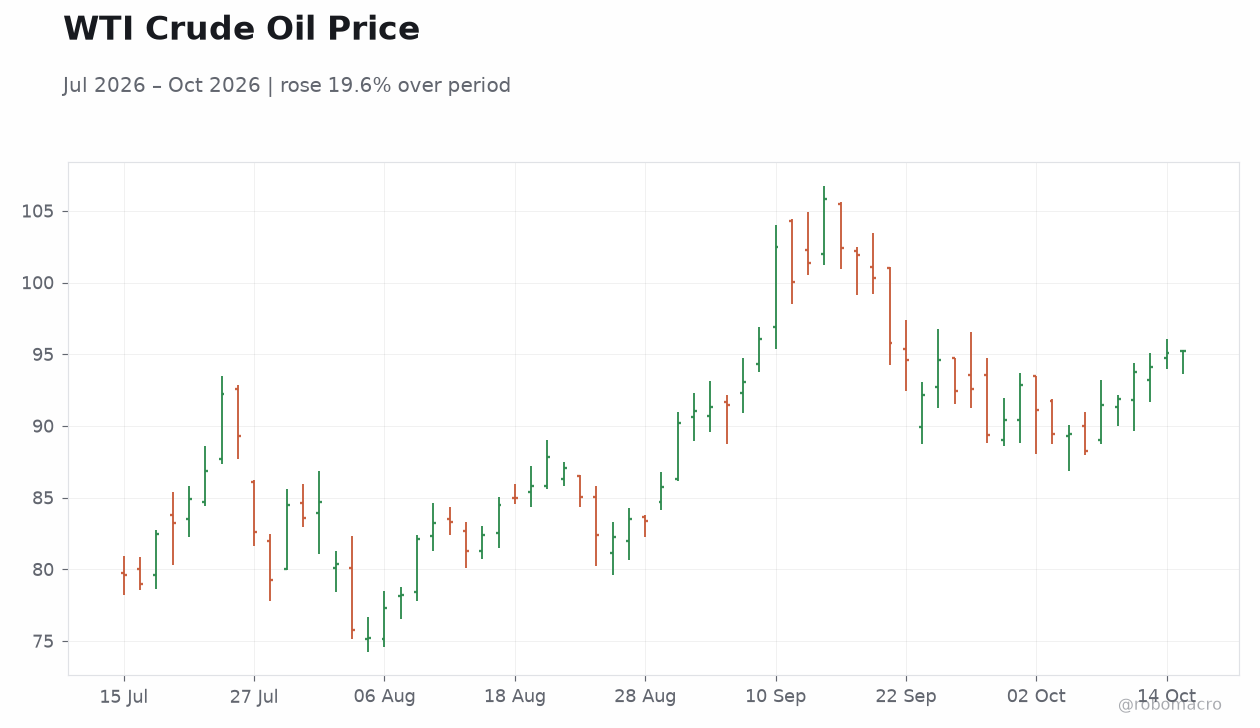
WTI Crude Oil Price WTI Crude Oil Price | Type: market_hloc | USD/bbl: 95.19 (2026-10-15) | Range: 75.22–105.8 | Trend(6pt): 79.6,77.29,83.4,94.59,95.09,95.19
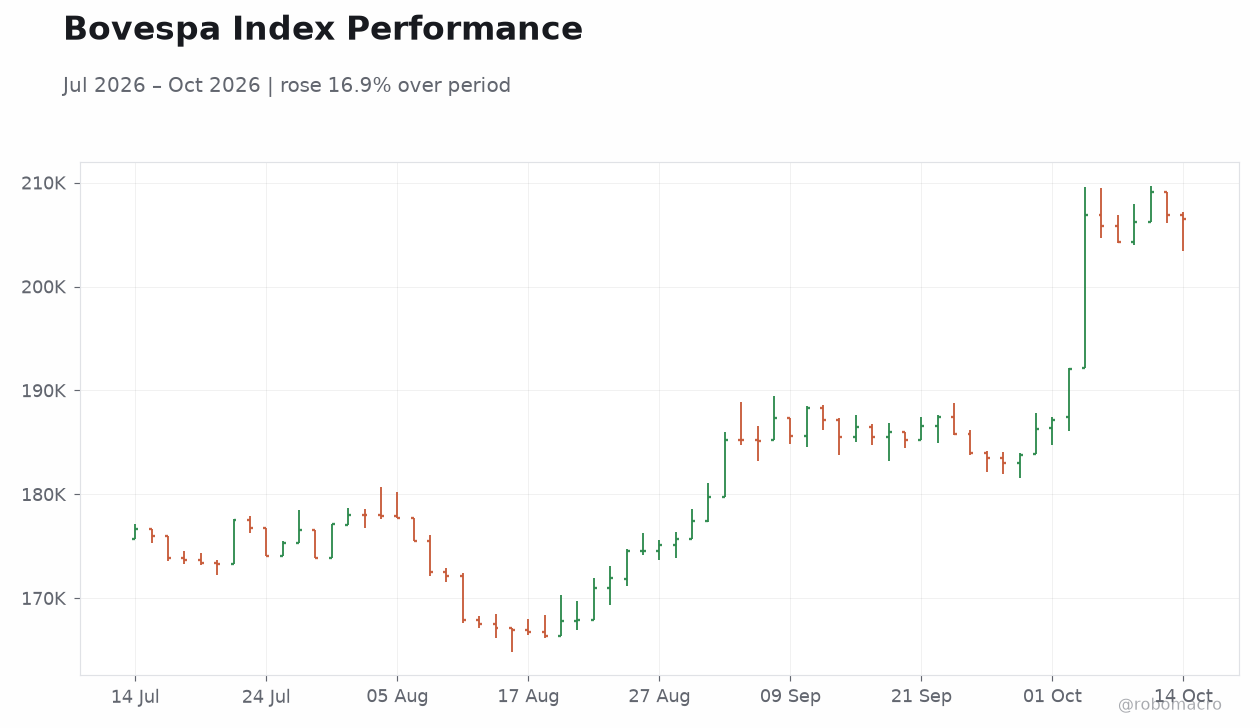
Bovespa Index Performance Bovespa Index Performance | Type: market_hloc | Index Level: 2.065e+05 (2026-10-14) | Range: 1.663e+05–2.091e+05 | Trend(5pt): 1.766e+05,1.777e+05,1.751e+05,1.866e+05,2.065e+05
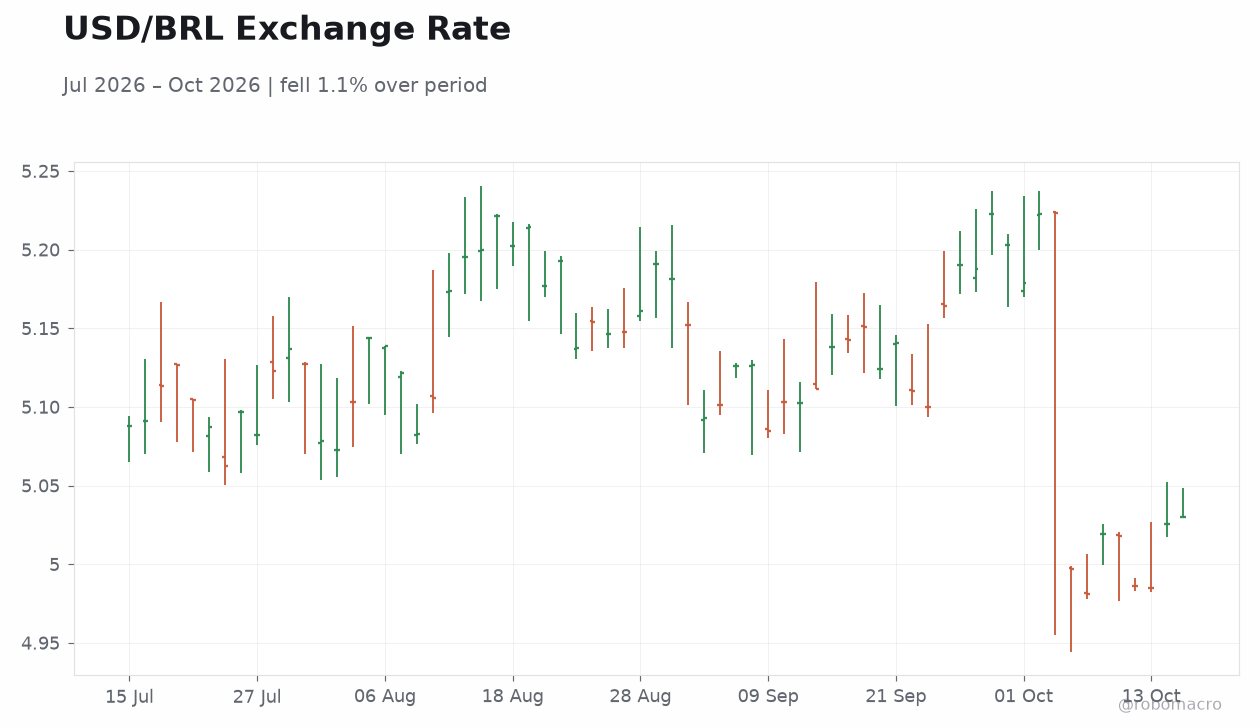
USD/BRL Exchange Rate USD/BRL Exchange Rate | Type: market_hloc | USD/BRL: 5.03 (2026-10-15) | Range: 4.981–5.223 | Trend(6pt): 5.088,5.139,5.161,5.141,4.985,5.03

Other Economic Notes (continued)

Economists flag near-term productivity and payroll cost questions, though phased implementation blunts the immediate fiscal hit. Separately, agribusiness continues to anchor the external accounts: projections cited in local media see Brazil potentially becoming the world's largest food exporter by end-2026, reinforcing the structural surplus in the soy, beef, and sugar complex. China's return to large-scale US soybean purchases post-summit bears watching for Brazilian origin competition into the November-January window.

Global Macro News

The global backdrop is a tale of divergent monetary paths. Hot US CPI prints have revived Federal Reserve hike bets, pressuring sterling and lifting the dollar broadly — yet the real has held its ground, a testament to Brazil's attractive carry. Oil remains supported near $95 by Middle East tensions and supply disruption risks, directly benefiting Petrobras and fiscal accounts via royalties.

Gold's run to $4,173 reflects hedging demand amid geopolitical uncertainty. In Europe, ECB commentary has pushed EUR/BRL higher, complicating the import-price calculus. China's renewed soybean buying is the key marginal demand signal for Brazilian agriculture.

Entain's results flagged softer Brazilian gaming revenue, a minor consumer discretionary data point. Climate litigation risks are mounting for majors like Shell after Brazilian flooding, an ESG cost vector for oil.

Sponsored by Arbitrage Search
Page 2

Brazil Macro Daily(Beta Mode)

October 15, 2026 robomacro.com

Continuation

BCB Watch

The Copom's stance remains data-dependent with the Selic at 13.75% and September IPCA at 4.58% y/y. Tuesday's rally in long-dated yields — the 10-year down 7 bp — suggests the market is pricing a smoother easing trajectory than feared a month ago, likely on fiscal consolidation signals and the confidence uptick. Communications have emphasized patience: with inflation expectations above target and activity resilient, there is no urgency to accelerate cuts.

The 5s10s configuration, with the long end just 4 bp above the belly, implies a flat curve consistent with terminal-rate conviction rather than reflation trades. Watch for minutes' language on the labor reform's second-round effects and any revision to the disinflation path. The 40-hour week adds a structural productivity wildcard to supply-side models.

For now, the 12.50% 10-year offers attractive yields for duration buyers, but fiscal execution into the runoff remains the swing factor for the curve's downside room.

Sponsored by Arbitrage Search
Page 3