RoboMacro ResearchAlso todaySee the US Macro Daily

Brazil Macro Daily(Beta Mode)

October 19, 2026 robomacro.com

Real Steadies as Yields Climb Pre-Runoff

Bovespa205,430.00+0.54%
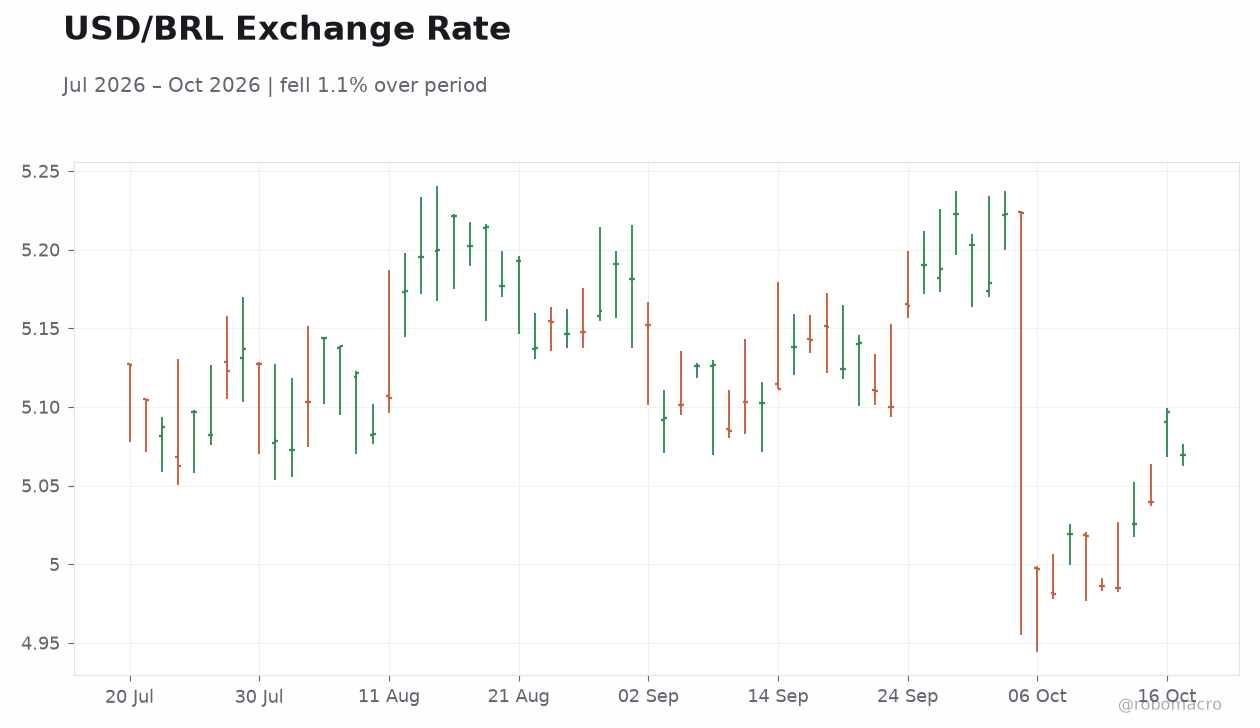
USD/BRL5.07-0.54%
EUR/BRL5.70-0.26%
Vale13.06+0.31%

Market Snapshot

AssetLevelChange
Bovespa205,430.00+0.54%
USD/BRL5.07-0.54%
EUR/BRL5.70-0.26%
Vale13.06+0.31%
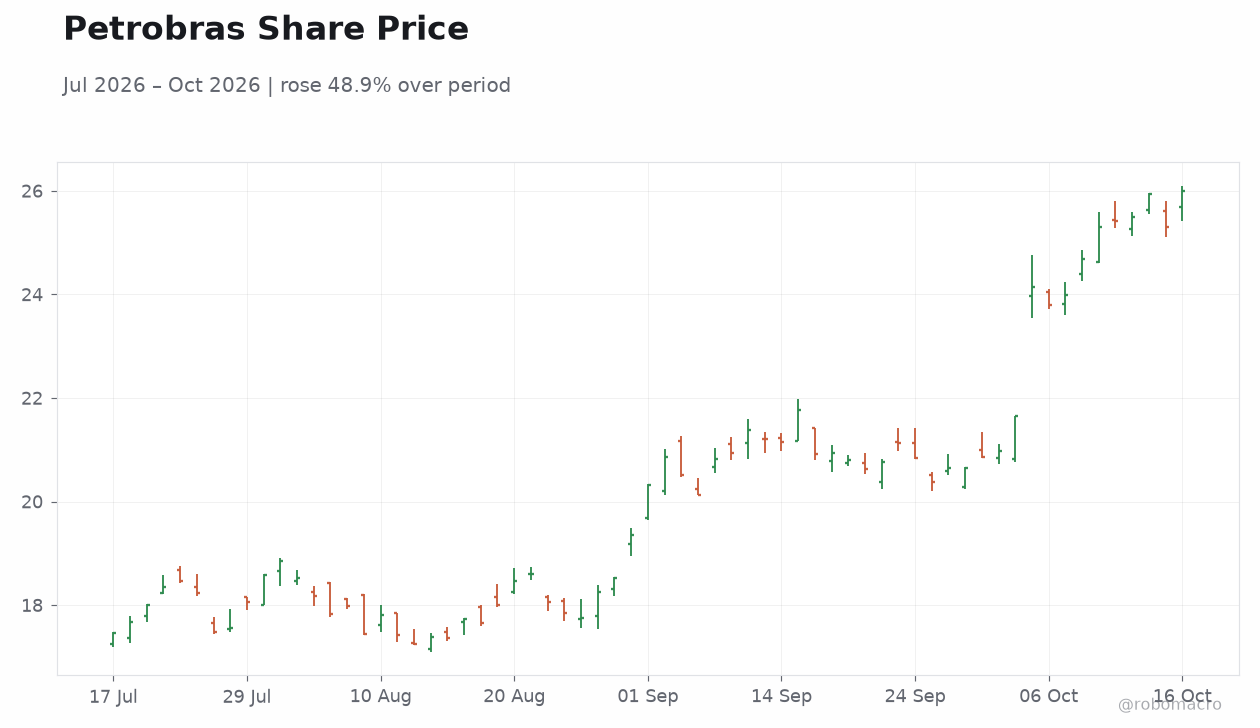
Petrobras26.00+2.77%
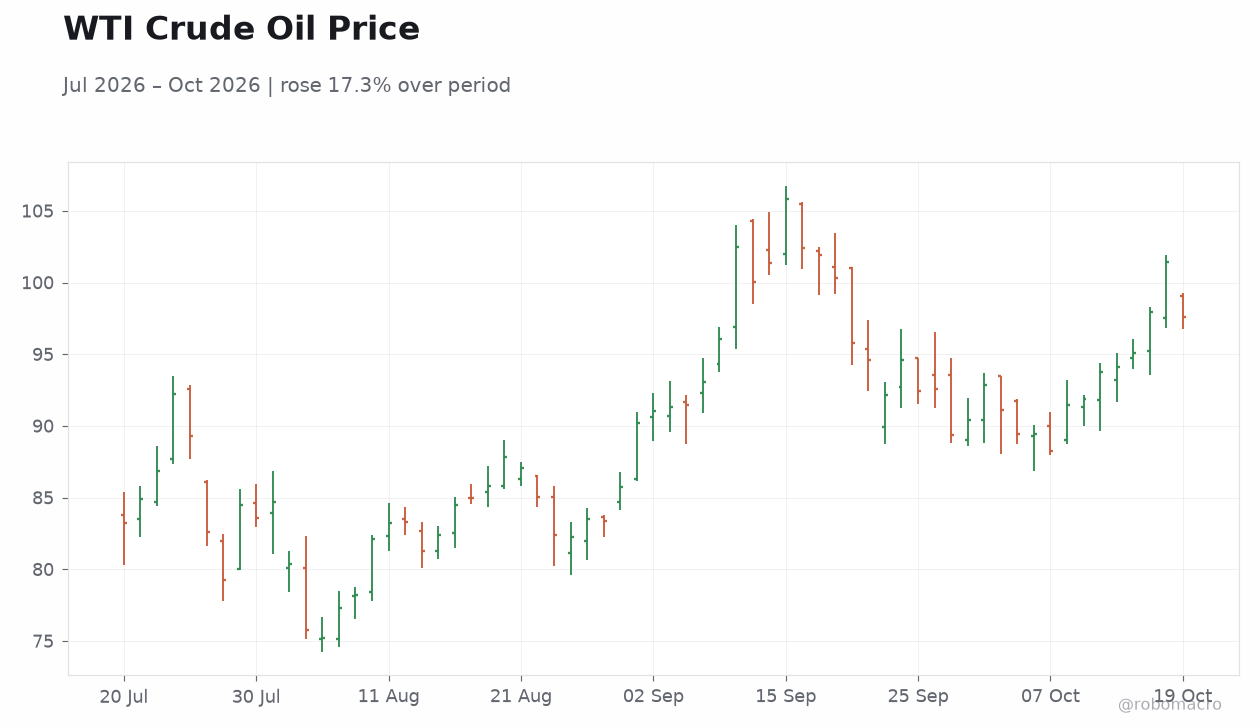
WTI Crude97.47-3.89%
Gold4,192.30+0.27%
Bitcoin82,746.89+0.89%
Brazil 5Y Govt Yield12.79%+14 bp
Brazil 10Y Govt Yield12.87%+16 bp

Prior Economic Events

Data Prior Cons Actual
No events available
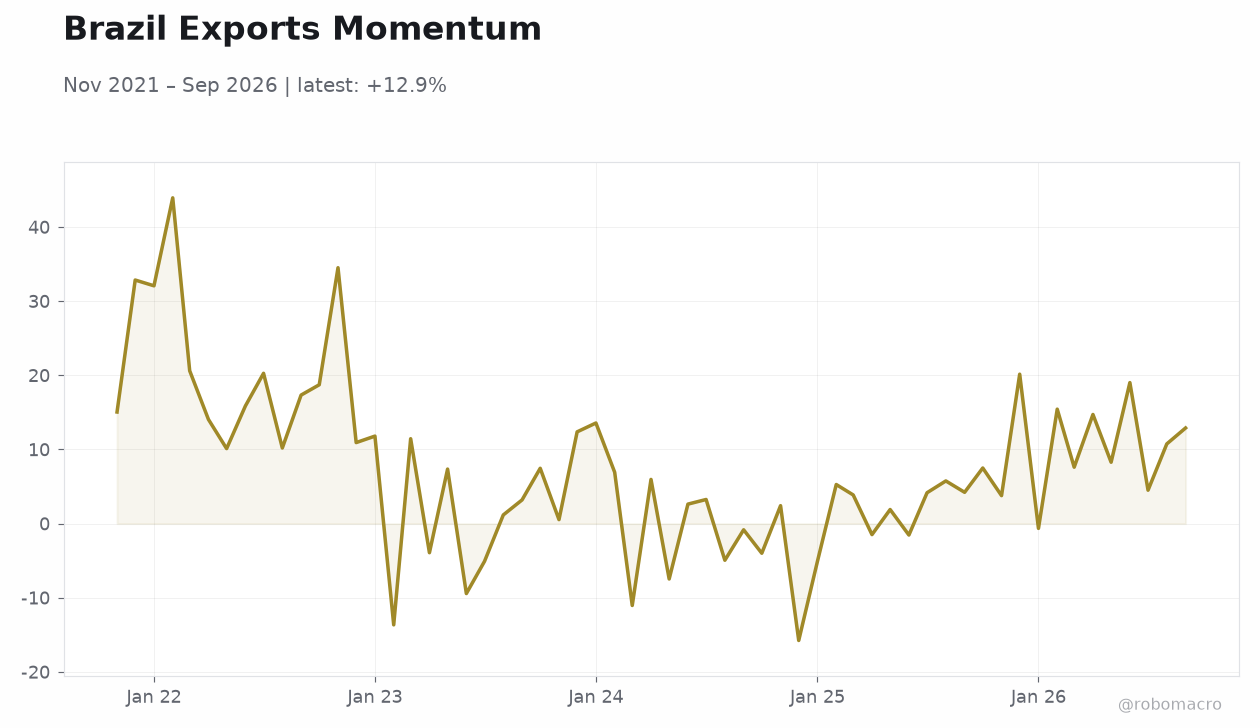
Brazil Exports MomentumBrazil Exports Momentum | Type: macro_line | Exports (USD, % YoY): 12.9 (2026-09-01) | Range: -15.76–43.94 | Trend(6pt): 15.05,11.81,-11.04,1.904,4.51,12.9

Today's Economic Events

Data Prior Cons Time
No events available
  • The real firmed 0.54% to 5.07/USD while Bovespa gained 0.54% to 205,430, led by a 2.77% jump in Petrobras as crude held near $97.
  • Local rates sold off with the 5-year up 14 bp to 12.79% and the 10-year up 16 bp to 12.87%, reflecting fiscal caution ahead of the October 25 run-off.
  • IBC-Br proxy GDP rose 0.3% m/m in August, up 1.2% y/y, while Amazon deforestation hit a record low and IMF projections see Brazil regaining its rank as the world's eighth-largest economy by 2027.

Yesterday's Recap

Friday's session closed with the Bovespa up 0.54% at 205,430, with Petrobras the standout gainer at +2.77% to 26.00 reais as WTI held near $97 despite a 3.89% intraday retreat. Vale added 0.31% to 13.06 reais, tracking steady iron ore sentiment. The real appreciated 0.54% to 5.07 per dollar, outperforming a modest 0.26% gain in the euro cross at 5.70.

Local fixed income weakened, with the 5-year government yield rising 14 bp to 12.79% and the 10-year climbing 16 bp to 12.87%, a curve steepening that suggests investors are pricing fiscal risk into the post-election outlook. On the data front, the central bank's IBC-Br economic activity index rose 0.3% m/m in August and 1.2% y/y, confirming growth momentum without overheating. The political calendar dominated headlines: Lula and Bolsonaro clashed in a bitter final debate before the October 25 run-off, while Bloomberg flagged that market euphoria over Flávio Bolsonaro's early success risks obscuring Brazil's surging debt trajectory.

Gold firmed 0.27% to $4,192 and Bitcoin rose 0.89% to $82,747.

The Day Ahead

Monday's calendar is light on tier-one releases, leaving markets to consolidate Friday's moves and position for the run-off in six days. Attention turns to any additional polling data following the final presidential debate, with bookmakers and local surveys likely to drive intraday real and rates volatility. The focus remains on the fiscal platforms of both campaigns, particularly commitments around the spending cap and tax reform sequencing.

Globally, Chinese Q3 GDP and September activity data due this week will shape the iron ore and soybean demand outlook that underpins Brazil's trade surplus. Oil markets will digest last week's sharp pullback from highs, with implications for Petrobras dividends and the fiscal accounts given the state's reliance on energy revenues. Expect thin liquidity in local rates as participants await clearer electoral signals before adding duration.
Page 1

Brazil Macro Daily(Beta Mode)

October 19, 2026 robomacro.com
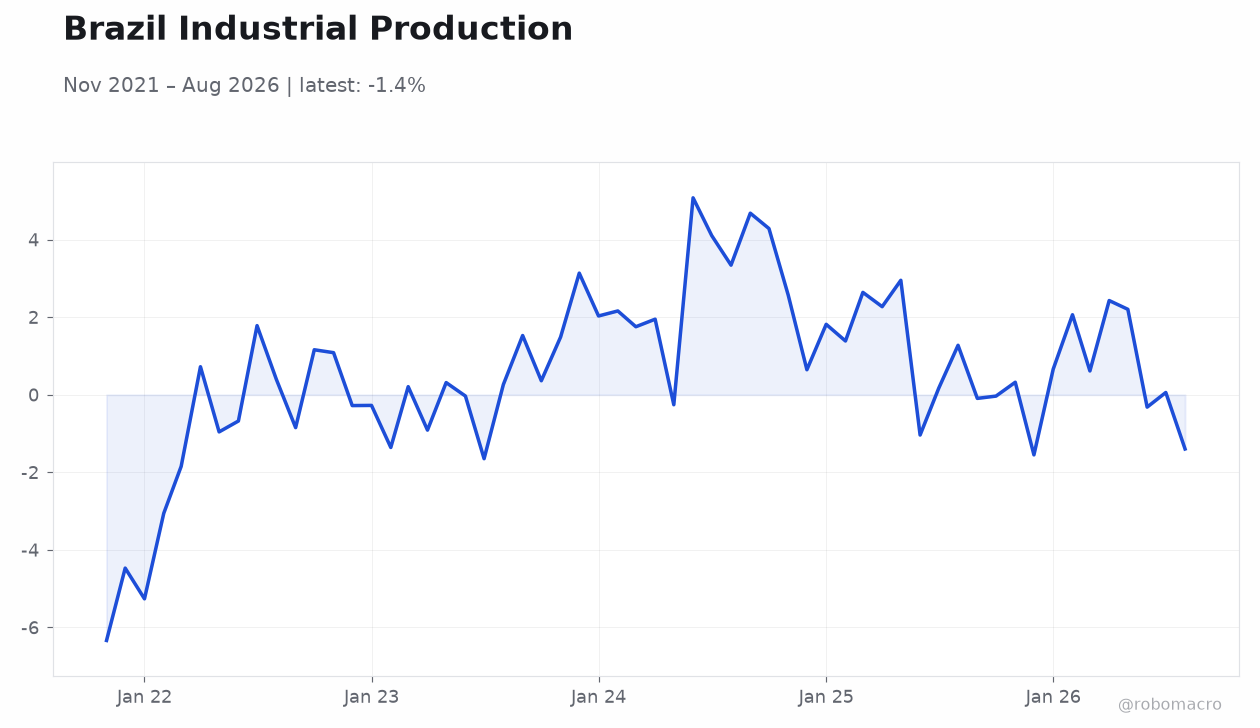
Brazil Industrial Production Brazil Industrial Production | Type: macro_line | Industrial Production (% YoY): -1.398 (2026-08-01) | Range: -6.335–5.078 | Trend(6pt): -6.335,-0.2744,1.754,2.951,0.05853,-1.398
Petrobras Share Price Petrobras Share Price | Type: market_hloc | USD per Share: 26 (2026-10-16) | Range: 17.25–26 | Trend(5pt): 17.46,17.81,20.33,20.84,26
USD/BRL Exchange Rate USD/BRL Exchange Rate | Type: market_hloc | BRL per USD: 5.069 (2026-10-19) | Range: 4.981–5.223 | Trend(6pt): 5.127,5.106,5.152,5.164,5.097,5.069
WTI Crude Oil Price WTI Crude Oil Price | Type: market_hloc | USD per Barrel: 97.59 (2026-10-19) | Range: 75.22–105.8 | Trend(5pt): 83.23,83.2,91.01,92.41,97.59

Other Economic Notes

The structural story of the week is Brazil's re-rating in the global hierarchy, with the IMF projecting the economy regains its position as the world's eighth-largest by 2027, driven partly by Chinese demand for Brazilian crude and agricultural exports. Domestically, the IBC-Br's 0.3% August gain confirms the expansion is broadening but gradual, consistent with a soft-landing profile rather than overheating. Environmental metrics are emerging as an asset-class signal: Amazon deforestation fell to its lowest level since records began in 1988, a milestone that strengthens the case for sustainable-finance flows into Brazilian paper.

The fiscal picture remains the key vulnerability, with debt dynamics flagged by Bloomberg as the overlooked risk beneath the post-election rally. Lula's late-campaign pivot on lowering the age of criminal responsibility to 16 underscores the transactional nature of coalition-building that markets should expect regardless of the winner.

Global Macro News

Crude's 3.89% retreat from $97 levels frames the week's commodity narrative, with WTI's pullback a headwind for Petrobras earnings and Brazilian terms of trade. China's oil demand resilience remains the linchpin for Brazilian export volumes, as highlighted in coverage of the country's climb up the IMF rankings. Gold's advance to $4,192 and Bitcoin's 0.89% gain to $82,747 reflect continued appetite for alternative stores of value even as equity markets grind higher.

The euro's 0.26% dip against the real at 5.70 signals relative stability in cross-market flows. ↓ p.3

Sponsored by Arbitrage Search
Page 2

Brazil Macro Daily(Beta Mode)

October 19, 2026 robomacro.com

Continuation

Global Macro News (continued)

Emerging market assets broadly benefited from a risk-on tone, though Brazil's local rates sell-off against a firmer currency suggests idiosyncratic fiscal and electoral premia are dominating the rates complex. The divergence between equity strength and bond weakness is a classic pre-election pattern, and the resolution on October 25 should narrow it. Watch for spillover from US rate expectations into the high-carry trade that has supported BRL carry positions.

BCB Watch

The Selic stands at 13.75% following the October 13 decision, leaving the policy rate 917 bp above the 4.58% September CPI print in real terms, an unusually restrictive stance by historical standards. With headline inflation at 4.58% y/y, the bank has room to signal gradual normalization once electoral uncertainty clears, though the fiscal outlook complicates the path. The 16 bp rise in the 10-year yield to 12.87% suggests markets want firmer commitment on the disinflation trajectory before pricing cuts.

COPOM communications have emphasized data dependence, and the strong IBC-Br print argues against premature easing. The key question for the November meeting is whether the committee frames the 13.75% level as the terminal rate or leaves optionality for further tightening if the real weakens post-election. The inflation-targeting framework's credibility, tested through successive supply shocks, remains the anchor for the 5-year at 12.79%.

A post-run-off rally in the real would give the bank flexibility to begin a measured easing cycle in early 2027 without breaching the target band.

Sponsored by Arbitrage Search
Page 3