Brazil Macro Daily(Beta Mode)
Real Rates Bite as Curve Steepens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
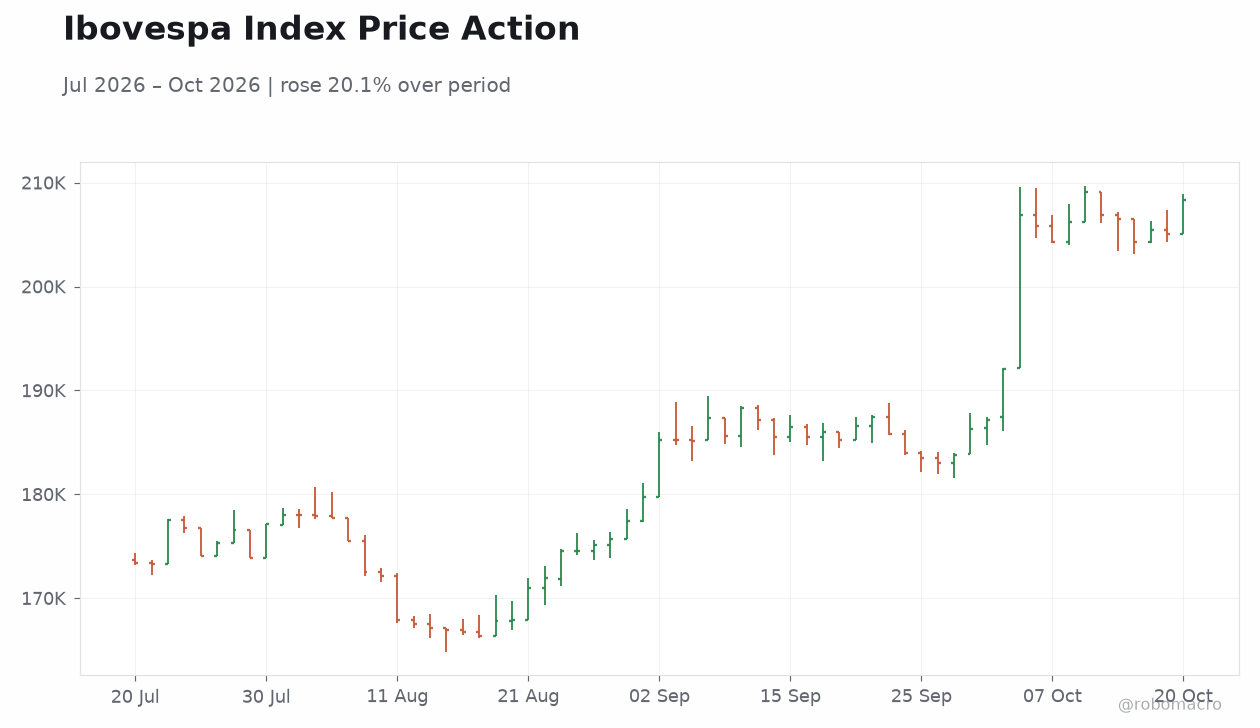
| Bovespa | 208,296.00 | +1.57% |
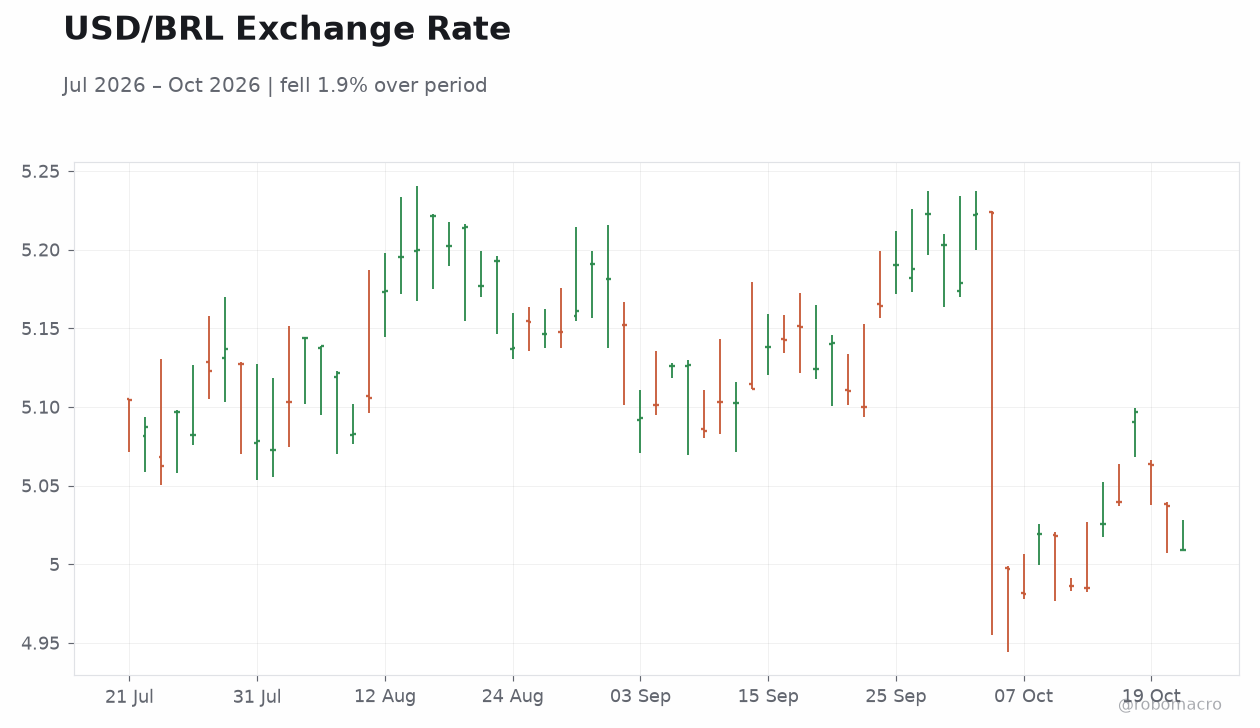
| USD/BRL | 5.01 | -0.55% |
| EUR/BRL | 5.63 | -0.38% |
| Vale | 13.02 | -0.69% |
| Petrobras | 25.70 | +0.55% |
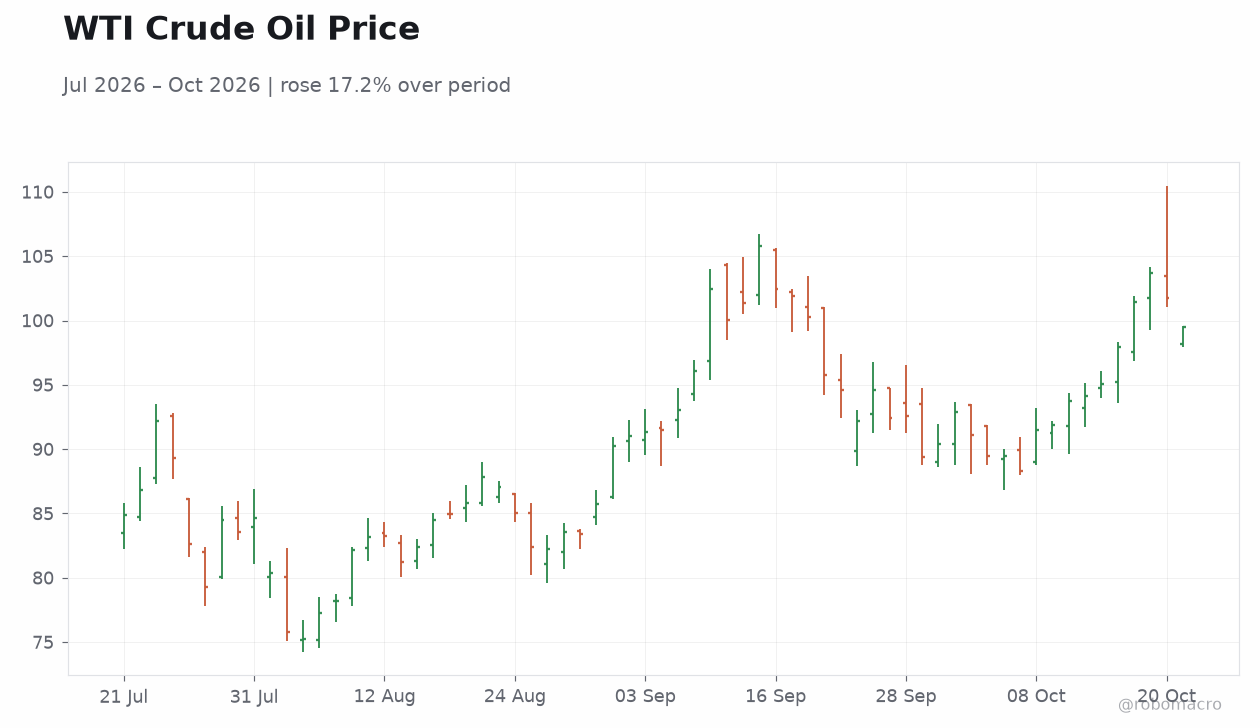
| WTI Crude | 99.33 | -2.42% |
| Gold | 4,138.90 | -0.09% |
| Bitcoin | 83,178.89 | +0.29% |
| Brazil 5Y Govt Yield | 12.79% | +14 bp |
| Brazil 10Y Govt Yield | 12.87% | +16 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
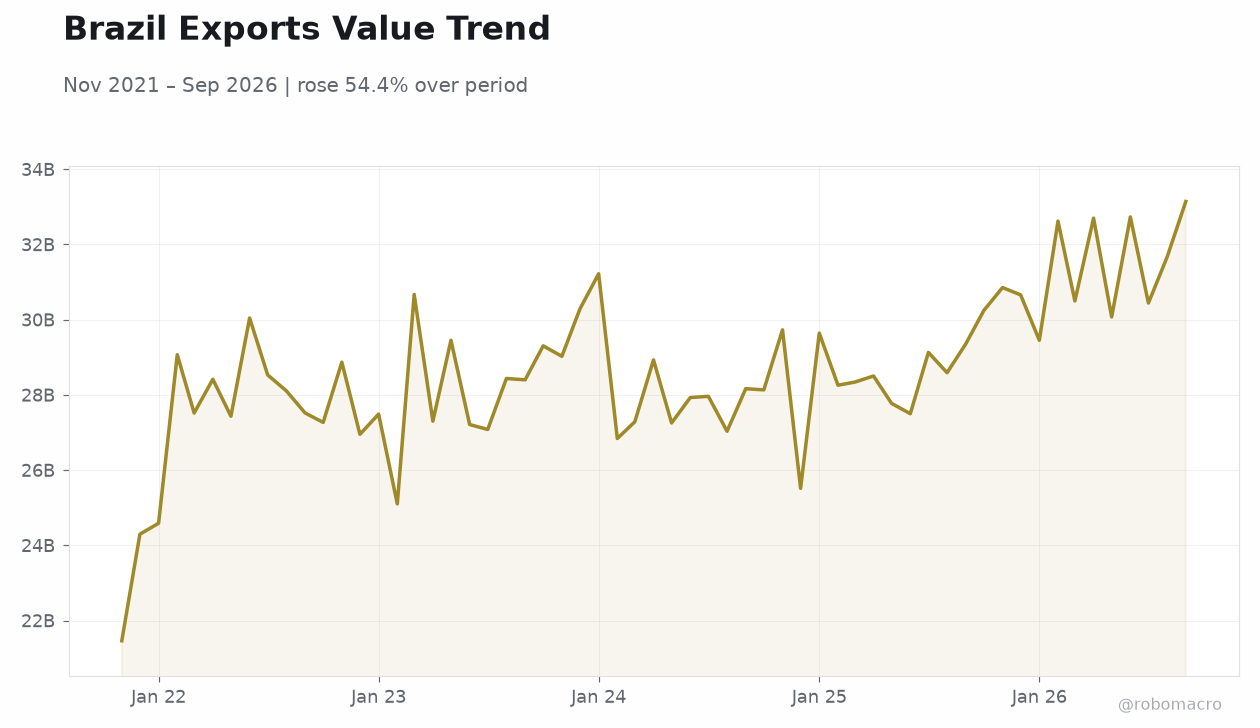 Brazil Exports Value Trend | Type: macro_line | Exports (USD): 3.314e+10 (2026-09-01) | Range: 2.146e+10–3.314e+10 | Trend(6pt): 2.146e+10,2.749e+10,2.729e+10,2.777e+10,3.044e+10,3.314e+10
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Ibovespa rallied 1.57% to 208,296 as USD/BRL slipped 0.55% to 5.01, but the local curve sold off with 10Y yields up 16 bp to 12.87% and 5Y up 14 bp to 12.79%.
- Labor-cost pressures dominate the micro narrative: unit labor costs at decade highs and "uberisation" of the workforce keep services inflation sticky against CPI at 4.58% YoY.
- Election runoff risk premium is building into term premia even as equities and FX celebrate — a divergence worth watching into the runoff vote.
Yesterday's Recap
Brazilian assets delivered a split session on October 20, with equities and FX moving in one direction and the rates market in the other. The Ibovespa closed up 1.57% at 208,296, extending a risk-on run, while the real strengthened 0.55% to 5.01 per dollar and 0.38% against the euro to 5.63. Petrobras added 0.55% to 25.70 even as WTI crude fell 2.42% to 99.33, while Vale lagged, down 0.69% to 13.02 amid reports of rotation out of the miner into the oil major.
The local curve, however, steepened: the 5-year yield rose 14 bp to 12.79% and the 10-year 16 bp to 12.87%, with the long end underperforming — consistent with elevated fiscal and term-premium concerns even as risk assets rallied. No official Brazilian data releases were scheduled for the session, leaving market technicals and political headlines to drive price action. The divergence between a stronger real and a weaker bond market is the key signal: FX is pricing external relief, while rates are pricing domestic fiscal risk.
The Day Ahead
The October 21 calendar is empty for Brazil, so flow will be driven by positioning ahead of the presidential runoff and by external cues. With no domestic prints, the market will focus on the real's ability to hold the 5.01 handle and on whether the curve continues to steepen after Tuesday's long-end underperformance. Commodity channels matter: iron ore and oil moves will feed directly into Vale and Petrobras, the two heaviest index names.
Watch for any BCB communication or fiscal headlines that could shift term premia. Expect thinner liquidity as investors await the runoff outcome.
Other Economic Notes
Brazil's labor market is the quiet inflation risk. Unit labor costs have reached decade-high levels, per Valor International, and the Financial Times' "uberisation" narrative points to a workforce increasingly reliant on informal, platform-based income — a structure that complicates both productivity gains and services disinflation. The IMF expects Brazil to regain its ranking as the 8th-largest economy by 2027, a reminder that the medium-term growth story remains intact despite near-term fiscal noise.
↓ p.2