Brazil Macro Daily(Beta Mode)
Yields Rise as Fiscal Worries Intensify
Market Snapshot
| Asset | Level | Change |
|---|---|---|
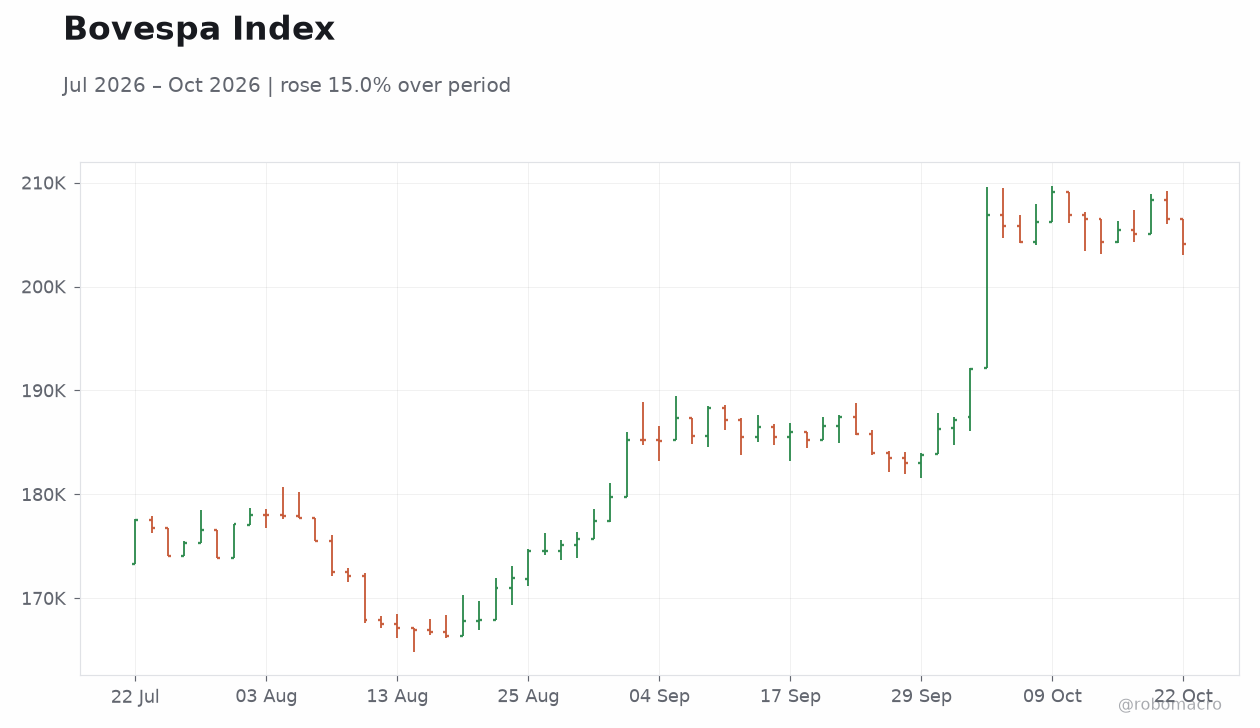
| Bovespa | 204,120.00 | -1.15% |
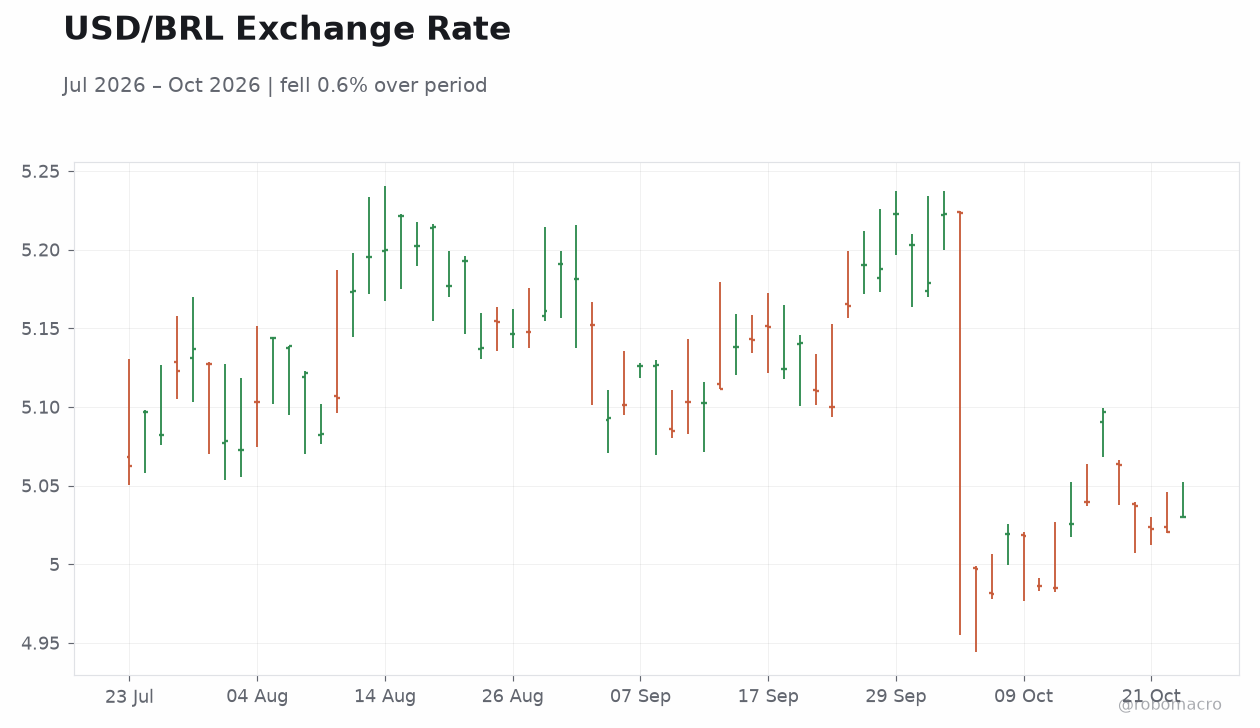
| USD/BRL | 5.03 | +0.19% |
| EUR/BRL | 5.64 | -0.05% |
| Vale | 12.20 | -3.94% |
| Petrobras | 25.62 | -0.16% |
| WTI Crude | 100.31 | +0.84% |
| Gold | 4,042.30 | -0.45% |
| Bitcoin | 81,678.24 | +0.45% |
| Brazil 5Y Govt Yield | 12.79% | +14 bp |
| Brazil 10Y Govt Yield | 12.87% | +16 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
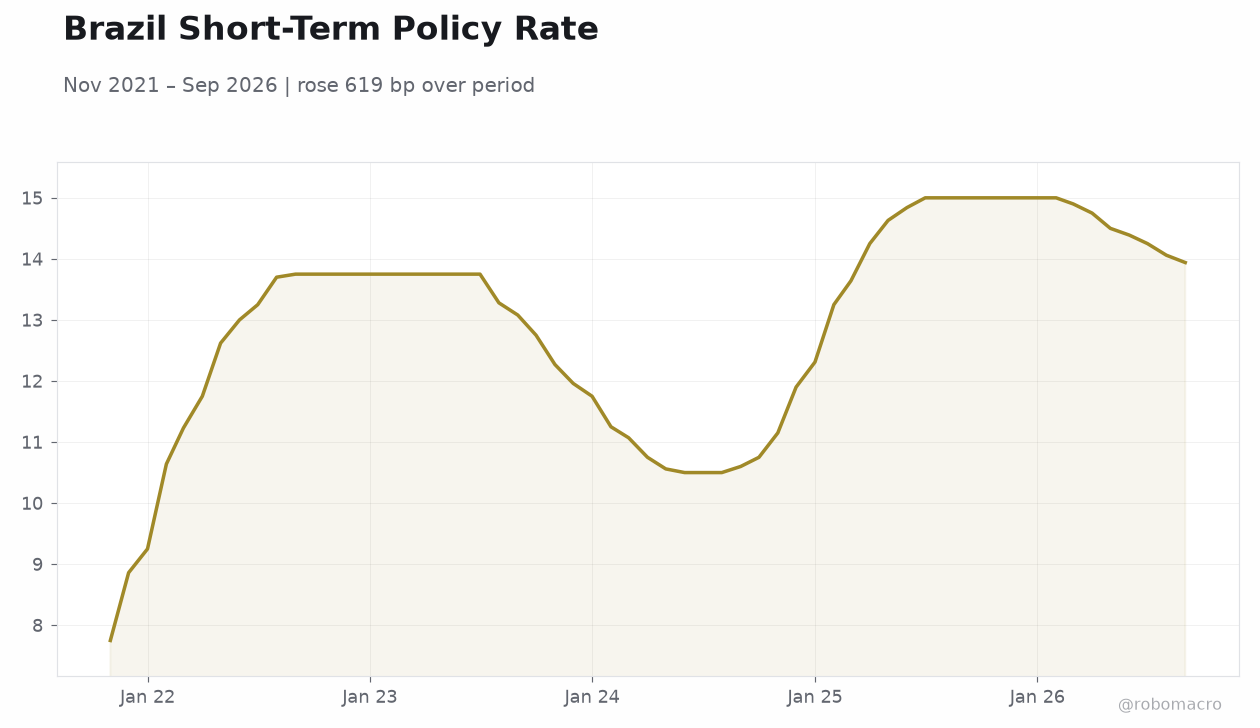 Brazil Short-Term Policy Rate | Type: macro_line | Rate %: 13.94 (2026-09-01) | Range: 7.75–15 | Trend(6pt): 7.75,13.75,11.07,14.63,14.25,13.94
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Bovespa drops 1.15% while 10-year yields climb 16 bp to 12.87% on fiscal concerns
- USD/BRL edges up 0.19% to 5.03 amid election uncertainty and reform calls
- Vale falls 3.94% as iron ore exposure weighs on sentiment
Yesterday's Recap
Brazilian assets closed weaker on October 22 as investors priced in heightened fiscal risks ahead of the presidential runoff. The Bovespa declined 1.15% to 204,120 while the 5-year government yield rose 14 bp to 12.79% and the 10-year yield increased 16 bp to 12.87%. USD/BRL advanced 0.19% to 5.03, reflecting modest depreciation pressure, whereas EUR/BRL eased 0.05%.
Vale shares dropped 3.94% to 12.20 on softer commodity sentiment, while Petrobras held nearly flat. WTI crude gained 0.84% to 100.31, offering limited support to energy names. No economic data prints occurred, leaving market moves driven by political headlines and global risk factors.
Gold eased 0.45% to 4,042.30 and Bitcoin rose 0.45% to 81,678.24, providing mixed external signals for local flows.
The Day Ahead
Markets will monitor campaign rhetoric on fiscal commitments through the weekend ahead of Sunday’s vote. Economists and business groups are pressing both candidates for credible 2027 budget anchors to support lower Selic levels over time. Attention will also turn to any fresh statements from the BCB on inflation dynamics given the September CPI print of 4.58%.
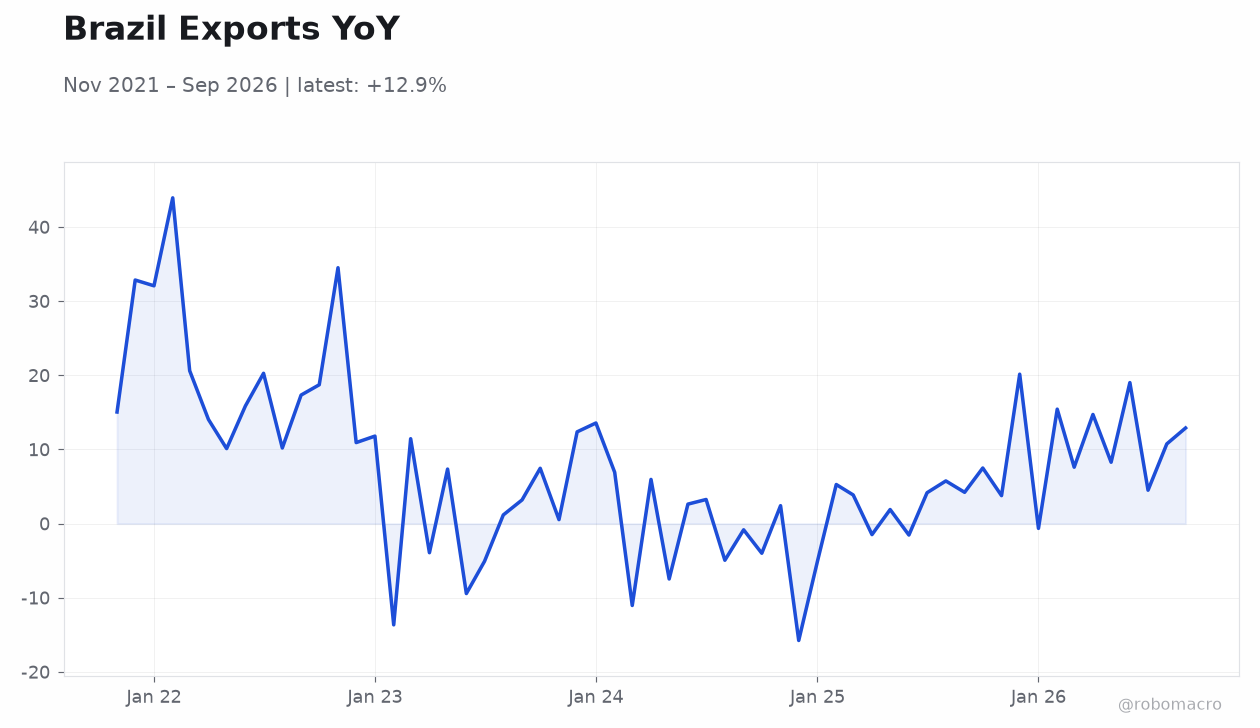
Commodity price swings remain relevant for export revenues, with iron ore and oil volatility likely to influence equity flows. Broader Latin American AI adoption trends offer a positive structural backdrop but are unlikely to shift near-term pricing. Regional developments in Chile and Uruguay alongside Brazil may reinforce longer-term productivity narratives without altering immediate positioning.
Other Economic Notes
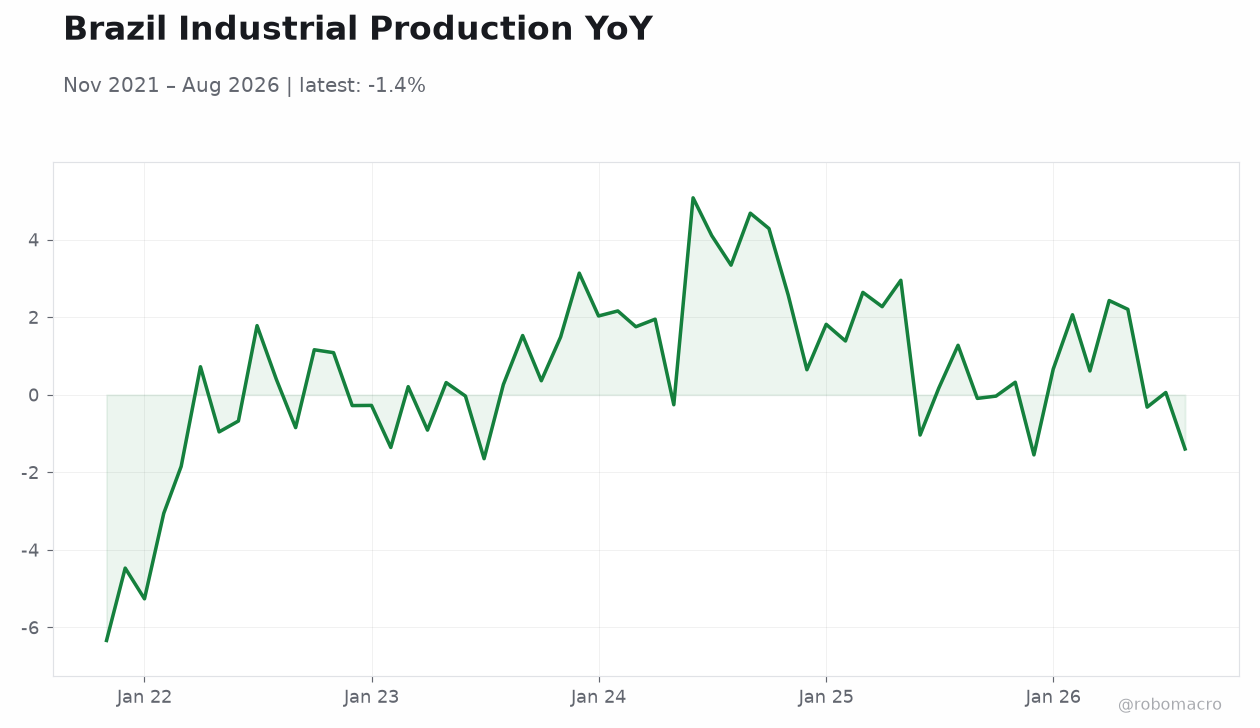
Brazil’s economy continues to face structurally weaker growth prospects unless fiscal discipline is restored. Analysts highlight the need for productivity-enhancing reforms in agriculture, labor markets, and public spending to sustain the current inflation-targeting framework. Pressure is mounting for a multi-year fiscal plan that could eventually ease the Selic burden from its current 13.75% level.
Without credible anchors, debt-service costs risk crowding out private investment and capping potential GDP expansion. Calls for a “Plano Real”-style approach to interest rates underscore the linkage between budget credibility and sustained disinflation.