Brazil Macro Daily(Beta Mode)
Brazilian Assets Slide as Political Risk Compounds
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Bovespa | 171,006.00 | -2.68% |
| USD/BRL | 5.34 | -0.12% |
| EUR/BRL | 5.96 | +0.07% |
| Vale | 11.47 | -3.12% |
| Petrobras | 22.03 | -1.21% |
| WTI Crude | 101.77 | -0.98% |
| Gold | 4,038.40 | -0.33% |
| Bitcoin | 79,779.09 | -1.83% |
| Brazil 5Y Govt Yield | 15.02% | -75 bp |
| Brazil 10Y Govt Yield | 14.93% | -49 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BCB Focus Market Readout | - | - | "" |
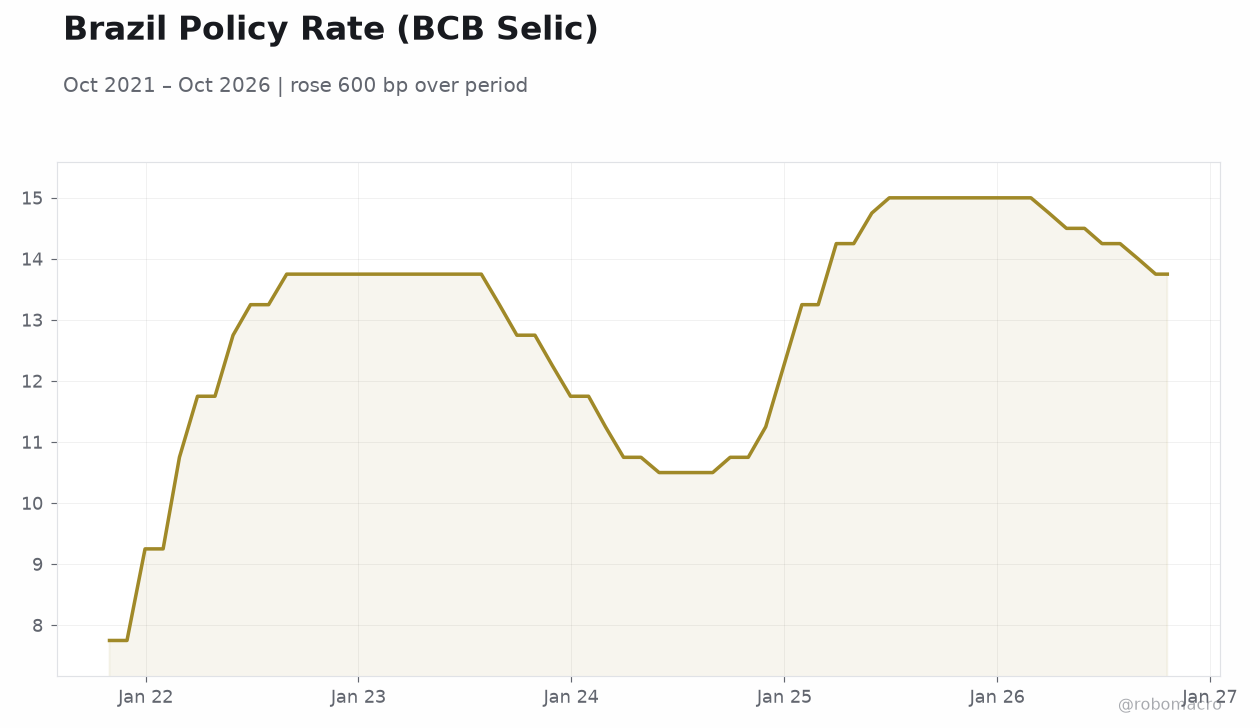 Brazil Policy Rate (BCB Selic) | Type: macro_line | Policy Rate (%): 13.75 (2026-10-20) | Range: 7.75–15 | Trend(5pt): 7.75,13.75,10.75,15,13.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Friday (2026-10-30) | |||
| Headline Unemployment Rate | 5.30 | 5.20 | 08:00 |
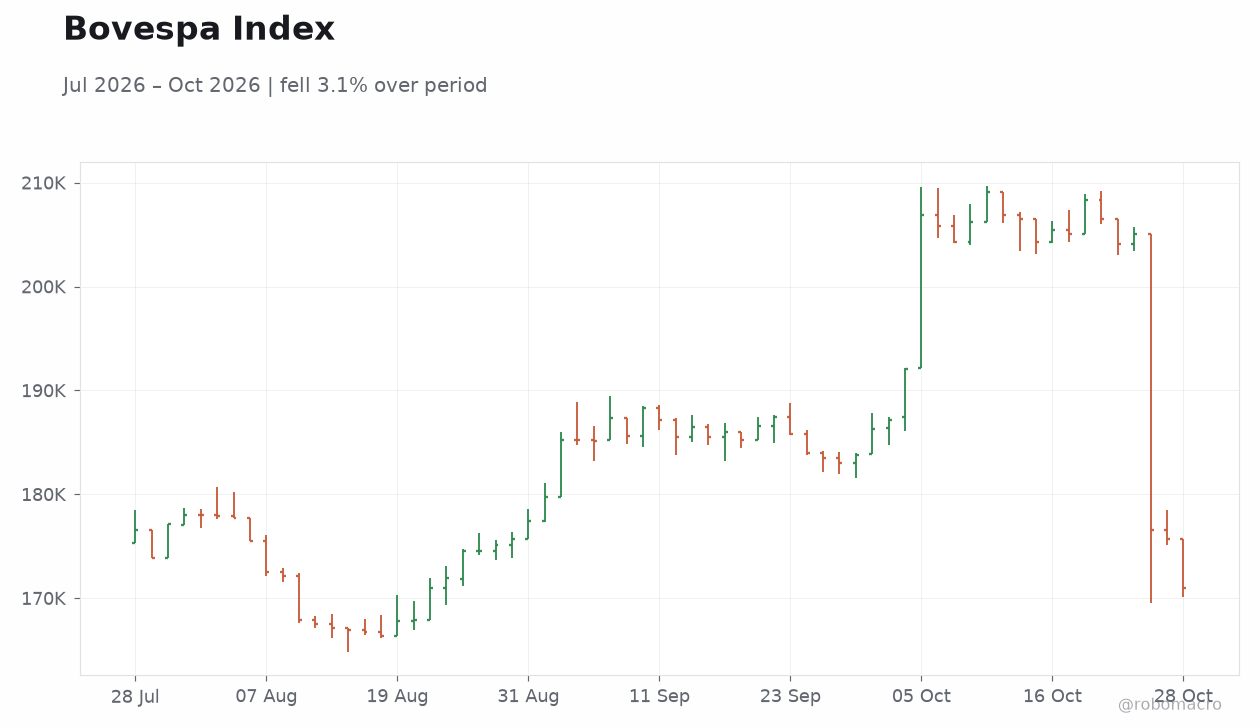
- Bovespa plunges 2.68% to 171,006 as Vale and Petrobras lead broad selloff amid post-election political turbulence
- Brazil 5Y and 10Y government yields compress sharply, falling 75bp and 49bp respectively to 15.02% and 14.93%
- USD/BRL edges down 0.12% to 5.34 while EUR/BRL ticks up 0.07% to 5.96; unemployment data due Friday
Yesterday's Recap
Brazilian equities suffered a sharp correction on October 28, with the Bovespa index tumbling 2.68% to close at 171,006 points. The selloff was led by commodity-linked names, as Vale dropped 3.12% to 11.47 and Petrobras declined 1.21% to 22.03, tracking softer iron ore sentiment and a 0.98% pullback in WTI crude to 101.77. Despite the equity rout, local fixed income rallied aggressively, with the 5-year government yield collapsing 75 basis points to 15.02% and the 10-year yield easing 49 basis points to 14.93%, suggesting investors rotated out of risk assets into duration.
Currency markets were comparatively stable, with USD/BRL slipping 0.12% to 5.34 while EUR/BRL firmed 0.07% to 5.96. The BCB Focus Market Readout released on October 26 provided no fresh directional catalyst, leaving markets to digest political headlines surrounding Flávio Bolsonaro's departure to Miami following the presidential election loss. Gold eased 0.33% to 4,038.40 and Bitcoin fell 1.83% to 79,779.09, reflecting a broader risk-off tone across global markets.
The Day Ahead
The calendar is light for Thursday, October 29, with no scheduled Brazilian data releases. Attention shifts to Friday, October 30, when the IBGE publishes the Headline Unemployment Rate at 08:00 ET. Consensus expects the unemployment rate to tick down to 5.2% from the prior 5.3% reading, which would reinforce the picture of a tight labor market.
A print at or below consensus would likely sustain pressure on the BCB to maintain its restrictive stance, particularly with services inflation remaining a concern. Markets will also continue monitoring political developments following the election, with cabinet transition announcements potentially influencing sentiment into the weekend.
Other Economic Notes
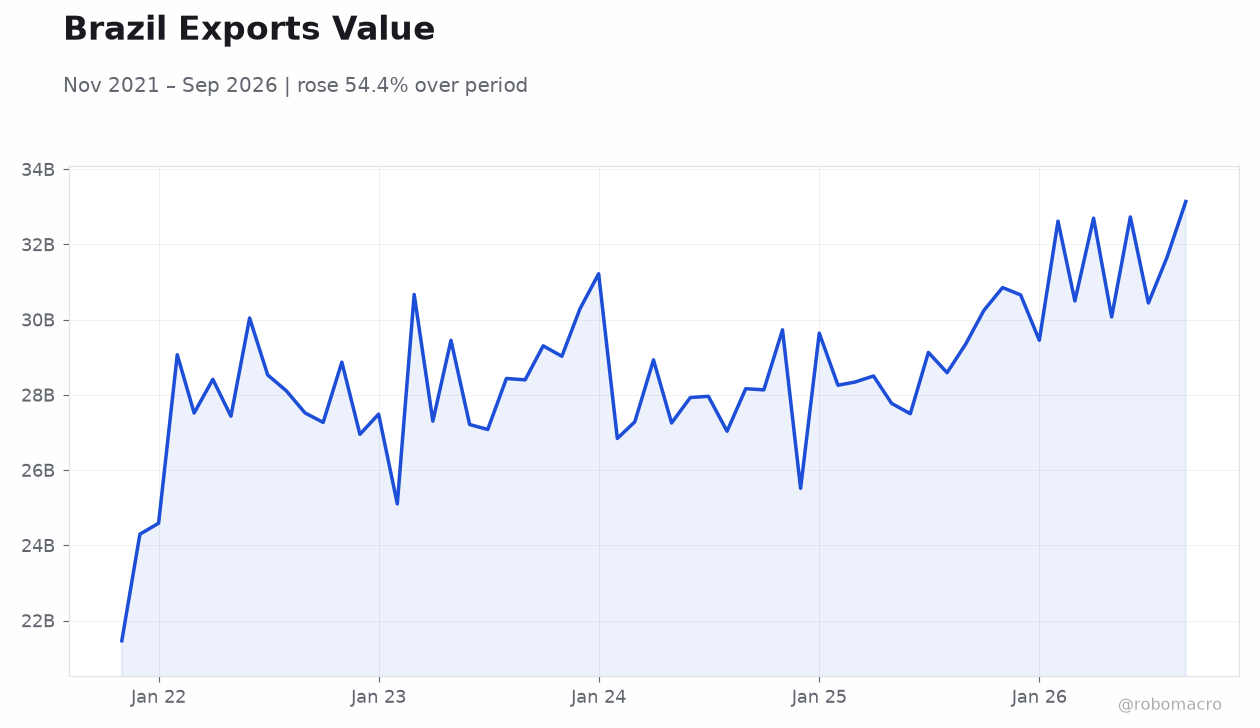
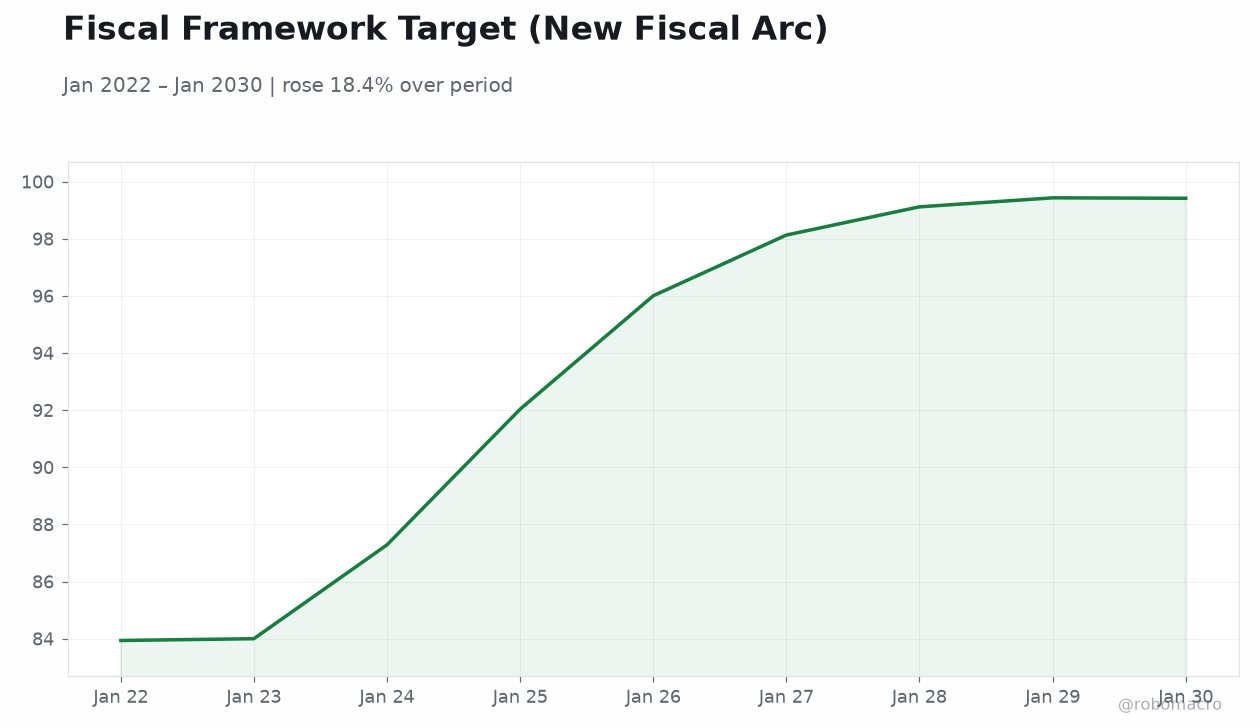
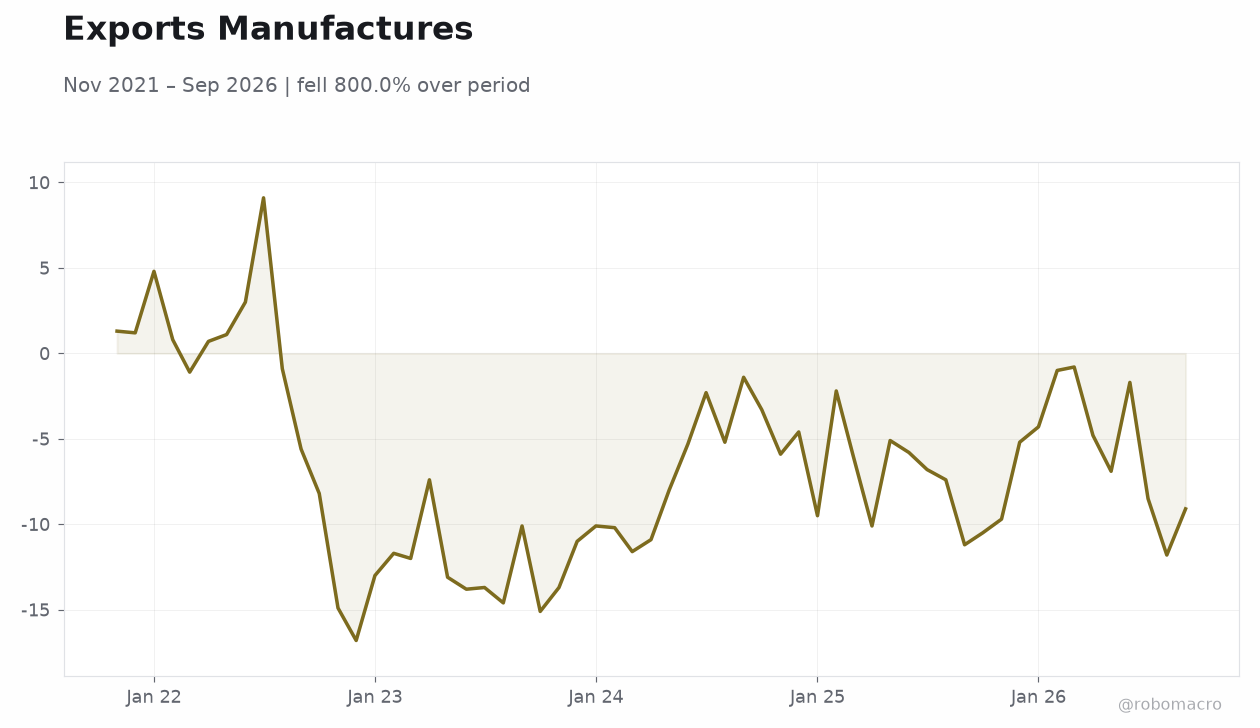
Brazil's fiscal trajectory remains the dominant medium-term concern for investors, with the incoming administration facing pressure to clarify spending priorities ahead of the 2027 budget cycle. The sharp rally in local yields despite equity weakness suggests the market is pricing a more benign inflation outlook, potentially front-running a BCB pivot in 2027. Commodity export dynamics remain mixed: soybean flows to China continue to displace US origins, supporting the agricultural trade surplus, while iron ore demand from Chinese steel producers shows signs of softening.
↓ p.2