Brazil Macro Daily(Beta Mode)
Real Slips, Yields Jump Ahead of COPOM
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Bovespa | 167,922.00 | -0.75% |
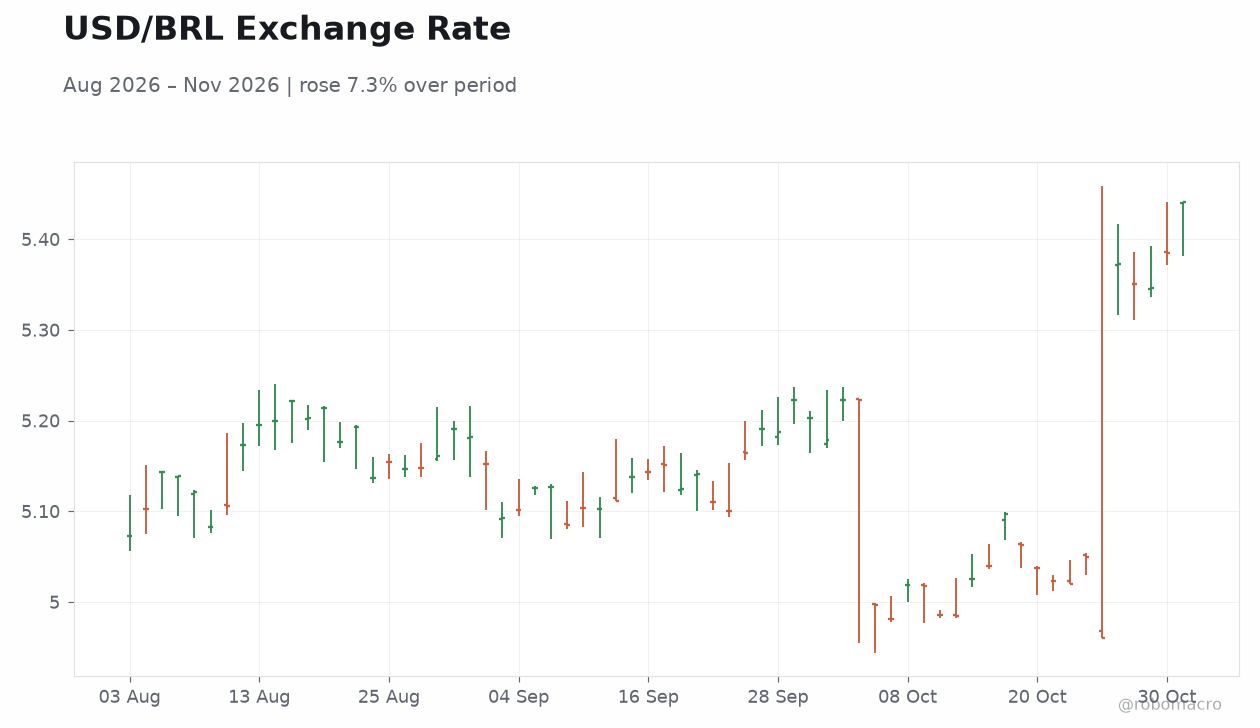
| USD/BRL | 5.44 | +1.04% |
| EUR/BRL | 6.10 | +1.39% |
| Vale | 11.39 | +1.88% |
| Petrobras | 22.05 | +0.68% |
| WTI Crude | 100.09 | -3.87% |
| Gold | 3,912.90 | +0.36% |
| Bitcoin | 78,191.00 | -0.07% |
| Brazil 5Y Govt Yield | 15.29% | +19 bp |
| Brazil 10Y Govt Yield | 15.23% | +23 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
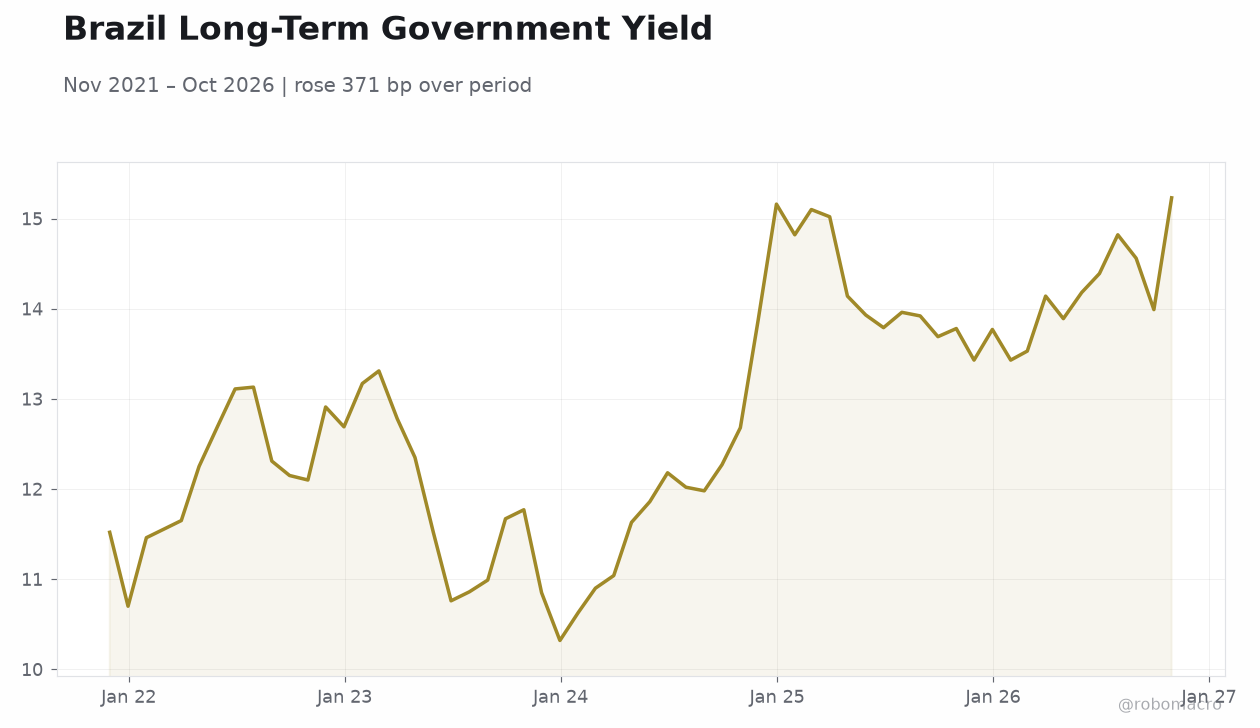 Brazil Long-Term Government Yield | Type: macro_line | 10Y Yield (%): 15.23 (2026-10-30) | Range: 10.32–15.23 | Trend(5pt): 11.52,13.31,11.86,13.92,15.23
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Tuesday (2026-11-03) | |||
| BCB Focus Market Readout | - | - | 06:30 |
| Wednesday (2026-11-04) | |||
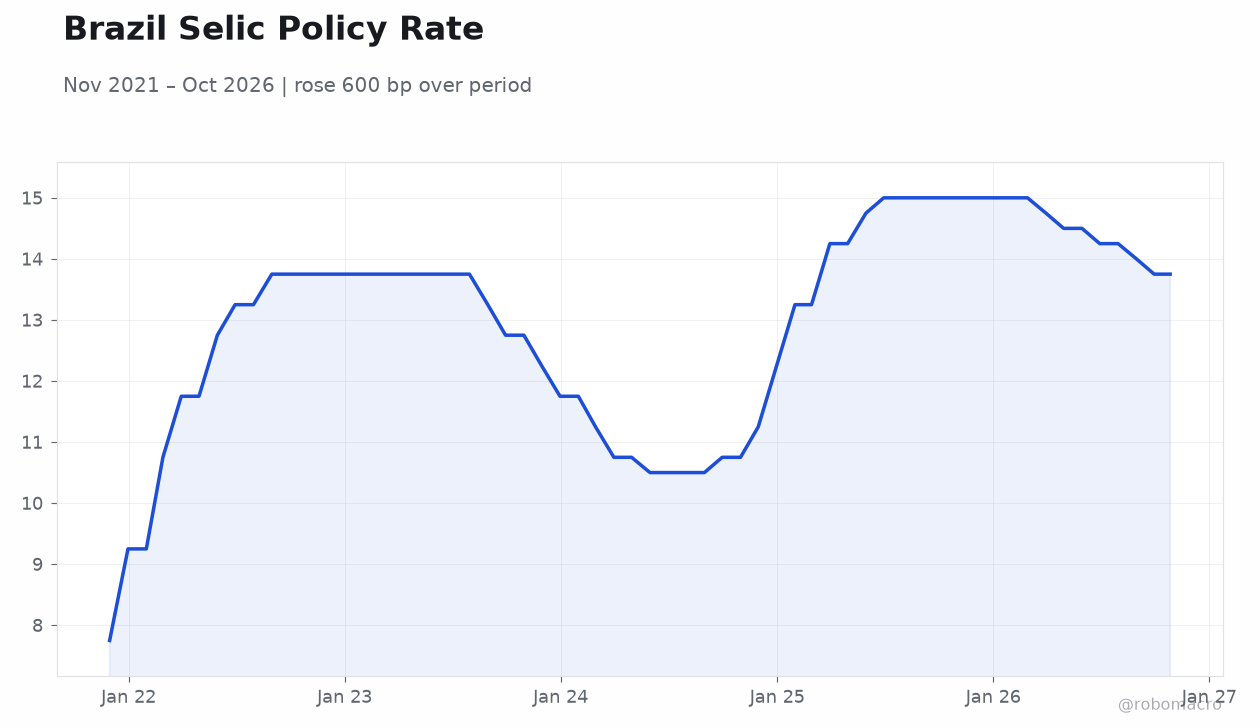
| Central Bank Interest Rate Decision | 13.75 | - | 16:30 |
| Thursday (2026-11-05) | |||
| Industrial Production Month-over-Month | -0.60 | - | 07:00 |
| S&P Global Services PMI | 49.20 | - | 08:00 |
| Friday (2026-11-06) | |||
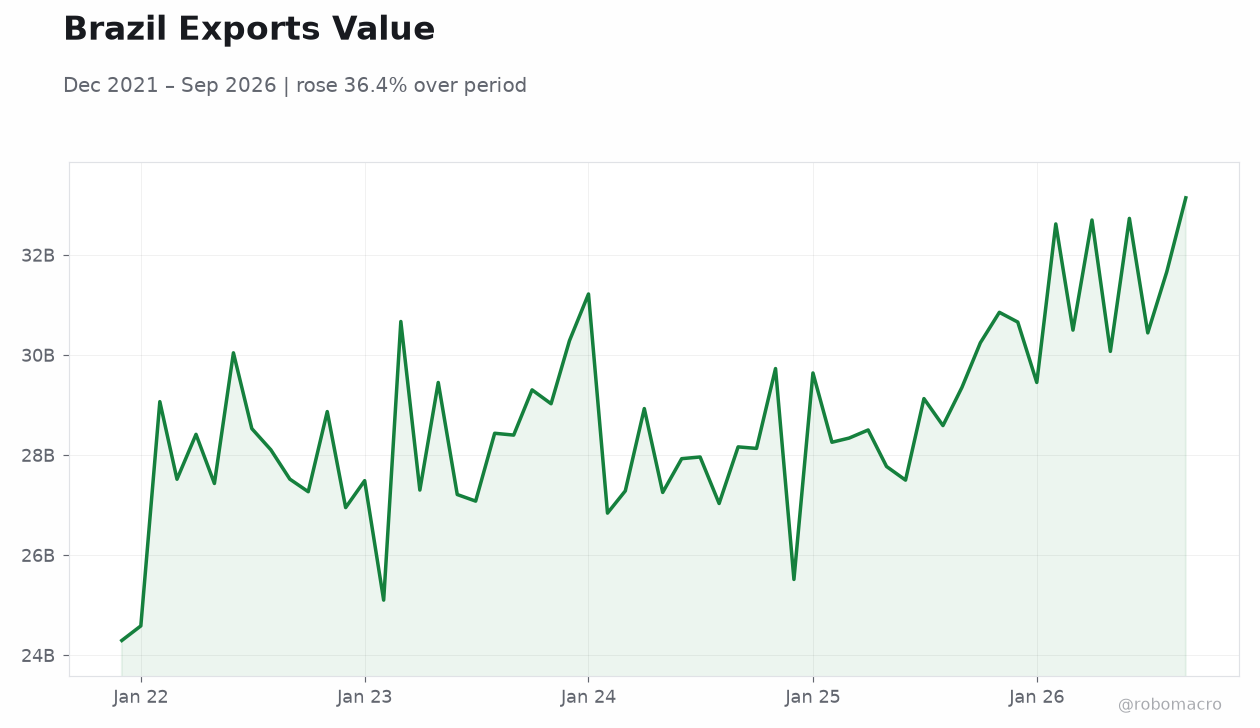
| Trade Balance | 7,740m | - | 13:00 |
- USD/BRL closed at 5.44 (+1.04%) as the real weakened broadly, with EUR/BRL at 6.10 (+1.39%), reflecting a risk-off tone in Brazilian assets.
- Brazil 10Y and 5Y government yields rose 23 bp and 19 bp to 15.23% and 15.29%, respectively, steepening the curve ahead of the COPOM decision.
- Bovespa fell 0.75% to 167,922 points, while Vale (+1.88%) and Petrobras (+0.68%) outperformed despite WTI crude dropping 3.87% to $100.09.
Yesterday's Recap
Brazilian markets opened the week on a risk-off footing, with the real depreciating over 1% against the dollar to 5.44 and the Bovespa shedding 0.75% to close at 167,922 points. The fixed-income market bore the brunt of the selloff, as the 10-year government yield jumped 23 bp to 15.23% and the 5-year yield rose 19 bp to 15.29%, steepening the curve and signaling heightened fiscal and monetary risk premia. Commodity-linked equities diverged from the broader index, with Vale gaining 1.88% and Petrobras adding 0.68%, even as WTI crude plunged 3.87% to $100.09.
Gold edged up 0.36% to $3,912.90, while Bitcoin was essentially flat at $78,191. The session reflected investor caution ahead of Wednesday's COPOM rate decision, with positioning skewed defensively amid lingering concerns over Brazil's fiscal trajectory and election-year spending pledges.
The Day Ahead
The week's marquee event is Wednesday's COPOM decision (16:30 ET), with the Selic currently at 13.75% following the September 16 hold. Tuesday's BCB Focus Market Readout (06:30 ET) will provide the latest consensus on inflation, growth, and the Selic path, offering a read on market expectations heading into the decision. Thursday brings Industrial Production month-over-month (07:00 ET), with the prior print at -0.6%, alongside the S&P Global Services PMI (08:00 ET), which previously registered 49.2 — still in contraction territory.
Friday's Trade Balance release (13:00 ET) follows a prior surplus of $7.74bn, a key gauge of external-sector resilience. Markets will parse each release for signals on the pace of disinflation and the durability of activity.
Other Economic Notes
Brazil's fiscal outlook is drawing renewed scrutiny, with election-year pledges potentially pushing the primary deficit toward 1% of GDP, complicating the debt trajectory. Oil revenue is projected to exceed budget forecasts by R$65bn, offering a modest fiscal buffer, though the windfall may be offset by higher spending commitments. ↓ p.2