Brazil Macro Daily(Beta Mode)
Petrobras Slump Weighs on Bovespa Ahead of COPOM
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Bovespa | 167,922.00 | -0.75% |
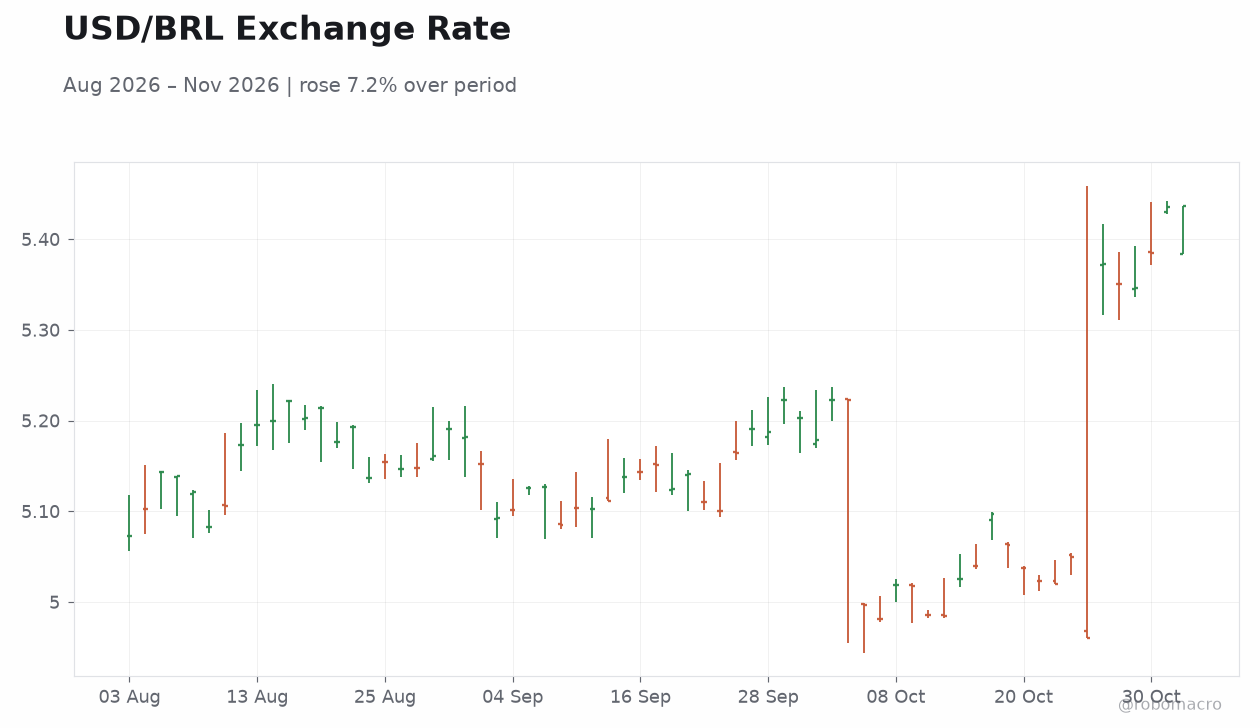
| USD/BRL | 5.44 | +0.03% |
| EUR/BRL | 6.08 | +0.26% |
| Vale | 11.34 | -0.44% |
| Petrobras | 21.16 | -4.04% |
| WTI Crude | 98.23 | +1.83% |
| Gold | 3,907.30 | -1.57% |
| Bitcoin | 76,541.90 | -0.18% |
| Brazil 5Y Govt Yield | 15.29% | +19 bp |
| Brazil 10Y Govt Yield | 15.23% | +23 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
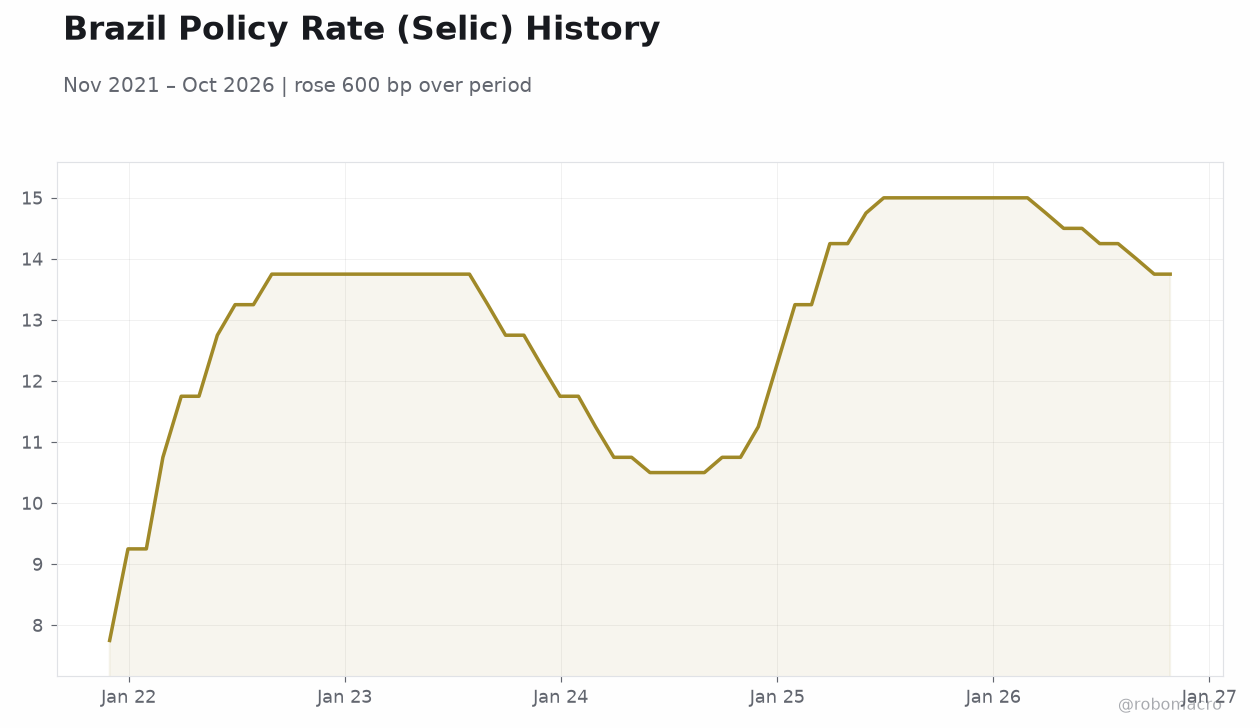 Brazil Policy Rate (Selic) History | Type: macro_line | Selic Rate (%): 13.75 (2026-10-27) | Range: 7.75–15 | Trend(5pt): 7.75,13.75,10.5,15,13.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BCB Focus Market Readout | - | - | 06:30 |
| Wednesday (2026-11-04) | |||
| Central Bank Interest Rate Decision | 13.75 | - | 16:30 |
| Thursday (2026-11-05) | |||
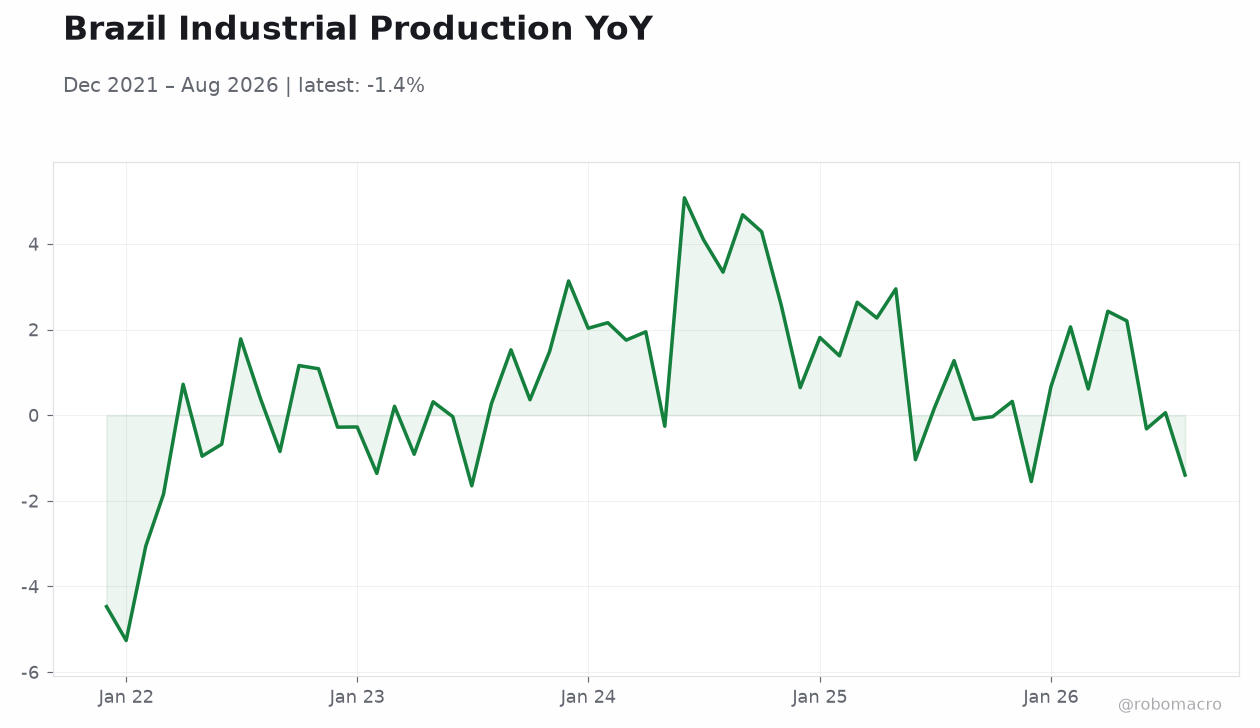
| Industrial Production Month-over-Month | -0.60 | - | 07:00 |
| S&P Global Services PMI | 49.20 | - | 08:00 |
| Friday (2026-11-06) | |||
| Trade Balance | 7,740m | - | 13:00 |
- Bovespa fell 0.75% to 167,922 as Petrobras dropped 4.04%, while the 10-year local yield widened 23 bp to 15.23%
- BCB Focus survey due today ahead of tomorrow's COPOM decision, with the Selic expected held at 13.75%
- Fiscal debate reignited as André Lara Resende's critique of BCB interest costs gains market attention
Yesterday's Recap
Brazilian assets came under broad pressure to open the week, with the Bovespa shedding 0.75% to close at 167,922 points. The selloff was led by Petrobras, which fell 4.04% to R$21.16, dragging the index despite WTI crude rising 1.83% to $98.23. Vale slipped 0.44% to R$11.34 as iron ore sentiment stayed soft.
The real was broadly stable, with USD/BRL at 5.44 (+0.03%) and EUR/BRL at 6.08 (+0.26%). The fixed-income market bore the brunt of the risk-off tone: the 5-year local yield rose 19 bp to 15.29% and the 10-year jumped 23 bp to 15.23%, steepening the curve and signaling rising term premium ahead of tomorrow's COPOM meeting. Gold fell 1.57% to $3,907.30, offering no safe-haven offset.
With no major Brazilian data prints on the calendar yesterday, positioning into the COPOM decision dominated flow.
The Day Ahead
The BCB Focus Market Readout at 06:30 ET leads today's calendar, with economists' median Selic, IPCA, and GDP forecasts closely watched for drift ahead of tomorrow's decision. Attention then pivots to Wednesday's Central Bank Interest Rate Decision at 16:30 ET, where the committee is widely expected to hold the Selic at 13.75%, the level set at the 2026-09-16 decision. Thursday brings industrial production month-over-month at 07:00 ET, with the prior print at -0.6%, alongside the S&P Global Services PMI at 08:00 ET, previously 49.2 — still in contraction territory.
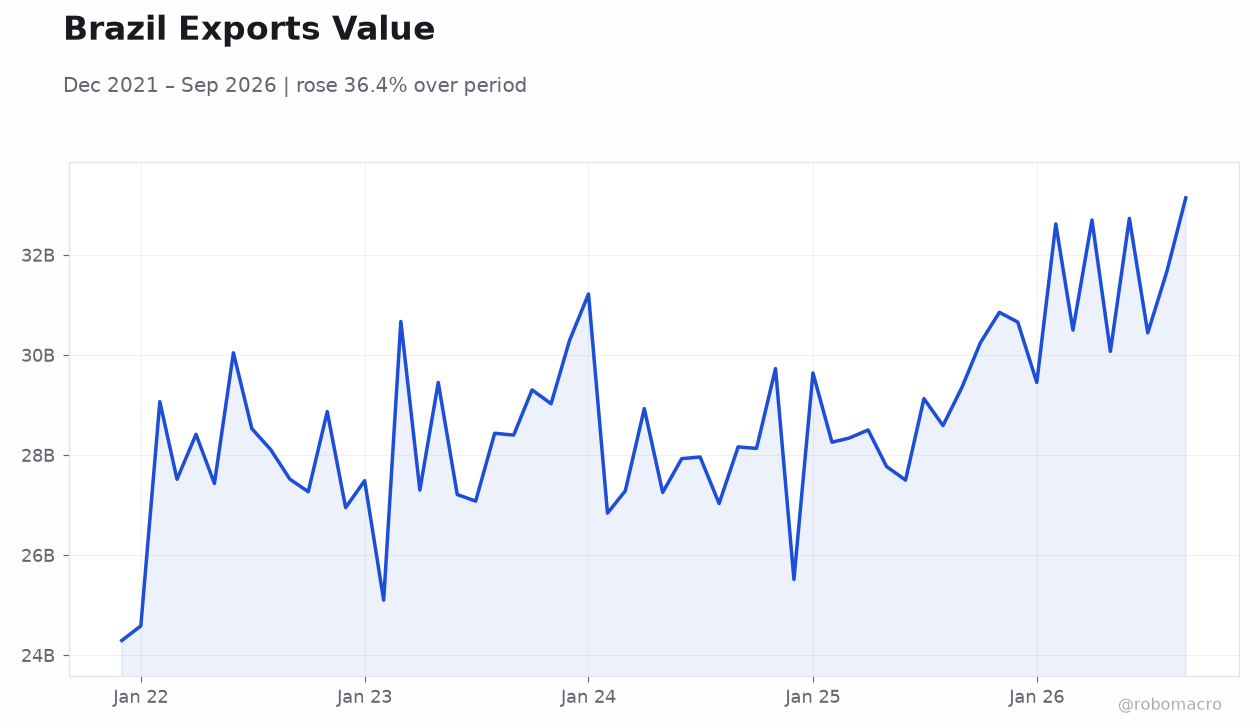
Friday's trade balance at 13:00 ET follows a prior surplus of $7.74 billion. Positioning into the COPOM decision will dominate today's flow.
Other Economic Notes
The fiscal narrative is reasserting itself in local markets. André Lara Resende, one of the architects of the Plano Real, has argued in a widely circulated article that the BCB's elevated interest burden is itself driving the fiscal deficit — a claim that has unsettled investors already sensitive to debt dynamics. The possible rapprochement between President Lula and Lara Resende has put the market on alert regarding the direction of economic policy.
↓ p.2