Brazil Macro Daily(Beta Mode)
Fiscal Package Meets Sticky Inflation
Market Snapshot
| Asset | Level | Change |
|---|---|---|
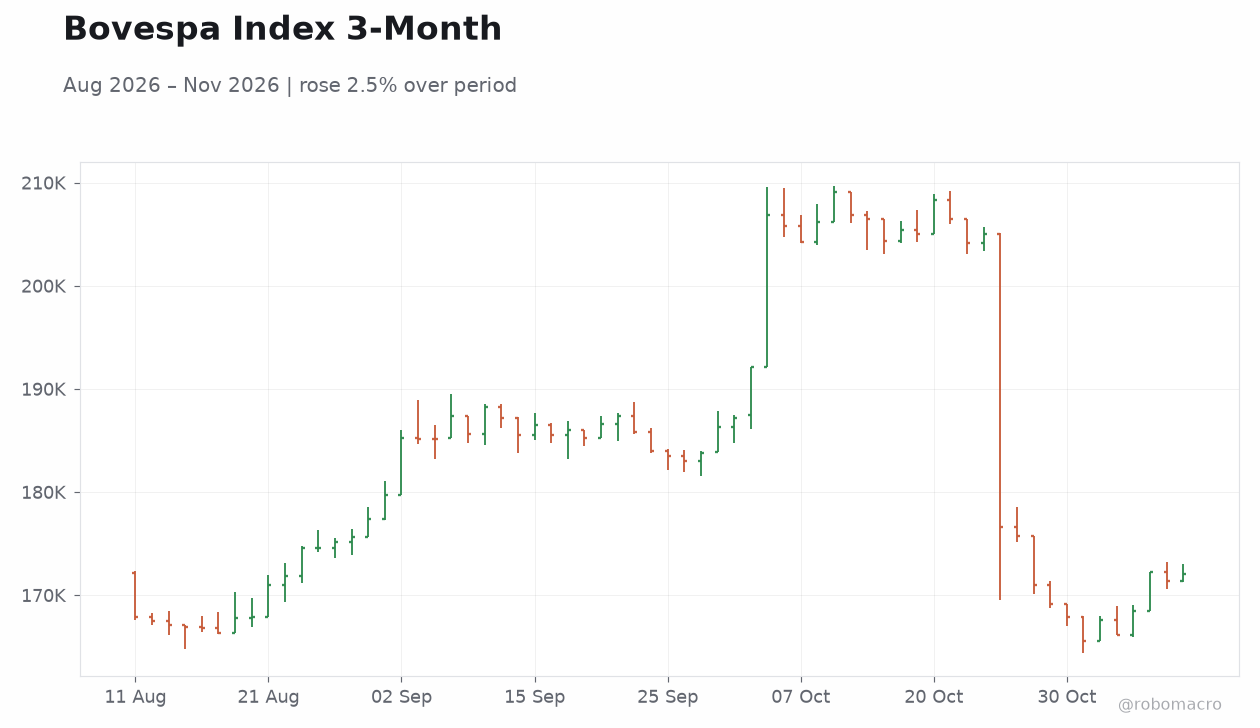
| Bovespa | 172,060.00 | +0.42% |
| USD/BRL | 5.58 | -0.01% |
| EUR/BRL | 6.19 | -0.62% |
| Vale | 11.58 | +0.00% |
| Petrobras | 17.82 | -2.52% |
| WTI Crude | 86.73 | +0.23% |
| Gold | 3,937.50 | -1.57% |
| Bitcoin | 73,360.59 | -0.82% |
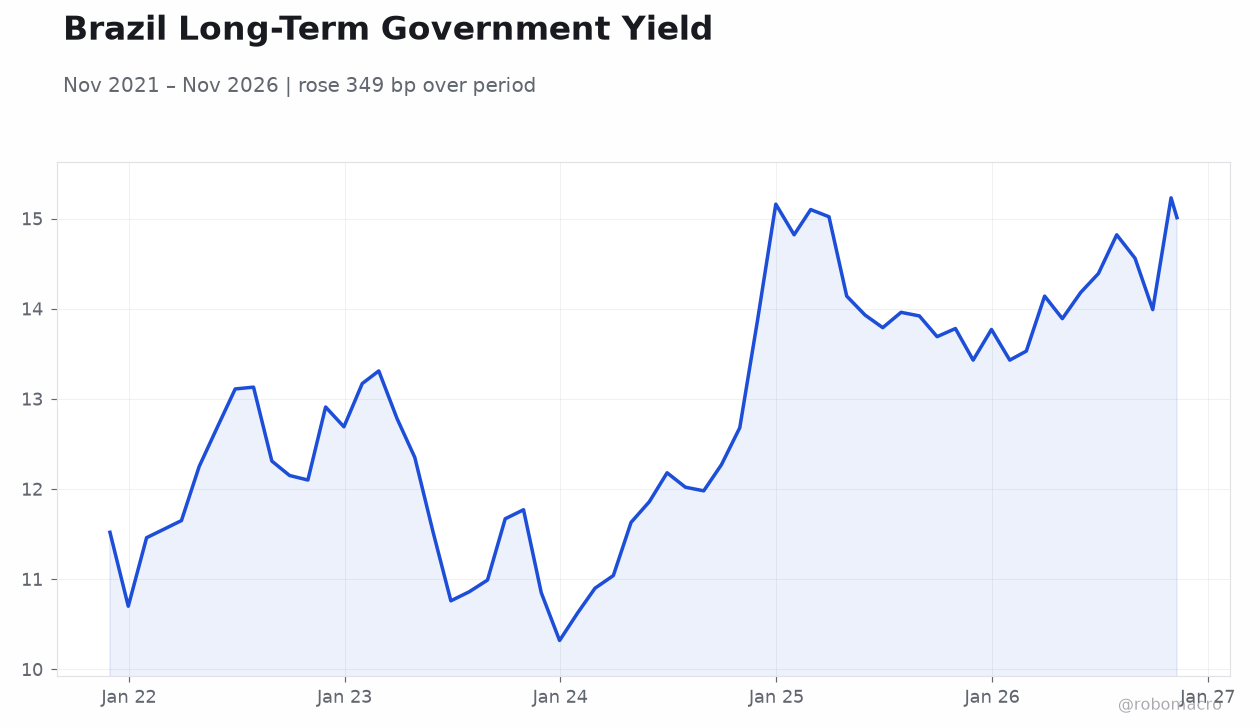
| Brazil 5Y Govt Yield | 14.96% | -3 bp |
| Brazil 10Y Govt Yield | 15.01% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BCB Focus Market Readout | - | - | "" |
| BCB Copom Meeting Minutes | - | - | - |
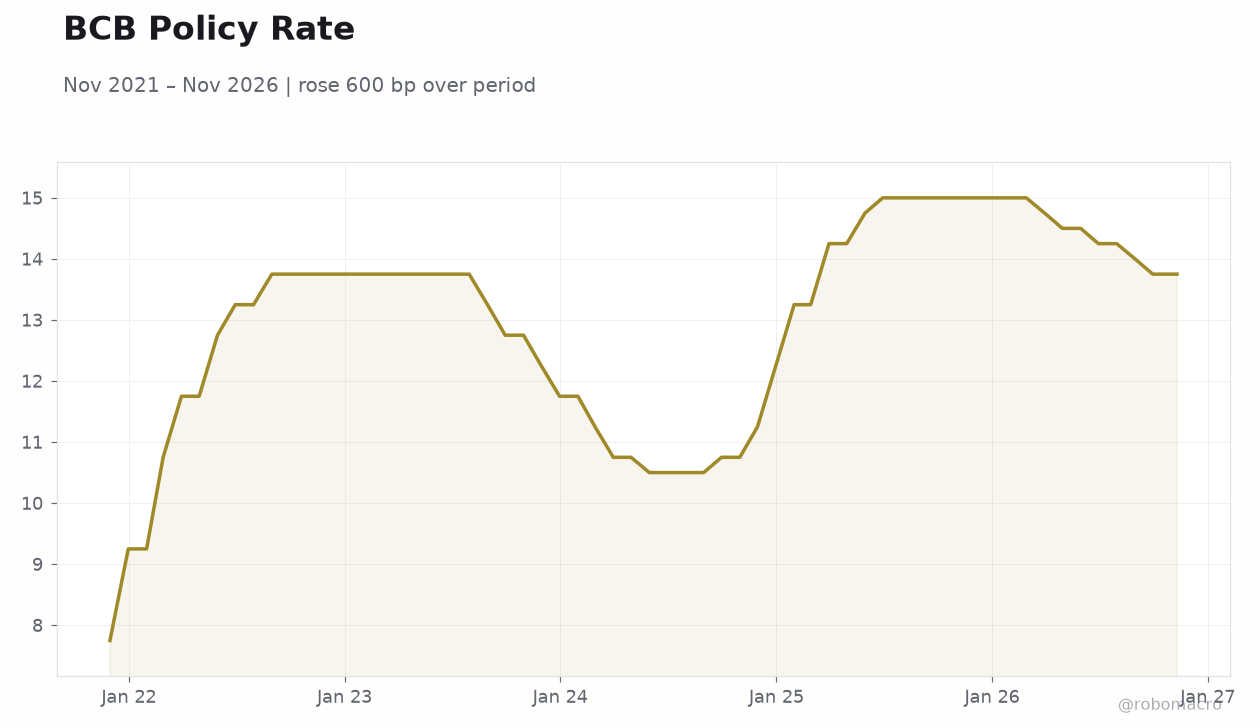 BCB Policy Rate | Type: macro_line | Policy Rate (%): 13.75 (2026-11-10) | Range: 7.75–15 | Trend(5pt): 7.75,13.75,10.5,15,13.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Inflation Rate Month-over-Month | 0.82 | 0.26 | 07:00 |
| Inflation Rate Year-over-Year | 4.58 | 4.74 | 07:00 |
| Friday (2026-11-13) | |||
| Retail Sales Month-over-Month | 0.10 | -0.20 | 07:00 |
| Business Confidence Index | 46.20 | - | 09:00 |
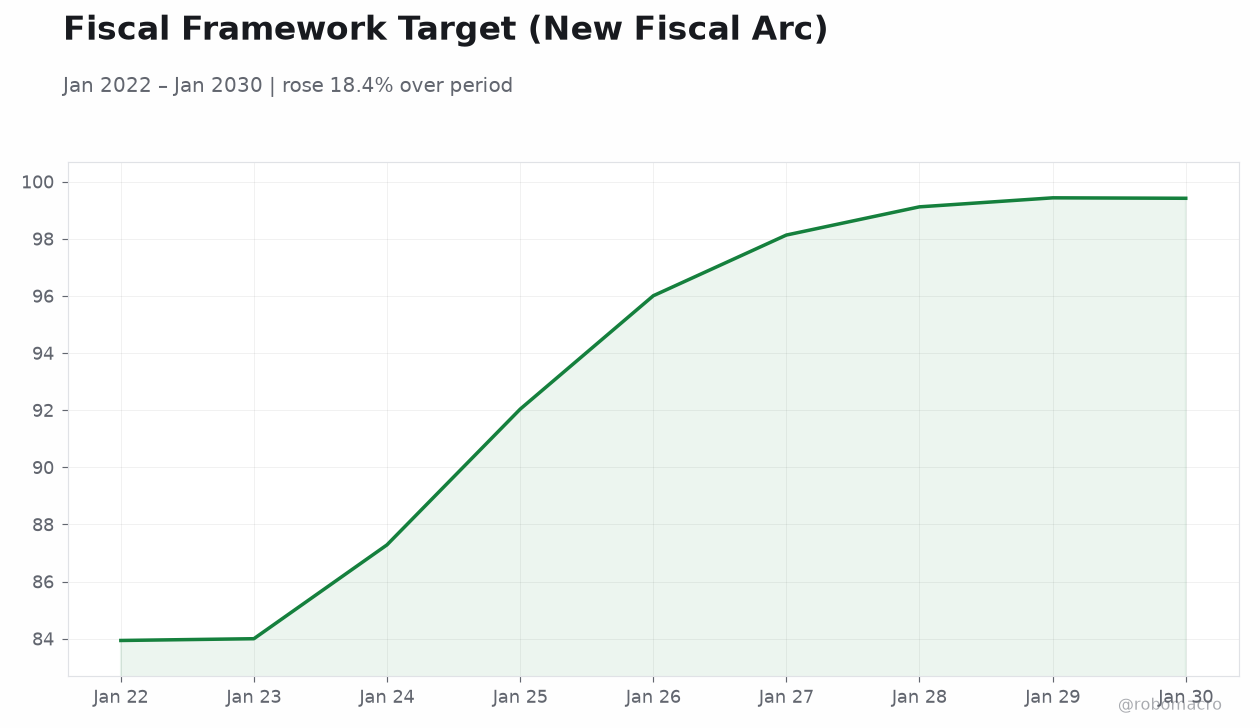
- Brazil unveils a fiscal package worth up to $10.8bn for next year, a headline positive for the fiscal trajectory but light on detail
- October IPCA consensus at 0.26% m/m and 4.74% y/y points to re-acceleration from the 4.58% September reading
- COPOM minutes and the Focus survey frame a BCB on hold at 13.75% with a hawkish bias after the September cut
Yesterday's Recap
The BCB published its Copom meeting minutes on 10 November, the key event of the week for rate expectations, and the Focus market readout landed on 9 November. Markets were mixed on 11 November: the Ibovespa firmed 0.42% to 172,060 while Petrobras fell 2.52% to 17.82 despite reporting third-quarter net income of R$39.75bn, and Vale was flat at 11.58. USD/BRL held at 5.58, down 0.01%, and EUR/BRL slipped 0.62% to 6.19.
The curve steepened modestly, with the 5-year yield down 3 bp to 14.96% and the 10-year up 1 bp to 15.01%. WTI edged up 0.23% to $86.73, gold dropped 1.57% to $3,937.50 and Bitcoin eased 0.82% to 73,360.59. Santander raised its buyout offer for minority holders of its Brazilian unit by 5%.
The Day Ahead
October IPCA prints at 07:00 ET, with consensus at 0.26% m/m and 4.74% y/y against 0.82% and 4.58% previously; the y/y step-up would mark a fresh acceleration and is the single most important input for the December COPOM decision. Friday brings October retail sales at 07:00 ET, where consensus is -0.2% m/m after 0.1% prior, and the November business confidence index at 09:00 ET from a 46.2 prior. A soft retail print alongside sticky inflation would reinforce the stagflation-lite narrative now embedded in the curve.
Watch the 10-year around 15.01% for the market's read on the fiscal package and the IPCA surprise.
Other Economic Notes
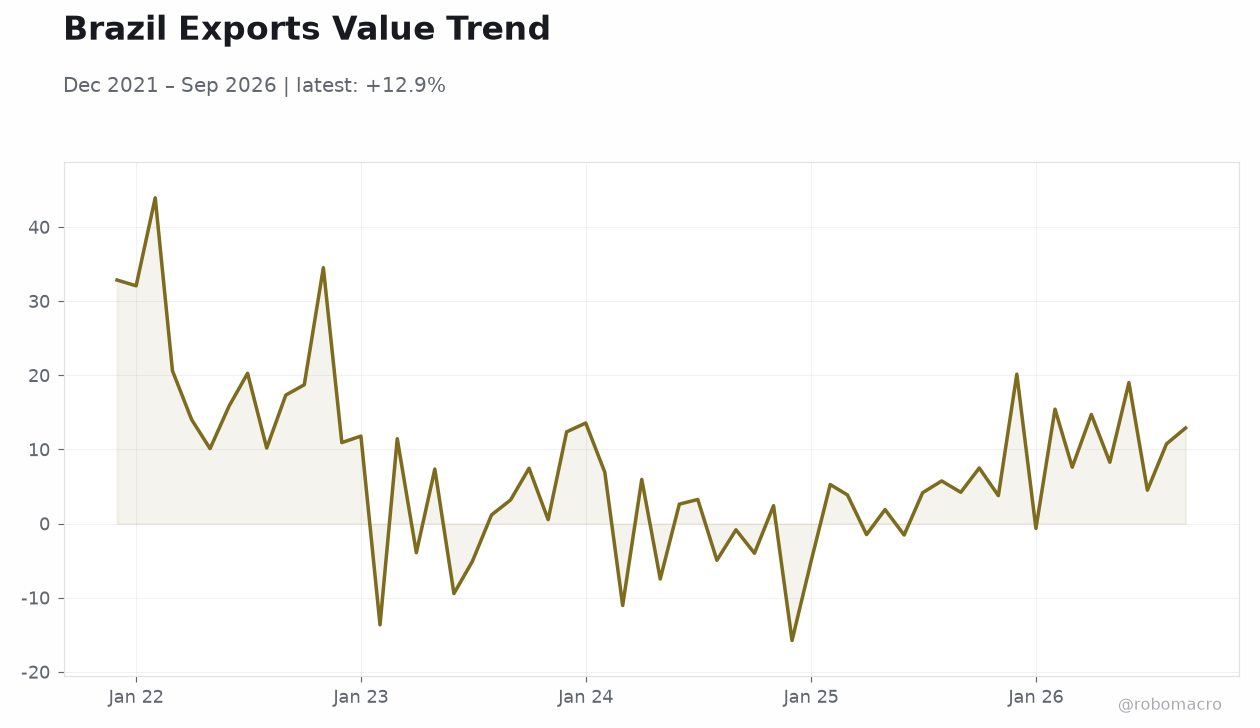
The fiscal package of up to $10.8bn for next year is the central swing factor for the 2027 primary balance and the credibility of the fiscal framework, but the market will want to see whether the measures are permanent revenue or one-offs. Real rates remain deeply restrictive with the Selic at 13.75% and the 10-year near 15%, a combination that historically pressures credit-sensitive sectors and retail. Petrobras' R$39.75bn quarterly profit and its platform capacity expansion without new investment underline the commodity export engine's cash generation, though the stock's 2.52% drop suggests dividend or capex disappointment.
Retail sales at -0.2% consensus would confirm the transmission of tight financial conditions into household demand.