Brazil Macro Daily(Beta Mode)
Inflation Surprise, Real Weakens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Bovespa | 171,324.00 | -0.43% |
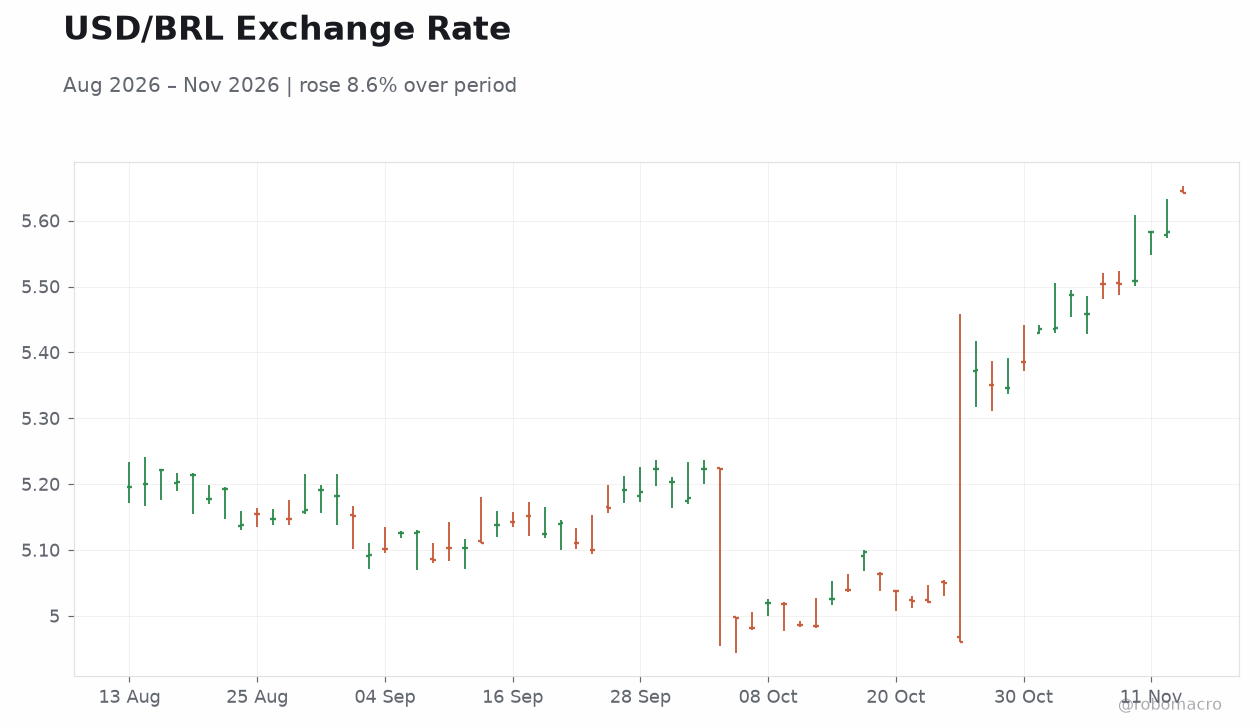
| USD/BRL | 5.64 | +1.07% |
| EUR/BRL | 6.24 | +0.81% |
| Vale | 11.28 | -2.59% |
| Petrobras | 18.10 | +1.57% |
| WTI Crude | 88.96 | +0.25% |
| Gold | 3,901.30 | +0.41% |
| Bitcoin | 68,663.10 | -3.76% |
| Brazil 5Y Govt Yield | 15.01% | +5 bp |
| Brazil 10Y Govt Yield | 15.05% | +4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BCB Focus Market Readout | - | - | "" |
| BCB Copom Meeting Minutes | - | - | - |
| Inflation Rate Month-over-Month | 0.82 | 0.26 | 0.14 |
| Inflation Rate Year-over-Year | 4.58 | 4.74 | 4.63 |
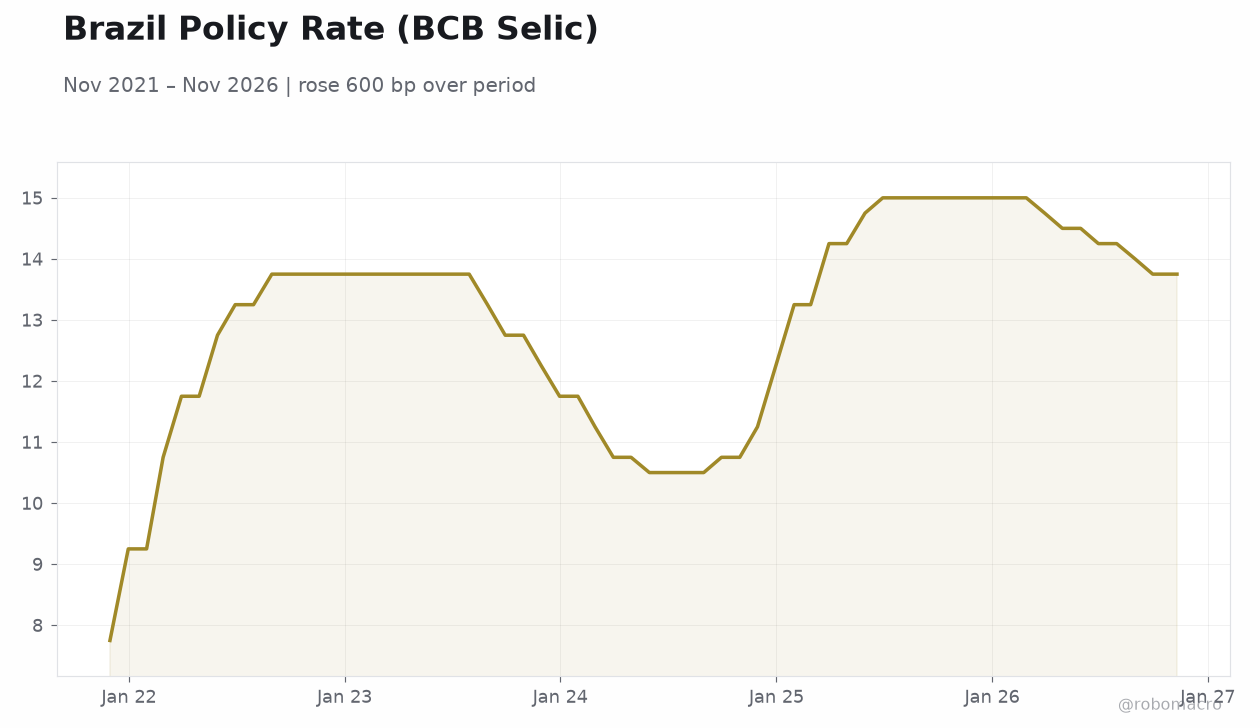 Brazil Policy Rate (BCB Selic) | Type: macro_line | Selic (%): 13.75 (2026-11-10) | Range: 7.75–15 | Trend(5pt): 7.75,13.75,10.5,15,13.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Retail Sales Month-over-Month | 0.10 | -0.20 | 07:00 |
| Business Confidence Index | 46.20 | - | 09:00 |
- October IPCA came in at 0.14% m/m and 4.63% y/y, well below the 0.26% consensus and the prior 0.82% print, a sharp disinflation surprise.
- USD/BRL jumped 1.07% to 5.64 while the Bovespa slipped 0.43% to 171,324; the 10-year yield rose 4 bp to 15.05%.
- October retail sales are due today at 07:00 ET with consensus at -0.2% m/m, alongside the Business Confidence Index at 09:00 ET.
Yesterday's Recap
October CPI printed at 0.14% m/m versus a 0.26% consensus and 0.82% prior, with the y/y rate at 4.63% against a 4.74% consensus and 4.58% prior — a meaningful downside surprise on both measures. The BCB Focus Market Readout was released on November 9 and the Copom meeting minutes on November 10, both feeding into the disinflation narrative. Despite the soft inflation print, the real weakened sharply, with USD/BRL up 1.07% to 5.64 and EUR/BRL up 0.81% to 6.24.
The Bovespa fell 0.43% to 171,324, with Vale down 2.59% to 11.28 while Petrobras gained 1.57% to 18.10. The 5-year yield rose 5 bp to 15.01% and the 10-year added 4 bp to 15.05%, suggesting the market read the CPI surprise as insufficient to shift the BCB's cautious stance. WTI crude edged up 0.25% to 88.96 and gold rose 0.41% to 3,901.30, while Bitcoin dropped 3.76% to 68,663.10.
The Day Ahead
October retail sales are scheduled for 07:00 ET with consensus at -0.2% m/m following a 0.1% prior, a key read on household demand after the disinflation surprise. The Business Confidence Index is due at 09:00 ET, with the prior at 46.2 — a level still in contractionary territory. No Brazilian releases are scheduled for November 14, so today's prints will set the tone into the weekend.
Markets will watch whether weak retail activity reinforces the disinflation case and supports the front end of the curve. With the next Copom meeting on December 9, today's data carries weight for the forward guidance debate.
Other Economic Notes
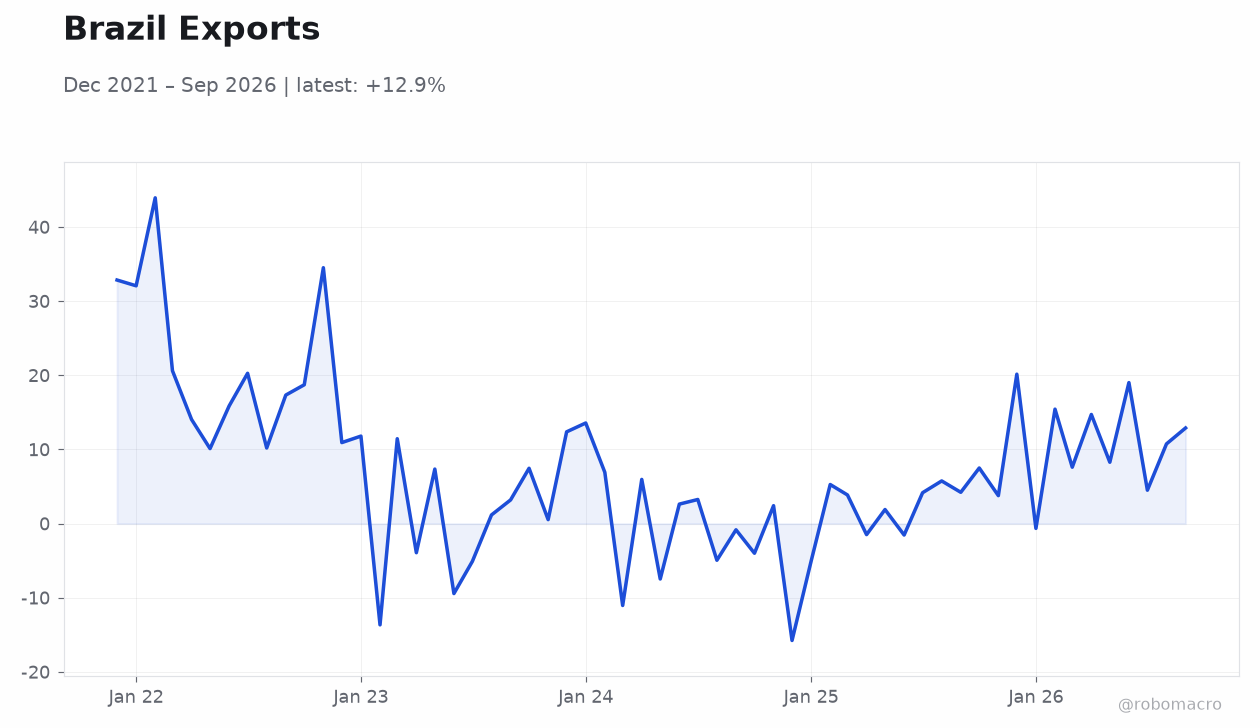
Brazil's farm economy weakness is spilling into corporate earnings, with Corteva shares hit by soft agricultural conditions — a reminder that the agribusiness cycle remains a drag on activity. Santander raised its offer for minority shareholders of its Brazilian unit by 5%, signaling continued confidence in the local franchise despite elevated rates. Asian oil buyers are increasingly turning to Brazilian grades as tanker rates plunge, a supportive signal for export volumes.
Global Macro News
The rupiah has become Asia's worst-performing currency, hitting record lows and forcing Bank Indonesia to intervene, a reminder that EM FX stress is broad-based and can spill into BRL sentiment. ↓ p.2