Brazil Macro Daily(Beta Mode)
Yields Spike as Fiscal Fears Mount
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Bovespa | 172,458.00 | +0.66% |
| USD/BRL | 5.67 | +0.46% |
| EUR/BRL | 6.25 | +0.30% |
| Vale | 11.22 | -0.53% |
| Petrobras | 18.34 | +1.33% |
| WTI Crude | 88.21 | -0.40% |
| Gold | 3,865.10 | -0.55% |
| Bitcoin | 64,297.30 | -1.54% |
| Brazil 5Y Govt Yield | 15.20% | +17 bp |
| Brazil 10Y Govt Yield | 15.30% | +21 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
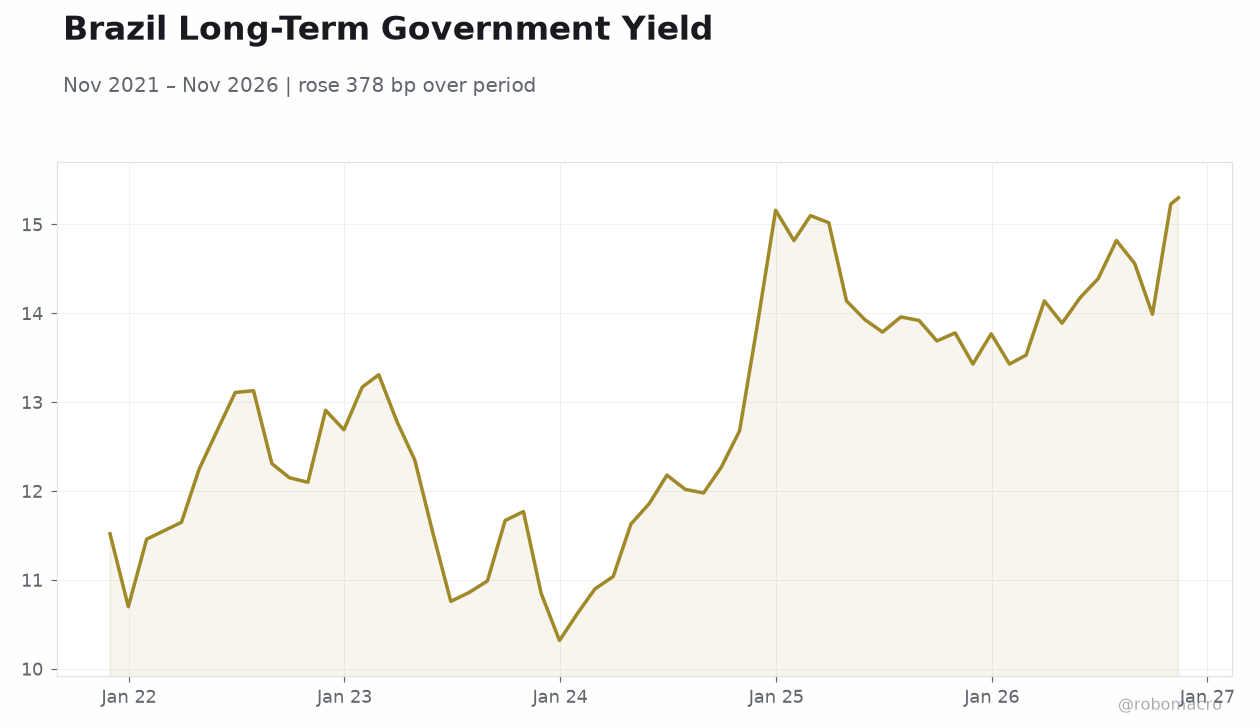 Brazil Long-Term Government Yield | Type: macro_line | 10Y Yield (%): 15.3 (2026-11-13) | Range: 10.32–15.3 | Trend(5pt): 11.52,13.31,11.86,13.92,15.3
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BCB Focus Market Readout | - | - | 06:30 |
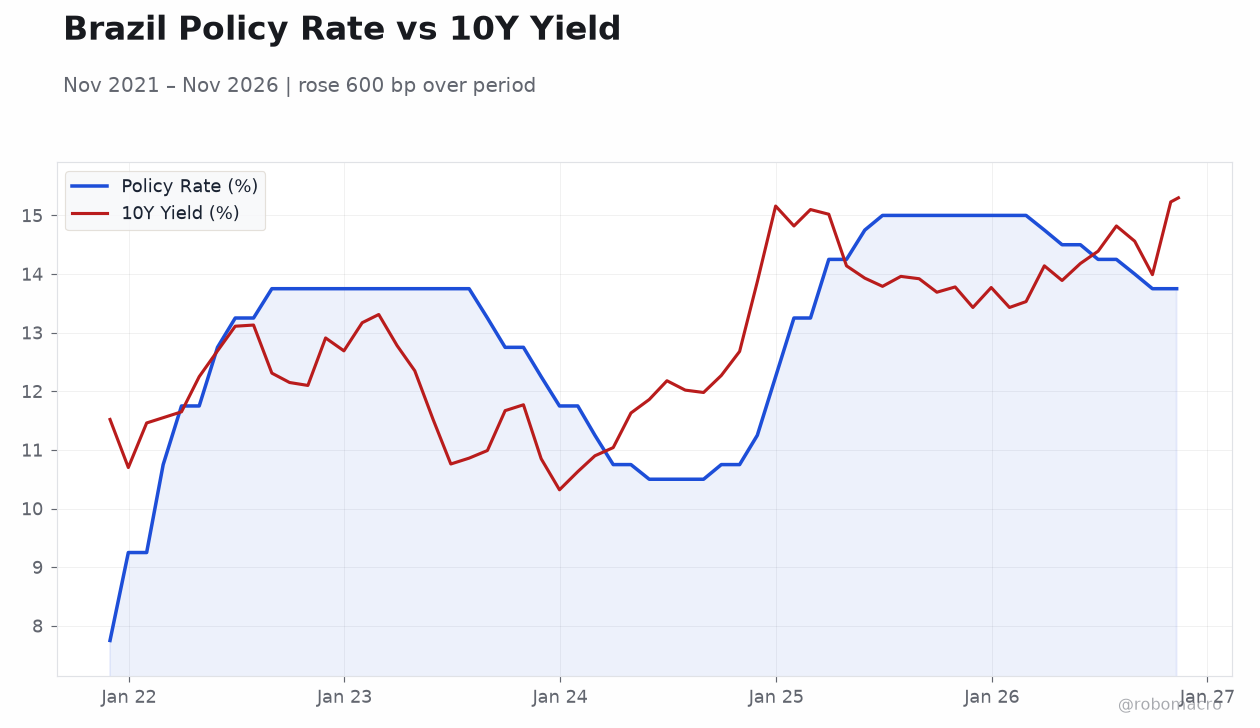
- Brazilian curve steepened sharply, with 10Y yields up 21 bp to 15.30% and 5Y up 17 bp to 15.20%, as fiscal credibility concerns dominate
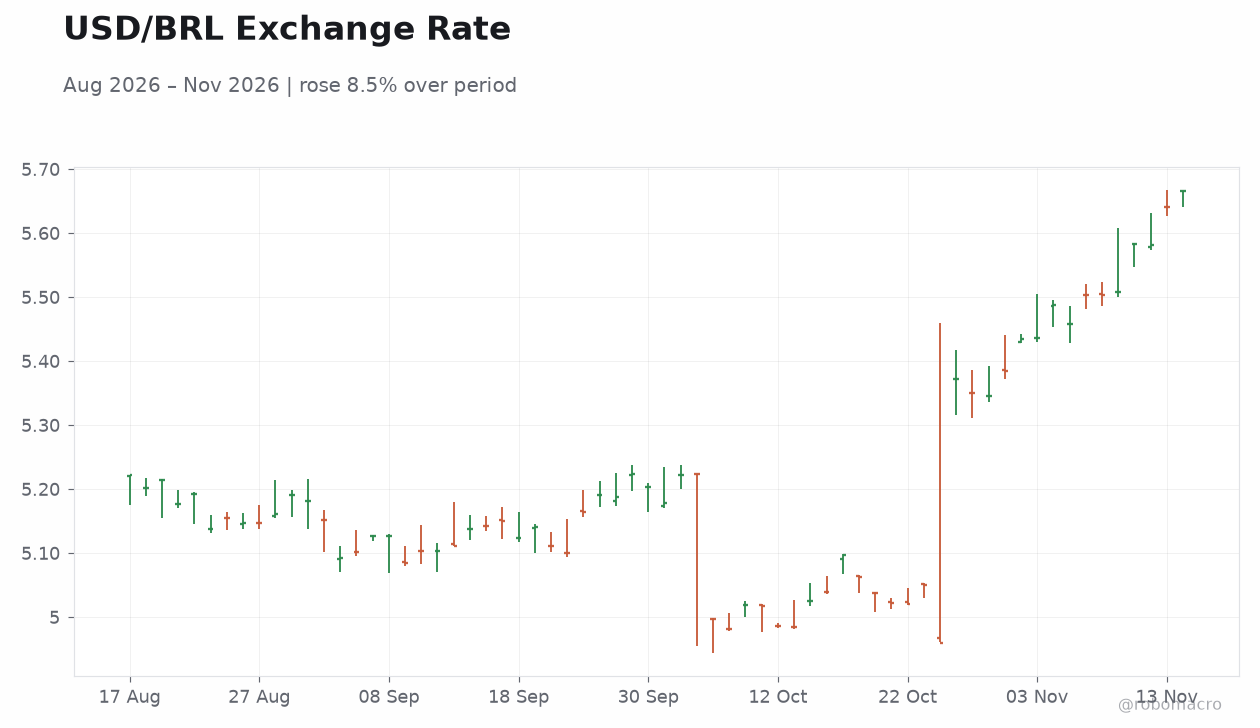
- USD/BRL weakened 0.46% to 5.67 despite Bovespa gaining 0.66%, reflecting persistent risk premium
- BCB Focus survey due today; market watches for inflation expectations drift against 4.63% CPI backdrop
Yesterday's Recap
Brazilian markets diverged on November 15, with equities grinding higher while the currency and rates told a more cautious story. The Bovespa added 0.66% to close at 172,458, supported by Petrobras strength (+1.33%) even as Vale slipped 0.53% on softer iron ore sentiment. The real weakened 0.46% to 5.67 against the dollar, and the EUR/BRL cross rose 0.30% to 6.25.
The fixed-income market delivered the clearest signal: the 10-year government yield jumped 21 bp to 15.30% and the 5-year rose 17 bp to 15.20%, extending a steepening trend that reflects mounting fiscal risk premium. WTI crude eased 0.40% to $88.21, while gold fell 0.55% to $3,865.10 and Bitcoin dropped 1.54% to $64,297.30. No official Brazilian data releases were scheduled for the session.
The Day Ahead
The sole scheduled Brazilian event today is the BCB Focus Market Readout at 06:30 ET, the central bank's weekly survey of private-sector economists' expectations for inflation, GDP, and the Selic path. With CPI running at 4.63% year-over-year as of October 31, the survey will be scrutinized for any upward drift in 2027 inflation projections that could complicate the BCB's easing bias. Traders will also watch whether Focus respondents revise their Selic forecasts following the November 4 hold at 13.75%.
No other Brazilian releases are scheduled for today or tomorrow, leaving the Focus survey as the primary domestic catalyst. Attention will otherwise remain on fiscal headlines and the currency's reaction to the elevated rate environment.
Other Economic Notes
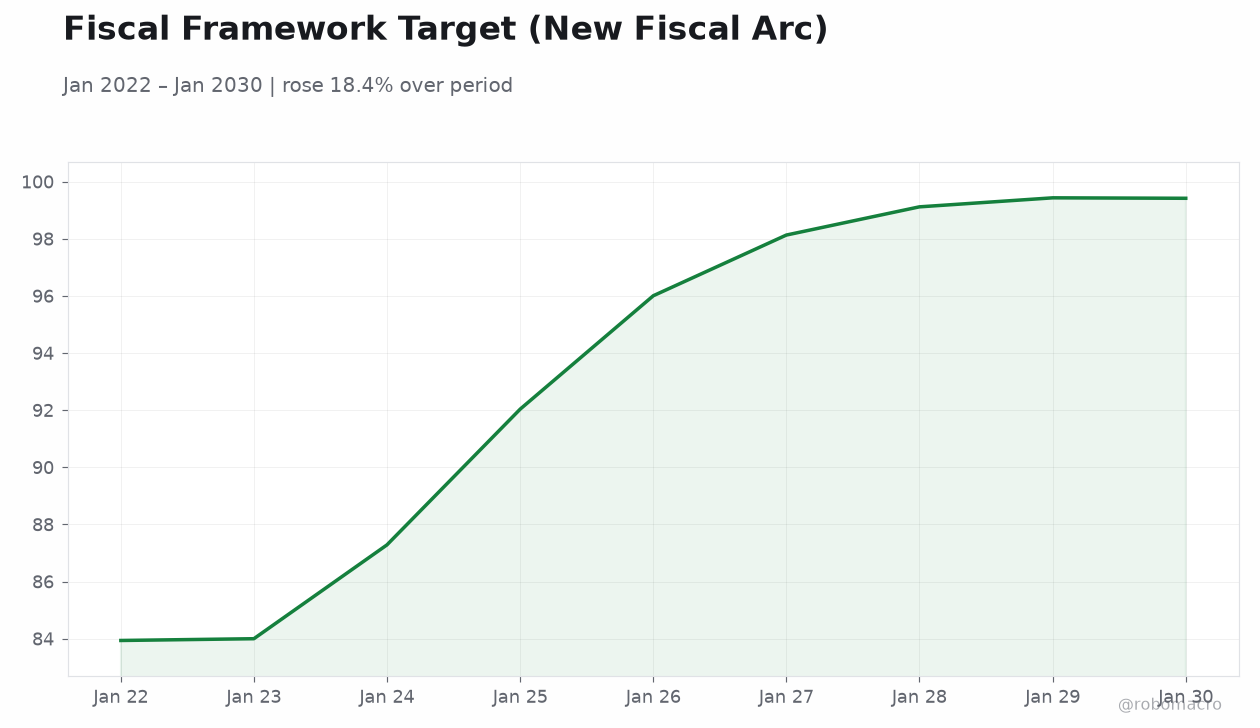
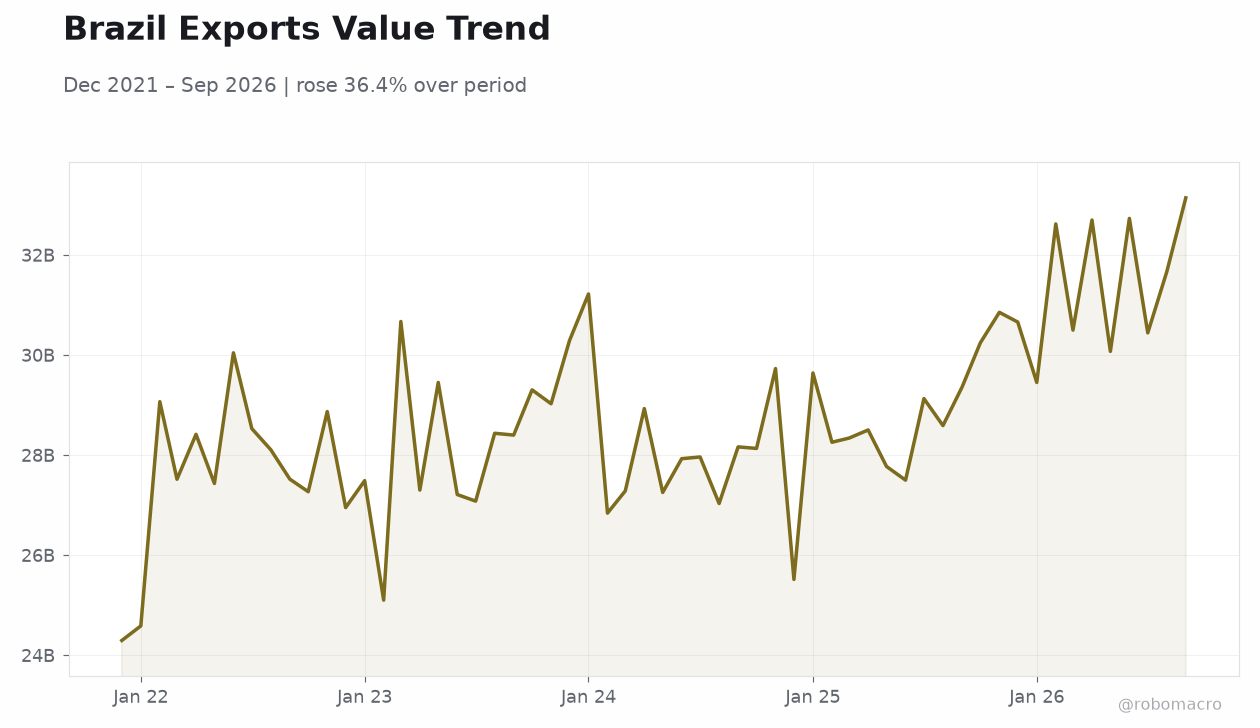
The fiscal backdrop remains the dominant driver of Brazilian asset pricing, with local managers warning that without a credible fiscal anchor, pessimism over the Selic path and GDP will continue to punish cyclical equities. Flavio Bolsonaro's public warning that Brazil risks going broke absent legal security underscores the political dimension of the investment climate debate. President Lula's push to seek new global trade partners in response to US tariffs adds a diplomatic layer to the export outlook.
Meanwhile, Caixa is studying higher mortgage rates as the Selic at 13.75% strains housing credit resources, a sign that tight policy is transmitting into household lending. ↓ p.2