Brazil Macro Daily(Beta Mode)
Real Slides as Growth Streak Ends
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Bovespa | 166,376.00 | -0.69% |
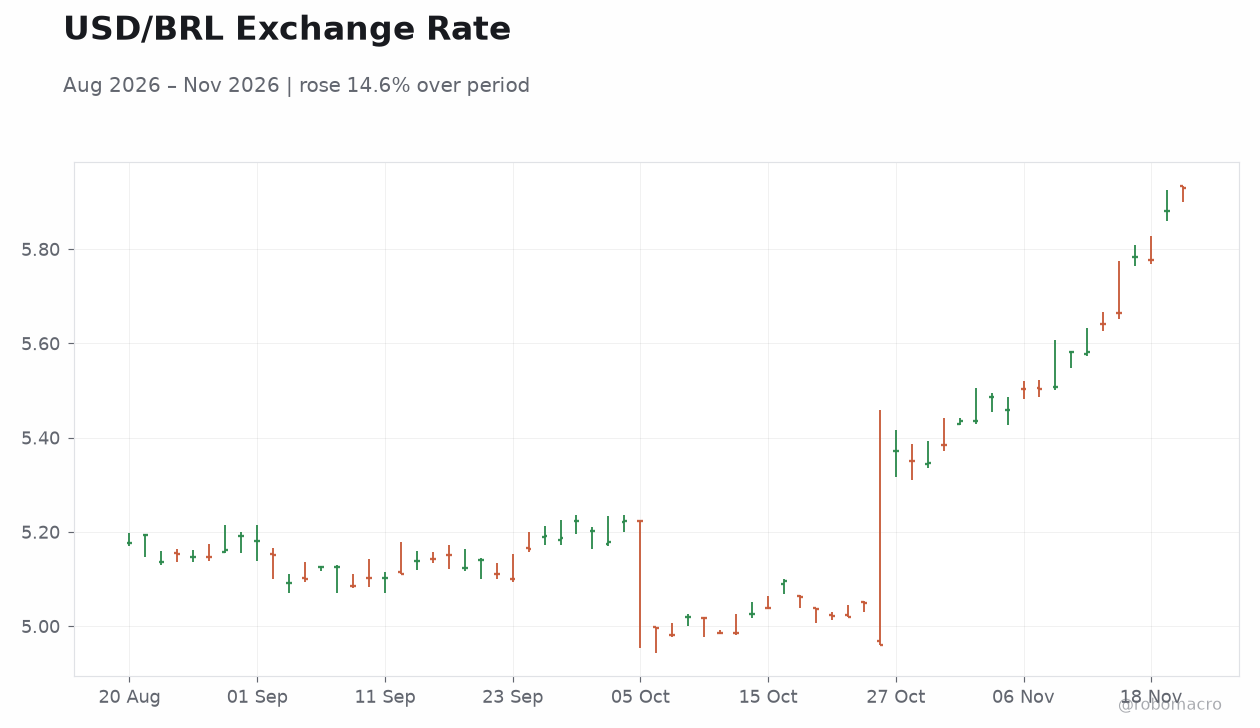
| USD/BRL | 5.93 | +0.81% |
| EUR/BRL | 6.50 | +0.85% |
| Vale | 9.83 | -2.09% |
| Petrobras | 16.29 | -2.63% |
| WTI Crude | 81.57 | -1.97% |
| Gold | 3,582.70 | -2.79% |
| Bitcoin | 61,736.14 | -0.27% |
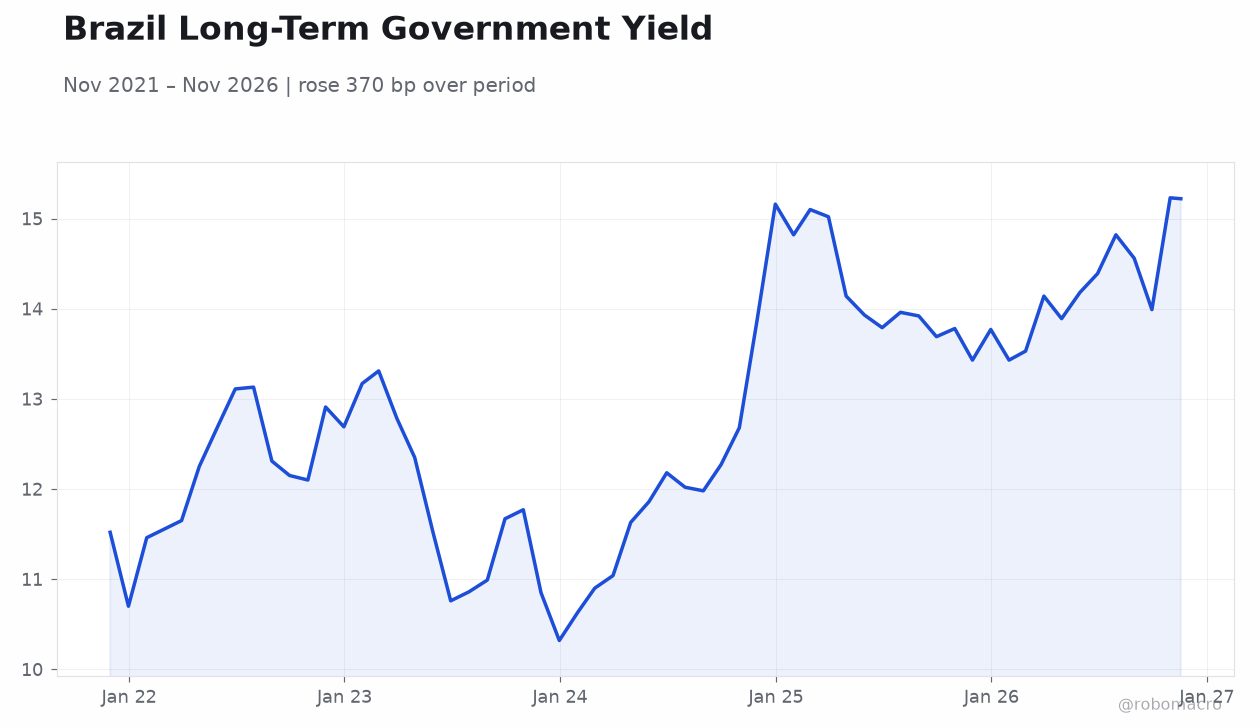
| Brazil 5Y Govt Yield | 15.19% | -7 bp |
| Brazil 10Y Govt Yield | 15.22% | -7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BCB Focus Market Readout | - | - | "" |
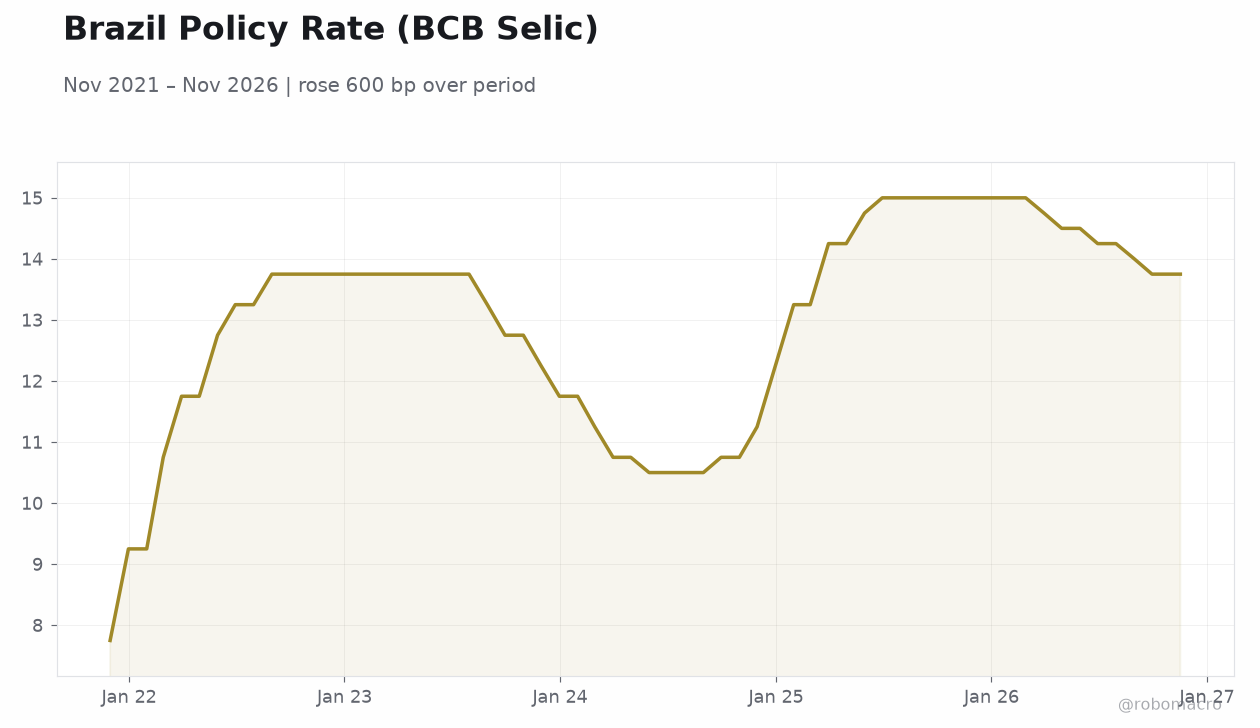 Brazil Policy Rate (BCB Selic) | Type: macro_line | Policy Rate (%): 13.75 (2026-11-17) | Range: 7.75–15 | Trend(5pt): 7.75,13.75,10.5,15,13.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Real weakens past 5.90/USD as BCB intervenes to stem post-election slide
- FGV reports 0.2% GDP contraction, ending 20-quarter growth streak
- Curve rallies 7bp despite FX stress; banks rotate toward Mexico equities
Yesterday's Recap
Brazilian assets sold off across the board on November 19, with the Bovespa shedding 0.69% to 166,376 and the real weakening 0.81% to 5.93/USD despite central bank intervention. The move extended a post-election slide that has forced the BCB to step into the FX market, as reported by the Financial Times. Petrobras fell 2.63% and Vale dropped 2.09%, tracking a 1.97% decline in WTI crude to $81.57 and softer iron ore sentiment.
The FGV survey showing a 0.2% economic contraction in the quarter ended a 20-quarter growth streak, raising concerns about investment and industrial activity. The BCB Focus Market Readout was released Monday, November 16, with no surprises. Notably, the local curve rallied against the FX stress, with the 5-year yield easing 7bp to 15.19% and the 10-year down 7bp to 15.22%, suggesting the market is pricing slower growth rather than inflation risk.
The Day Ahead
The calendar is empty for both today and tomorrow, leaving markets to digest the FGV contraction print and the FX intervention strategy. Attention turns to the BCB's December 9 COPOM meeting, now less than three weeks away, where the committee will weigh the growth slowdown against a still-elevated 4.63% CPI. With no domestic data to anchor the session, real direction will be driven by global risk appetite and commodity flows.
Traders will watch whether the BCB escalates its FX intervention or relies on verbal guidance. The absence of releases also shifts focus to fiscal headlines, particularly the government's tax penalty relief plan tied to the reform deadline.
Other Economic Notes
The FGV contraction marks a meaningful inflection for an economy that had posted uninterrupted growth for five years, and the details point to weakness in investment and industrial activity rather than consumption. Brazil's government is preparing tax penalty relief as companies approach a reform deadline, a measure that could ease corporate cash flow but adds to fiscal uncertainty. BofA flagged a path for capital return to Brazil only if fiscal "homework" is completed, underscoring that foreign investors remain on the sidelines pending credible consolidation.
Banks from Wall Street to Faria Lima are rotating equity preferences toward Mexico, citing diverging growth trajectories. ↓ p.2