Canada Macro Daily(Beta Mode)
BoC Flags Limits of Rate Policy for Housing
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 35,154.80 | -0.23% |
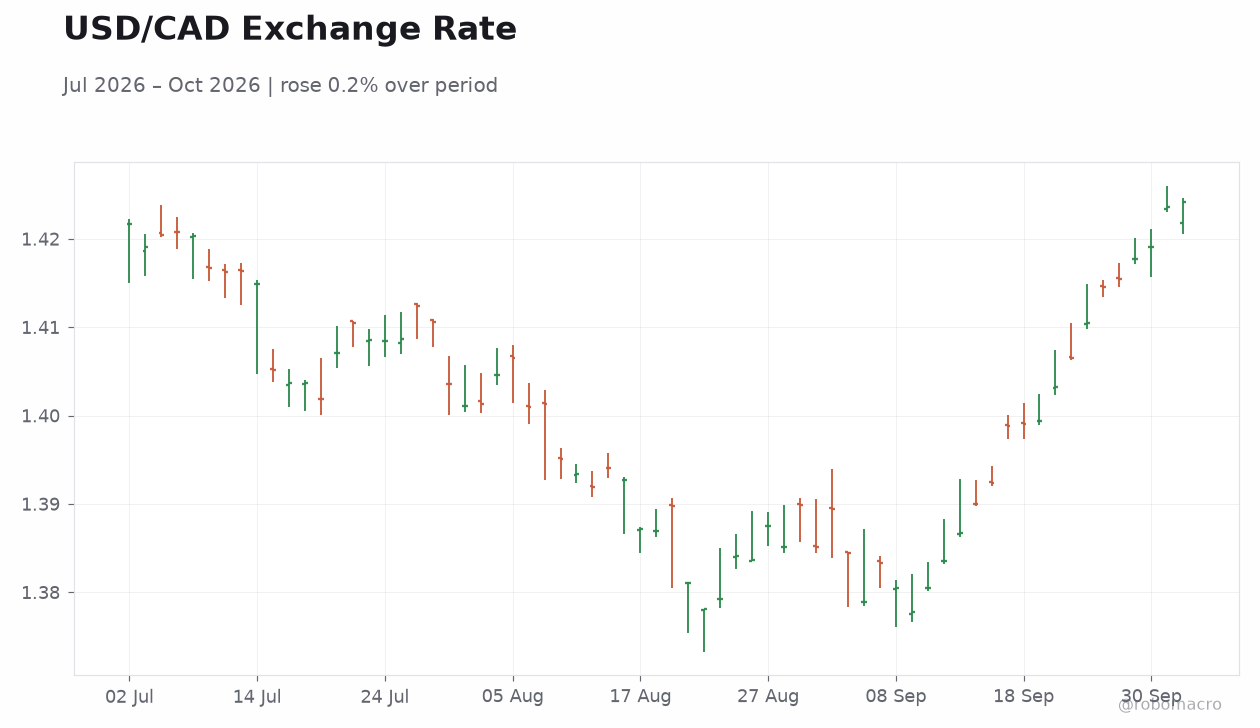
| USD/CAD | 1.42 | +0.02% |
| EUR/CAD | 1.60 | -0.71% |
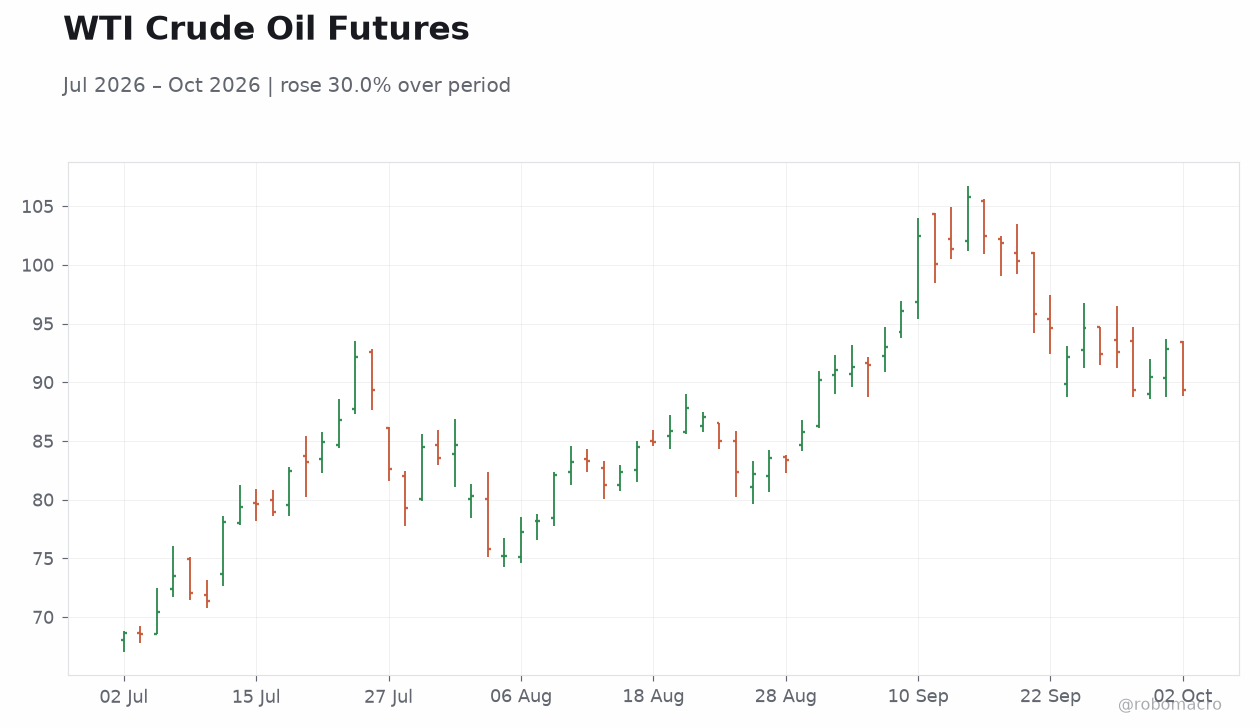
| WTI Crude | 89.24 | -3.91% |
| Natural Gas | 2.92 | -1.62% |
| Gold | 4,210.60 | +0.20% |
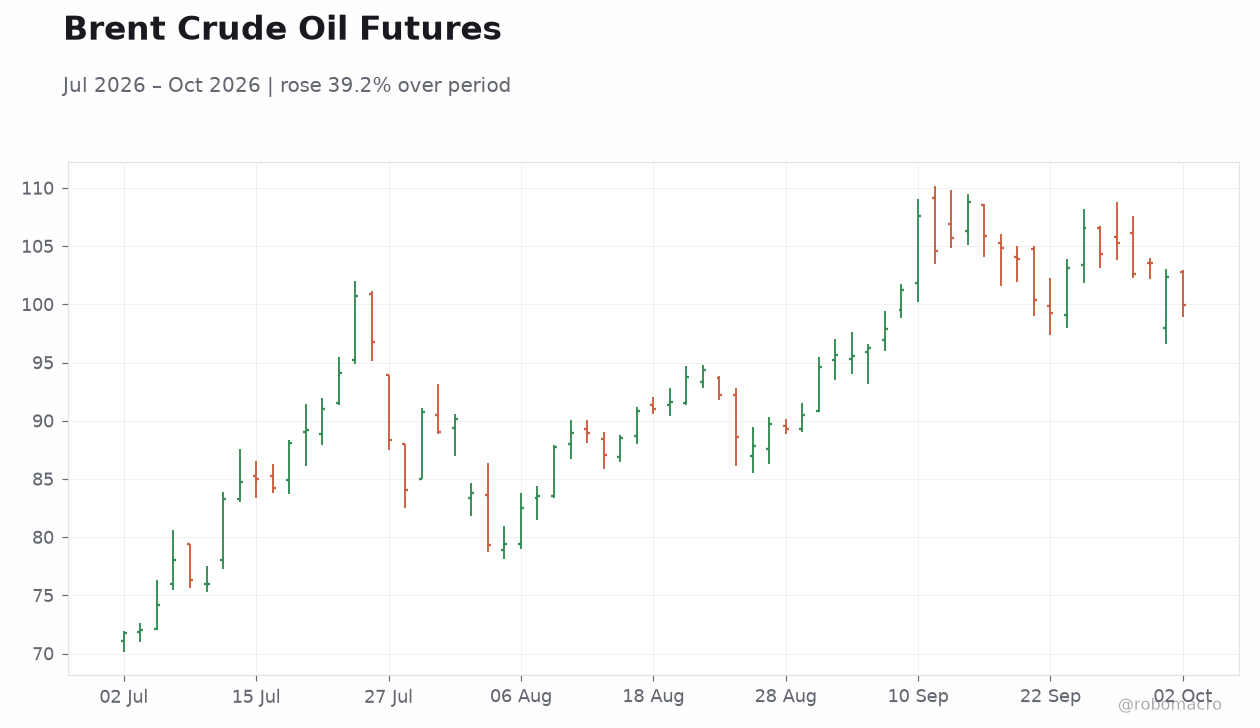
| Brent Crude | 99.85 | -2.40% |
| Bitcoin | 86,476.00 | +1.91% |
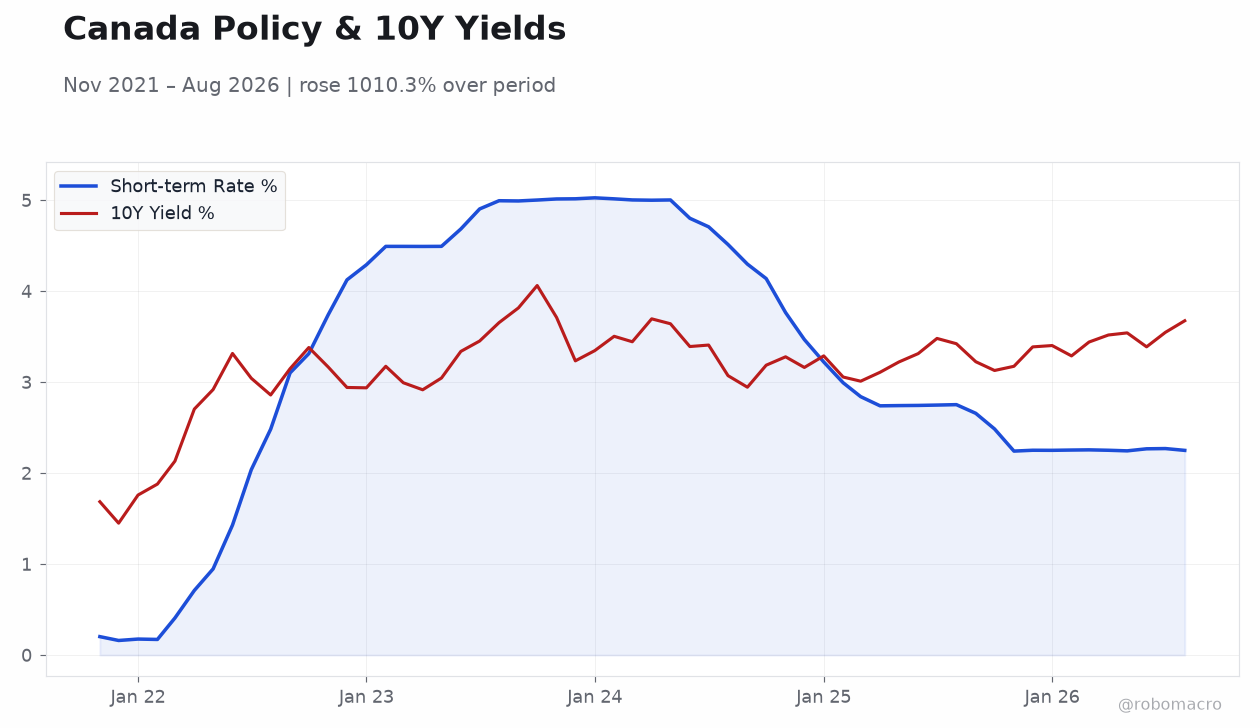
| Canada 2Y Govt Yield | 3.37% | +2 bp |
| Canada 10Y Govt Yield | 3.96% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| GDP Month-over-Month | 0.40 | 0 | 0 |
| GDP Month-over-Month Prel | 0 | - | 0.20 |
| S&P Global Manufacturing PMI Index | 53 | - | 51.50 |
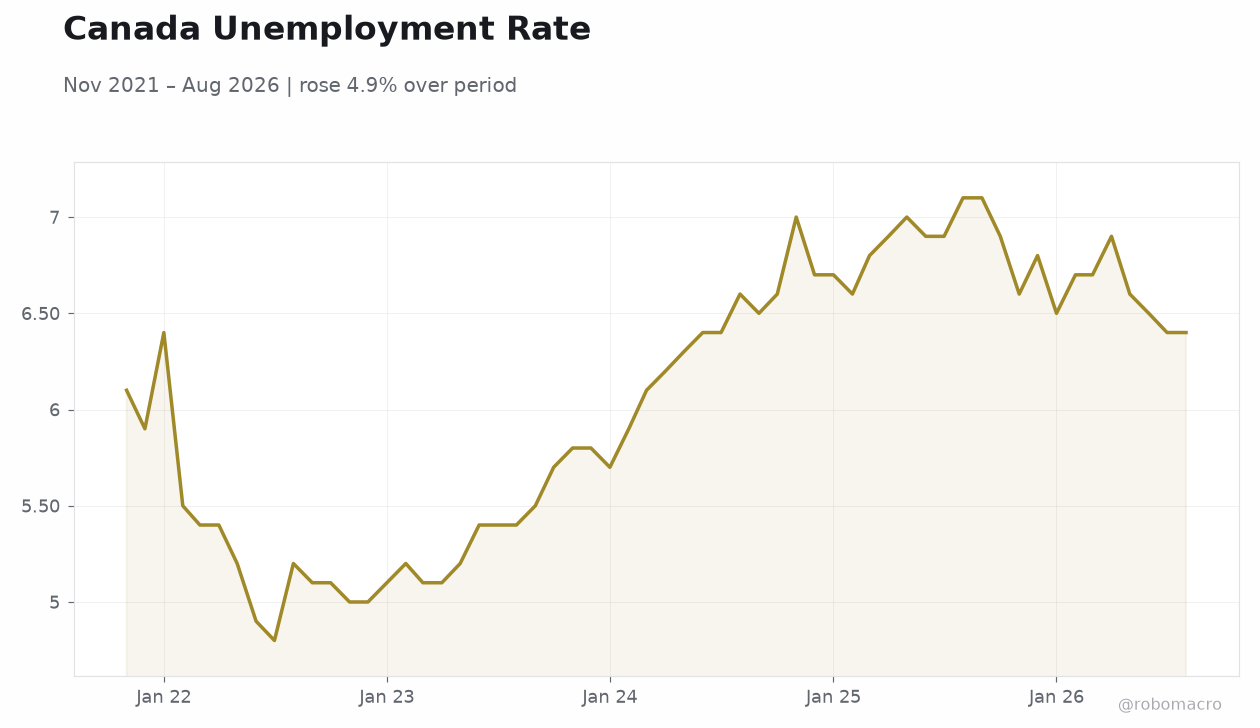 Canada Unemployment Rate | Type: macro_line | Unemployment Rate %: 6.4 (2026-08-01) | Range: 4.8–7.1 | Trend(5pt): 6.1,5.1,6.1,7,6.4
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- GDP flat in August while manufacturing PMI slips to 51.5
- Rogers says rates too blunt to address housing affordability
- TSX falls 0.23 percent as WTI crude drops 3.91 percent
Yesterday's Recap
Statistics Canada reported August GDP flat at 0.0 percent month-over-month against a 0.4 percent prior reading, with a preliminary estimate showing 0.2 percent growth. The S&P Global Manufacturing PMI declined to 51.5 from 53.0, confirming softer factory momentum. Headline CPI reached 3.00 percent in August as gasoline prices rebounded.
The S&P/TSX Composite closed at 35,154.80, down 0.23 percent. WTI crude fell to 89.24, a 3.91 percent decline, while the 2-year Canada yield rose 2 basis points to 3.37 percent and the 10-year yield climbed 2 basis points to 3.96 percent. USD/CAD edged 0.02 percent higher to 1.42 amid softer domestic data and firmer U.S.
dollar flows. Natural gas declined 1.62 percent to 2.92. Brent crude eased 2.40 percent to 99.85 and gold rose 0.20 percent to 4,210.60.
The Day Ahead
No Canadian data releases or Bank of Canada speeches are scheduled for October 2. Tomorrow’s calendar is also empty, leaving markets without fresh domestic anchors. Focus will remain on external oil-price swings and any follow-through from Deputy Governor Rogers’ housing remarks.
USD/CAD and energy futures are likely to dictate intraday moves in the absence of local prints. Traders will continue to monitor September CPI due October 19 for clues on the next policy step. EUR/CAD fell 0.71 percent to 1.60 as cross-border flows reacted to softer Canadian data.
Other Economic Notes
Gasoline-driven inflation at 3.00 percent keeps the Bank of Canada’s 2.25 percent policy rate in focus even as housing affordability remains outside its direct reach. The new forecasting model’s heavier emphasis on mortgages highlights structural transmission channels but does not alter the committee’s view that rate policy cannot target house prices. Broader Canadian growth appears steady yet lacks momentum, with flat GDP and the PMI decline pointing to subdued near-term expansion.
Energy-price volatility continues to shape both inflation outcomes and CAD crosses, amplifying external shocks to domestic markets. A $30-million rocket-engine test facility announced in London, Ontario, is projected to support long-term industrial capacity without immediate market impact.