Canada Macro Daily(Beta Mode)
Loonie Steadies Near 1.42 as Oil Slides
Market Snapshot
| Asset | Level | Change |
|---|---|---|
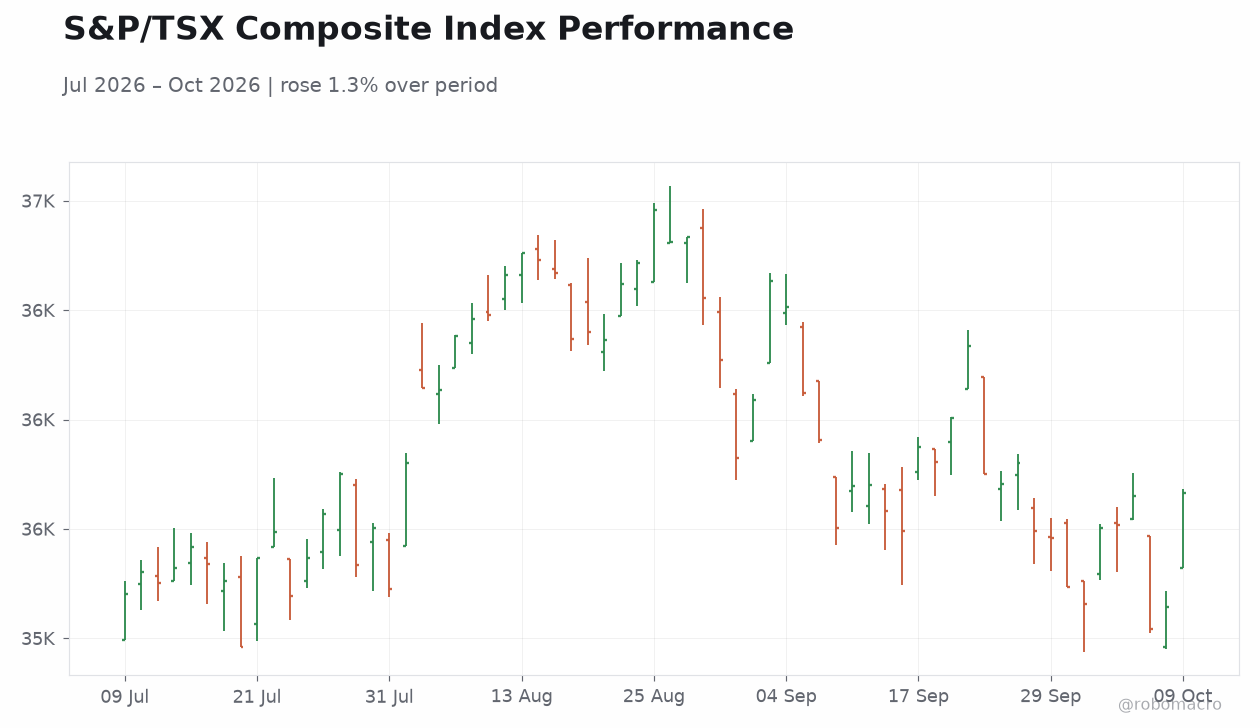
| S&P/TSX | 35,664.60 | +1.48% |
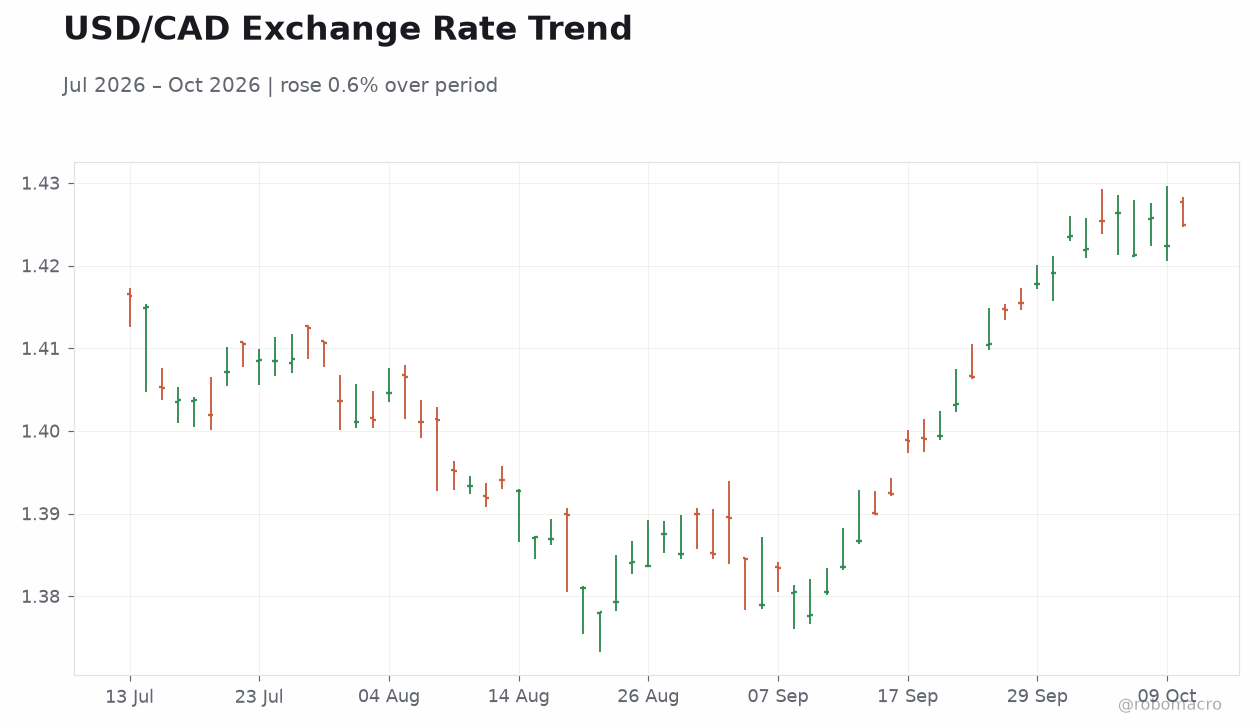
| USD/CAD | 1.42 | -0.24% |
| EUR/CAD | 1.59 | -0.02% |
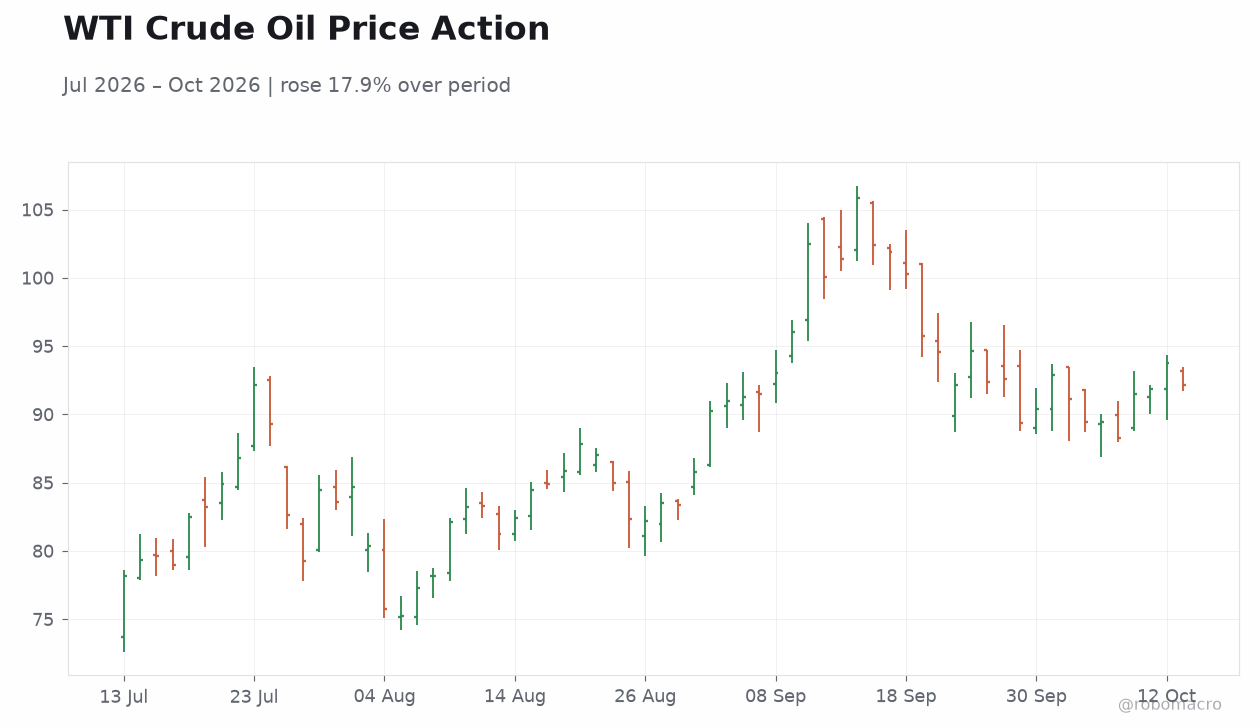
| WTI Crude | 92.08 | -1.77% |
| Natural Gas | 3.12 | -1.55% |
| Gold | 4,207.60 | +0.41% |
| Brent Crude | 104.80 | -1.73% |
| Bitcoin | 83,476.80 | +2.10% |
| Canada 2Y Govt Yield | 3.24% | +1 bp |
| Canada 10Y Govt Yield | 3.93% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
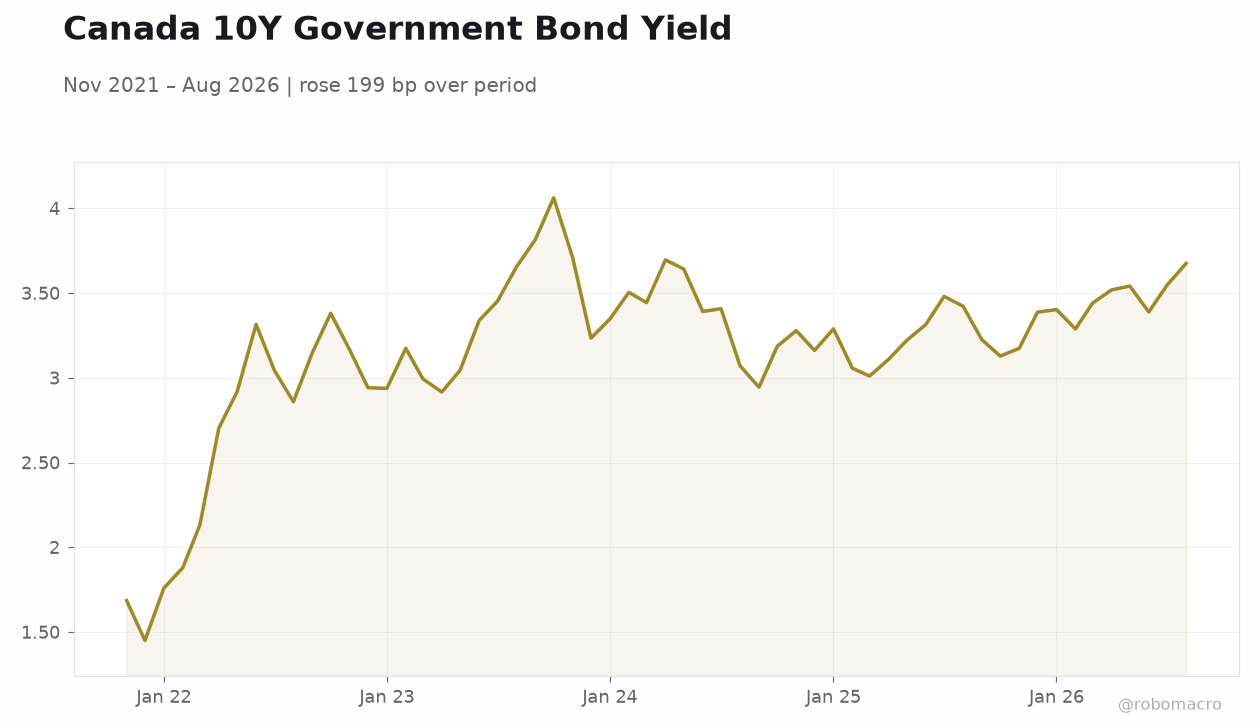 Canada 10Y Government Bond Yield | Type: macro_line | 10Y Yield %: 3.675 (2026-08-01) | Range: 1.45–4.062 | Trend(6pt): 1.686,2.938,3.444,3.221,3.547,3.675
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-10-14) | |||
| BoC Gov Macklem Speech | - | - | 02:05 |
| Thursday (2026-10-15) | |||
| BoC Rogers Speech | - | - | 05:00 |
| Friday (2026-10-16) | |||
| BoC Gov Macklem Speech | - | - | 00:15 |
| Housing Starts Level | 229,000 | 230,000 | 08:15 |
- TSX gains 1.48% to 35,664.60 while WTI crude falls 1.77% to $92.08, leaving USD/CAD pinned near 1.42 as the oil drag offsets broader USD softness.
- Canada 2Y yield edges up 1 bp to 3.24% and the 10Y eases 1 bp to 3.93%, with the curve flattening marginally ahead of a heavy BoC speaker schedule.
- Governor Macklem speaks Wednesday and Friday, with Senior Deputy Governor Rogers Thursday — markets will parse tone for confirmation the Bank stays on hold at 2.25% into the next decision.
Yesterday's Recap
Canadian markets caught a firm bid Monday. The S&P/TSX Composite rallied 1.48% to close at 35,664.60, led by strength in financials and gold names as bullion added 0.41% to $4,207.60. Bitcoin's 2.10% jump to $83,476.80 supported crypto-exposed equities.
The commodity complex was weaker, however: WTI crude dropped 1.77% to $92.08, Brent lost 1.73% to $104.80, and natural gas slid 1.55% to $3.12, weighing on energy producers despite the broader equity advance. In FX, USD/CAD slipped 0.24% to 1.42, with the loonie finding support from a softer dollar backdrop that cushioned the impact of sliding crude. EUR/CAD was essentially flat at 1.59.
Rates markets were quiet, with the 2Y yield ticking up 1 bp to 3.24% while the 10Y eased 1 bp to 3.93% — a marginal flattening suggesting traders see the easing cycle largely complete while growth momentum holds. It was a holiday-thinned session in the US, keeping volumes subdued across North American fixed income.
The Day Ahead
The week's key event arrives Wednesday at 02:05 ET when Governor Tiff Macklem delivers a high-impact speech. With the Bank of Canada having held the overnight rate at 2.25% at its October 5 decision, markets will scrutinize Macklem's language on the inflation outlook — headline CPI ran at 3.00% in the latest reading, above the 2% target — and on how long the Bank intends to stay on the sidelines. Thursday brings Senior Deputy Governor Carolyn Rogers at 05:00 ET, another high-impact event likely to probe financial-system and transmission questions.
Friday features a second Macklem appearance at 00:15 ET, followed at 08:15 by housing starts, where consensus looks for 230,000 annualized units versus 229,000 previously. The cluster of Governing Council appearances in a single week is unusual and suggests a coordinated effort to anchor expectations ahead of the next policy decision.
Other Economic Notes
The inflation picture has re-emerged as the dominant macro narrative, with gasoline-price rebounds pushing headline CPI to 3.00% year over year — a level that complicates the narrative of a completed easing cycle. ↓ p.2