Canada Macro Daily(Beta Mode)
BoC Poised to Hike as Inflation Expectations Rise
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 36,171.50 | +0.63% |
| USD/CAD | 1.40 | +0.23% |
| EUR/CAD | 1.56 | -0.21% |
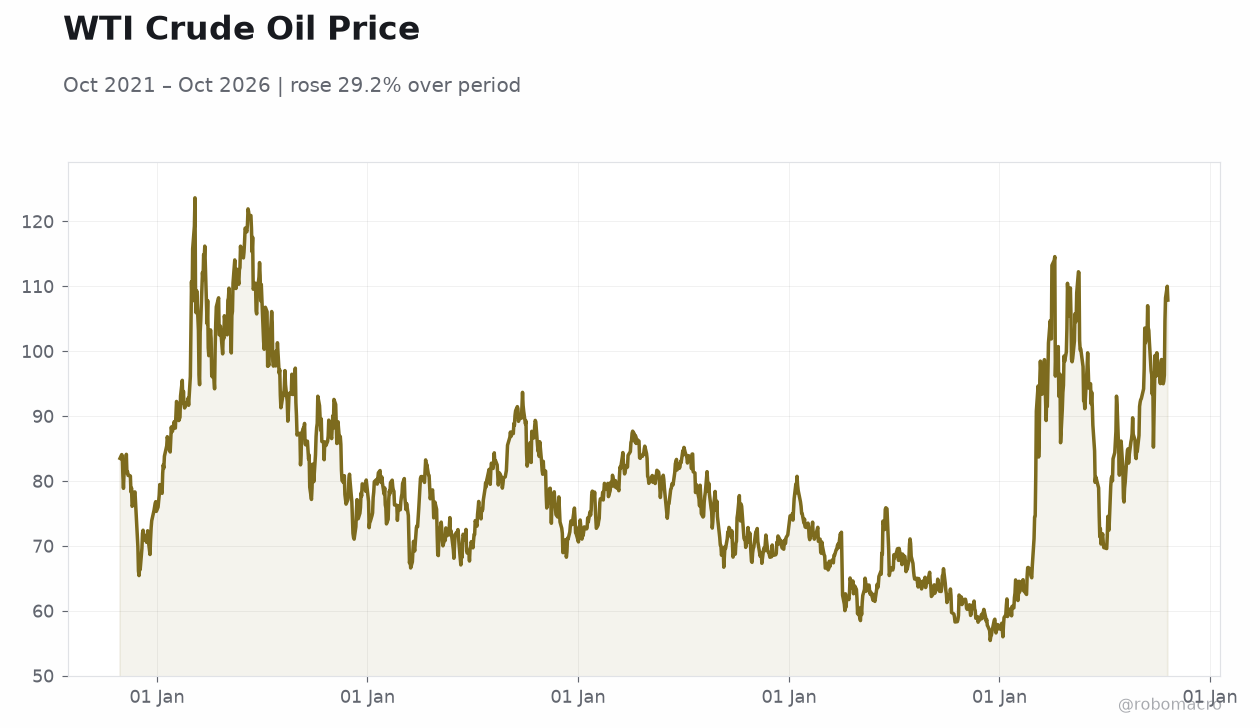
| WTI Crude | 101.57 | +1.67% |
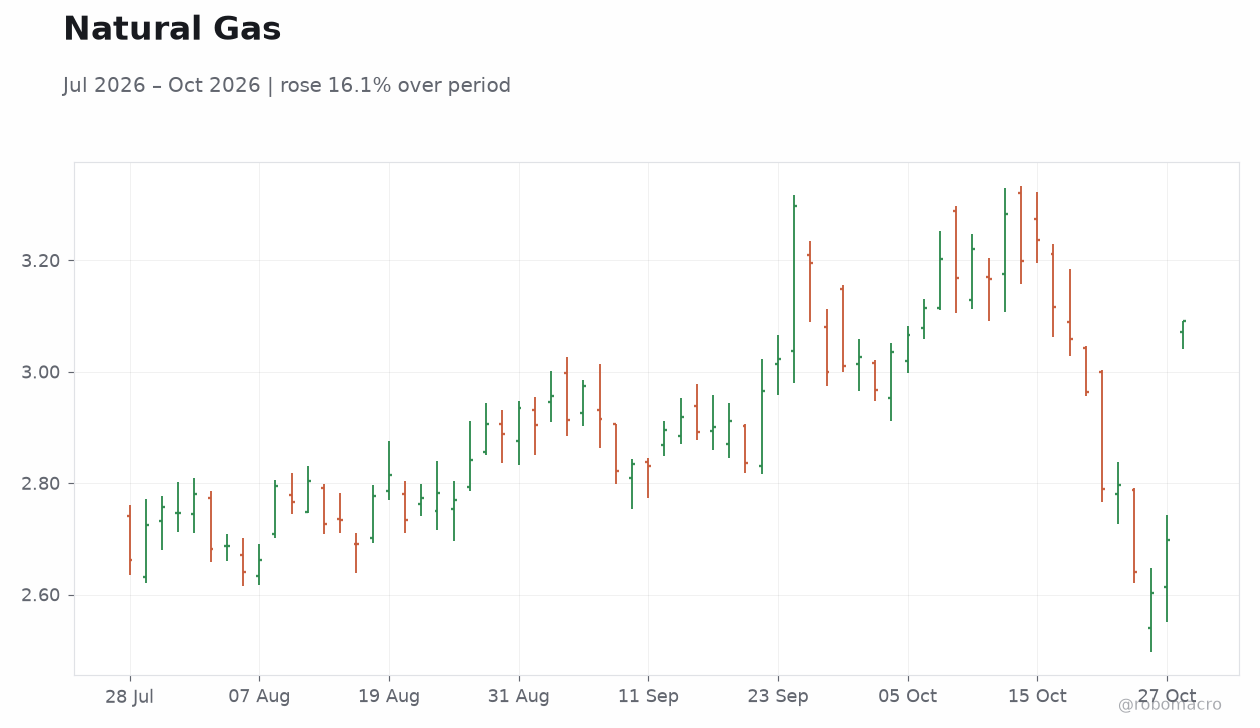
| Natural Gas | 3.08 | +14.31% |
| Gold | 4,060.40 | -0.35% |
| Brent Crude | 111.29 | -2.27% |
| Bitcoin | 81,271.38 | +0.58% |
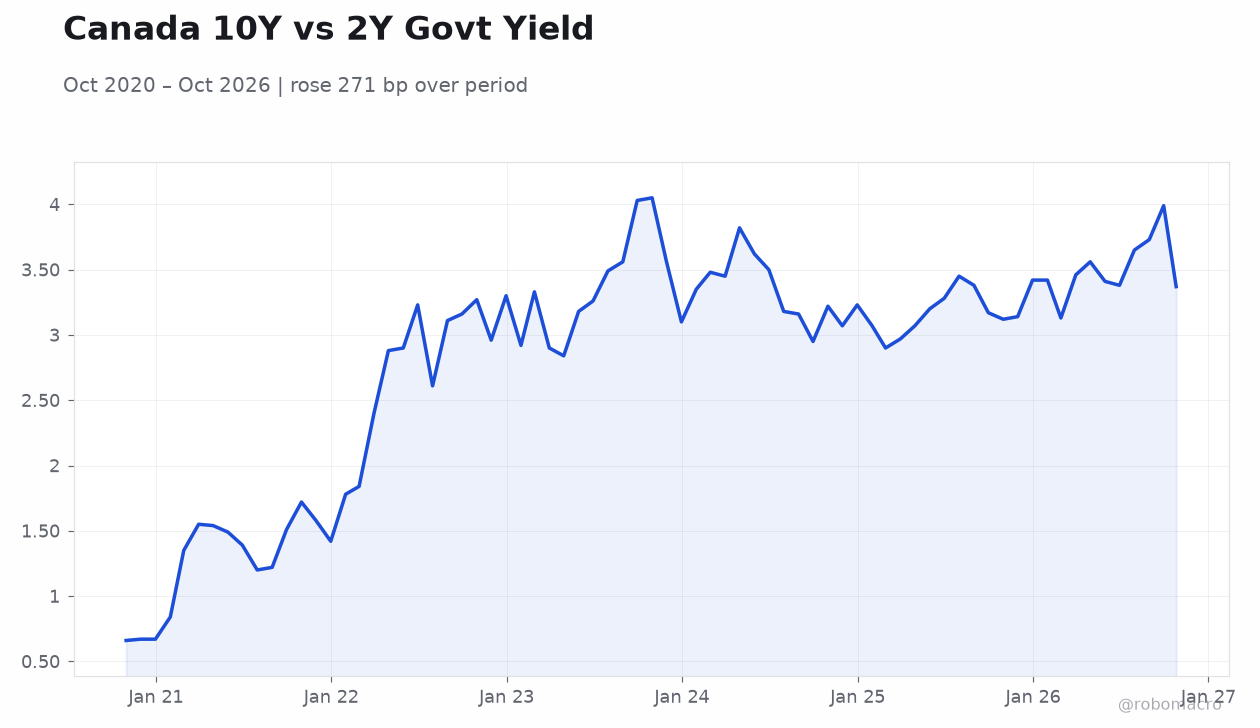
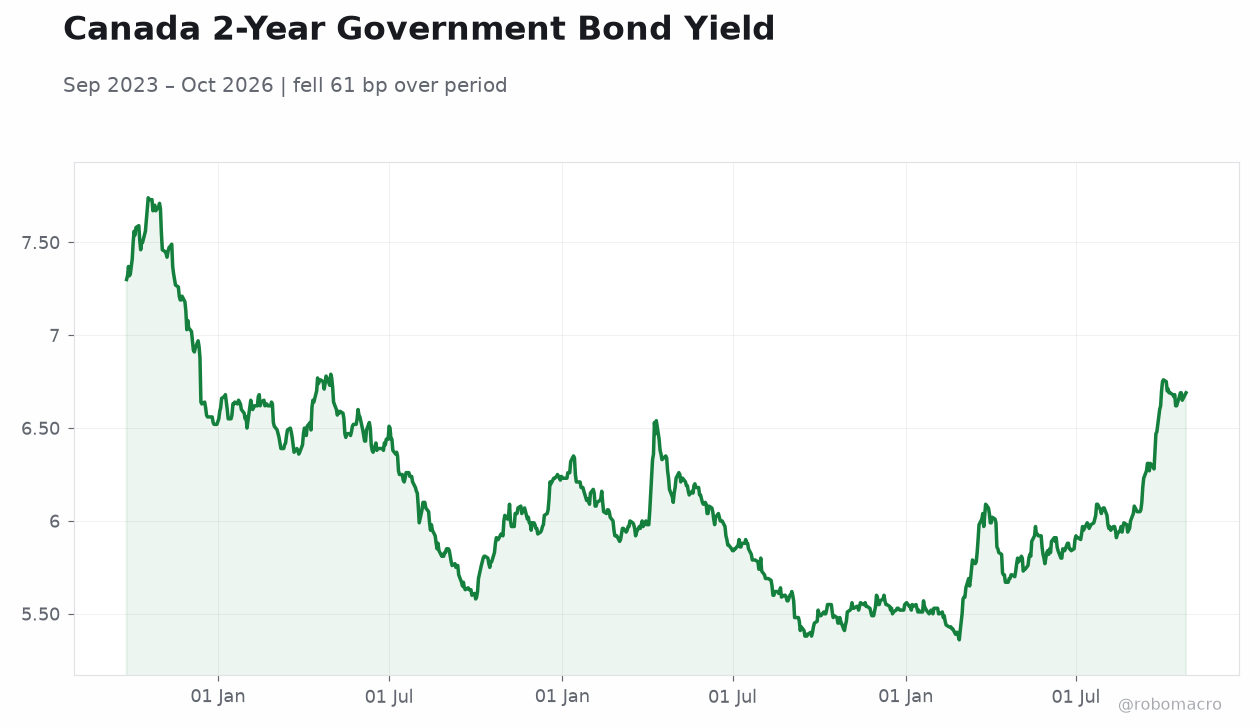
| Canada 2Y Govt Yield | 3.37% | +4 bp |
| Canada 10Y Govt Yield | 3.84% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
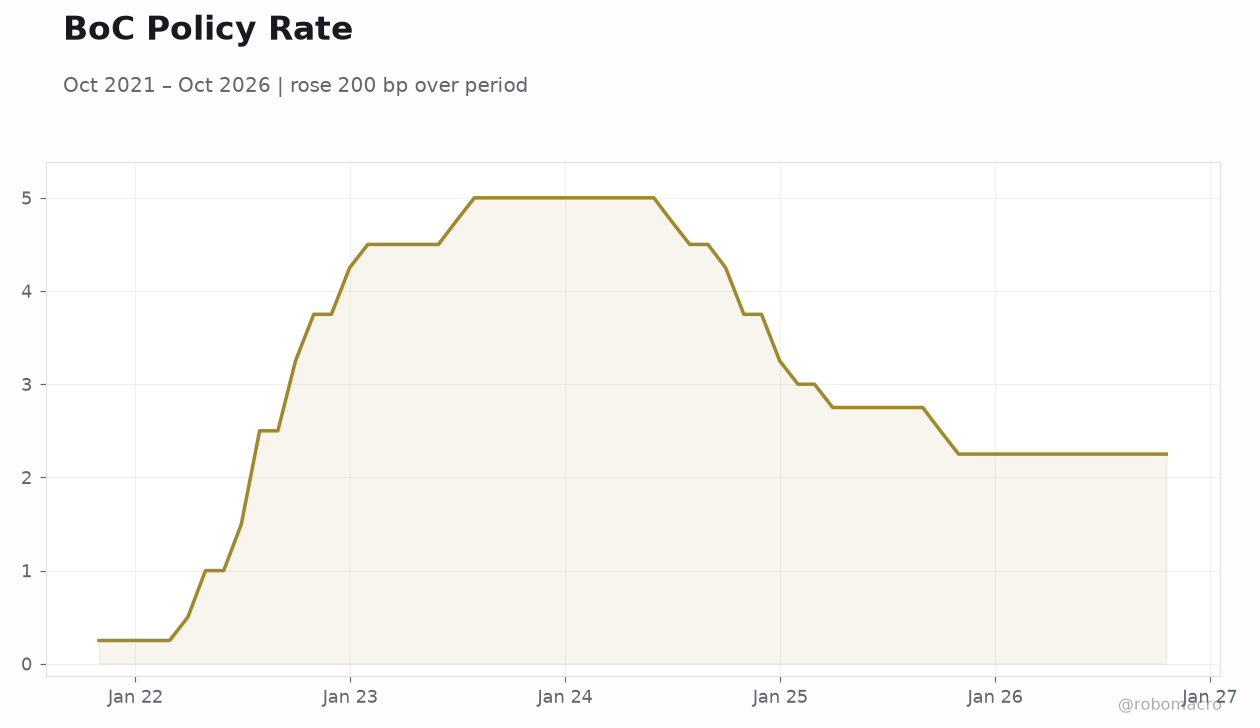 BoC Policy Rate | Type: macro_line | Policy Rate %: 2.25 (2026-10-19) | Range: 0.25–5 | Trend(5pt): 0.25,4.5,5,2.75,2.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BoC Interest Rate Decision | 2.25 | 2.50 | 09:45 |
| BoC Monetary Policy Report | - | - | 09:45 |
| BoC Rate Statement | - | - | 09:45 |
| BoC Press Conference | - | - | 10:30 |
| Friday (2026-10-30) | |||
| GDP Month-over-Month | 0 | 0.20 | 08:30 |
| GDP Month-over-Month Prel | - | - | 08:30 |
- Bank of Canada expected to raise its policy rate from 2.25% at today's 09:45 ET decision, the first hike since 2023, with consensus at 2.5%
- September CPI at 3.09% YoY and rising inflation expectations in the BoC's own survey have cemented the case for tightening
- Energy complex is the wildcard: WTI above $101 and natural gas up 14% yesterday keep upside inflation risks alive even as Brent slipped
Yesterday's Recap
There were no scheduled Canadian data releases on Tuesday, leaving markets to position ahead of today's Bank of Canada decision. The S&P/TSX Composite closed up 0.63% at 36,171.50, with energy names likely leading on the back of a 1.67% jump in WTI to $101.57 and a striking 14.31% surge in natural gas to $3.08. The Canadian dollar weakened, with USD/CAD rising 0.23% to 1.40, while EUR/CAD slipped 0.21% to 1.56.
Rates markets leaned hawkish: the Canada 2-year yield climbed 4 bp to 3.37% and the 10-year added 1 bp to 3.84%, steepening modestly as front-end risk premium built into the curve. Gold eased 0.35% to $4,060.40, and Brent fell 2.27% to $111.29 amid Middle East peace-talk headlines, diverging from WTI's gain. Bitcoin was marginally firmer at $81,271.
The Day Ahead
All eyes are on the Bank of Canada's 09:45 ET announcement, with consensus expecting a 25 bp hike to 2.5% from the current 2.25% — a move that would mark the first increase since 2023. The decision lands alongside the full Monetary Policy Report and Rate Statement, followed by the 10:30 ET press conference, where Governing Council will be pressed on the inflation outlook and the pace of any further tightening. Markets will parse the MPR's growth and inflation projections for signals on the terminal rate path.
Attention then shifts to Friday's 08:30 ET GDP release, with month-over-month growth consensus at 0.2% following a flat prior print. No Canadian releases are scheduled for Thursday.
Other Economic Notes
The inflation backdrop has deteriorated decisively, with September CPI at 3.09% YoY driven by a gasoline price rebound, and the BoC's own survey showing a notable rise in inflation expectations — a combination that undermines the case for patience. Energy dynamics are amplifying the problem: with WTI above $101 and natural gas spiking, input costs are feeding through to headline prices even as Brent's pullback on peace hopes offers limited relief. The Canadian dollar's slide toward 1.40 versus the greenback adds imported inflation pressure, complicating the BoC's calculus.
Financial conditions have already tightened via the front end, with the 2-year yield at 3.37% reflecting markets pricing further hikes. ↓ p.2