Canada Macro Daily(Beta Mode)
BoC Hikes to 2.50% as Growth Stalls
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 36,249.00 | -0.04% |
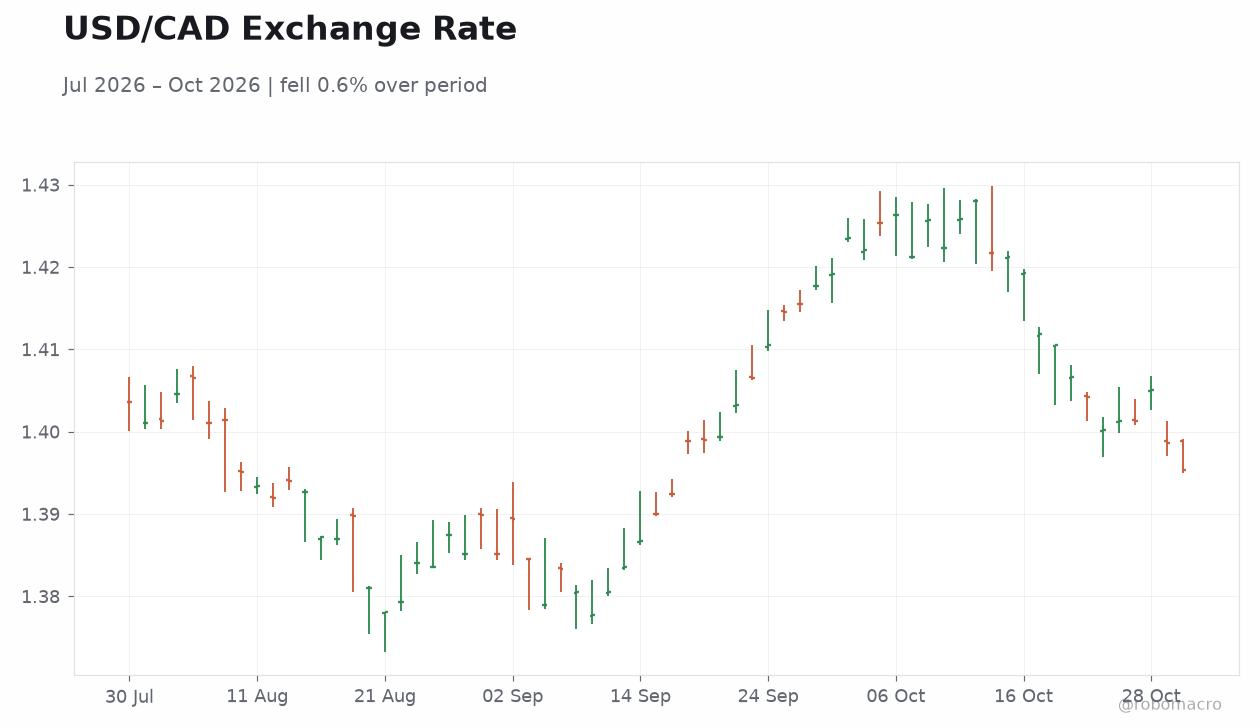
| USD/CAD | 1.40 | -0.22% |
| EUR/CAD | 1.56 | +0.12% |
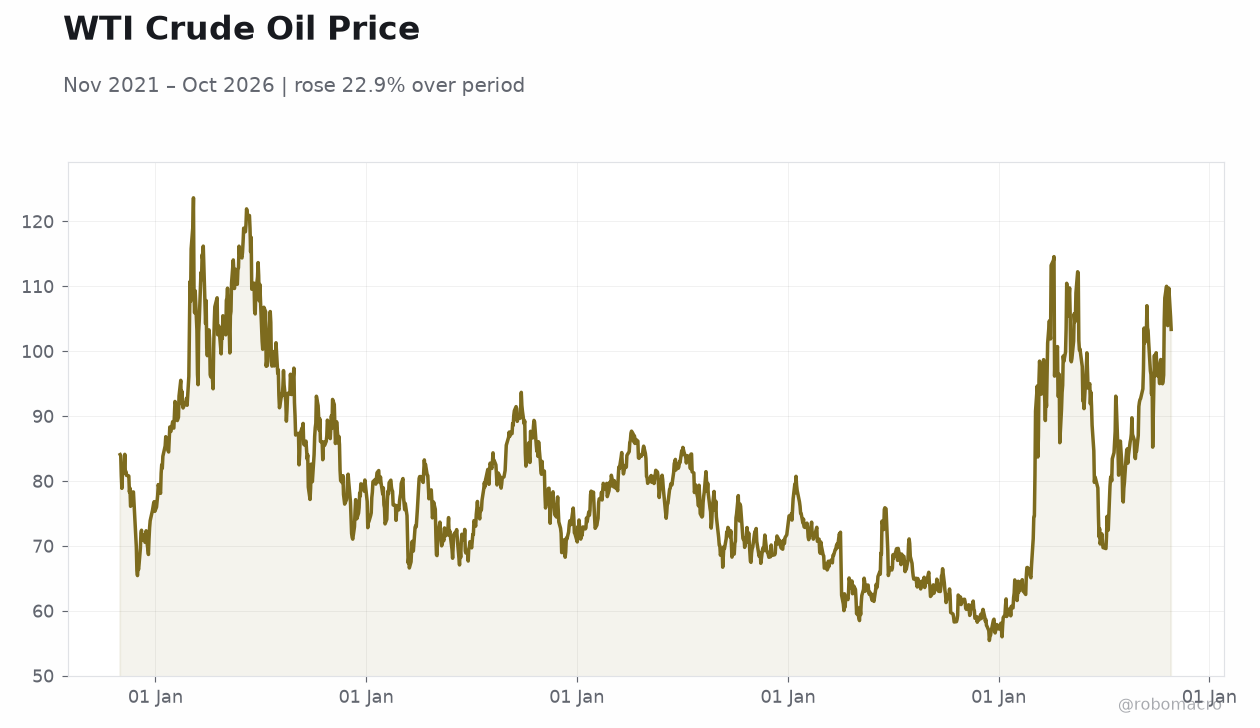
| WTI Crude | 104.13 | +2.09% |
| Natural Gas | 2.89 | -2.00% |
| Gold | 3,980.00 | -1.27% |
| Brent Crude | 113.38 | -1.31% |
| Bitcoin | 77,557.00 | -0.28% |
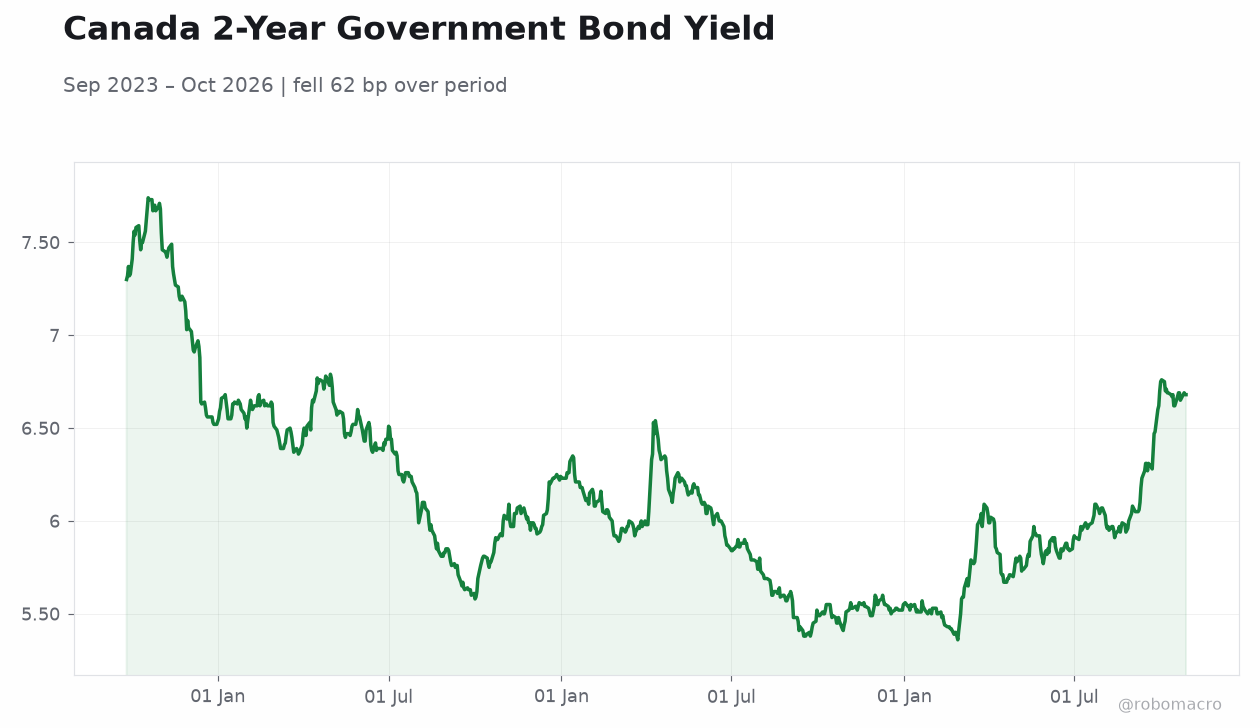
| Canada 2Y Govt Yield | 3.41% | +5 bp |
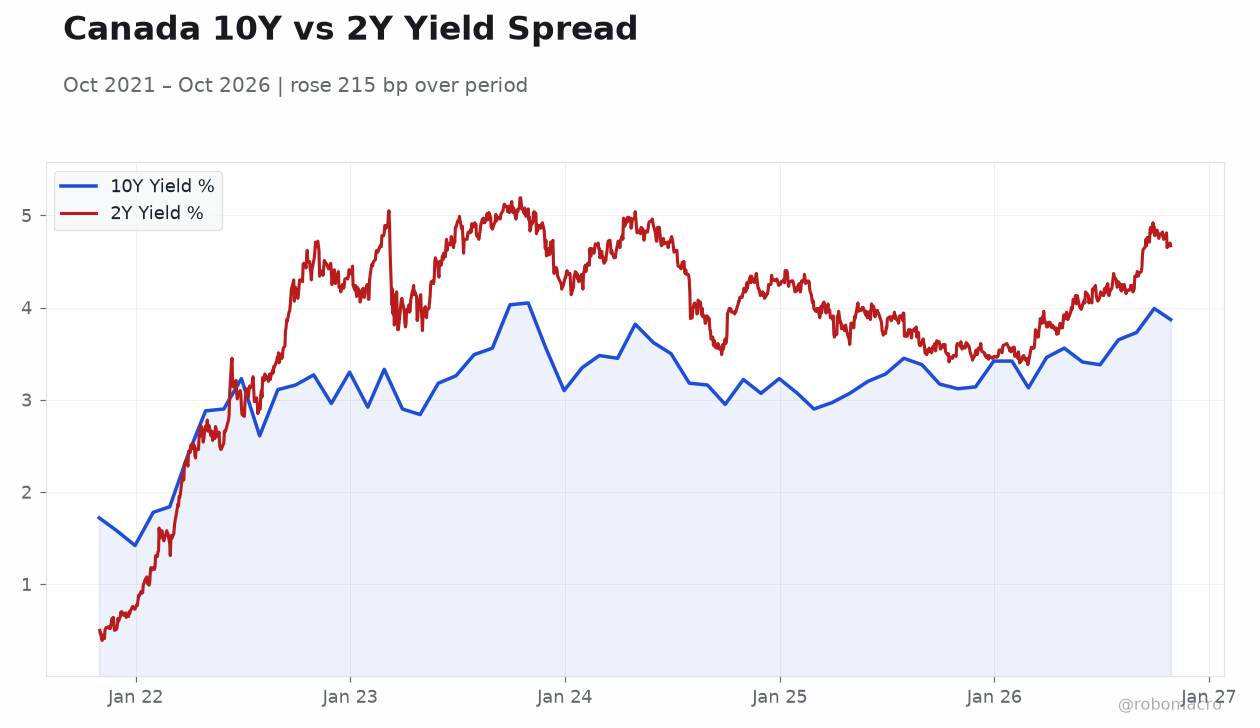
| Canada 10Y Govt Yield | 3.87% | +4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BoC Interest Rate Decision | 2.25 | 2.50 | 2.50 |
| BoC Monetary Policy Report | - | - | - |
| BoC Rate Statement | - | - | - |
| BoC Press Conference | - | - | - |
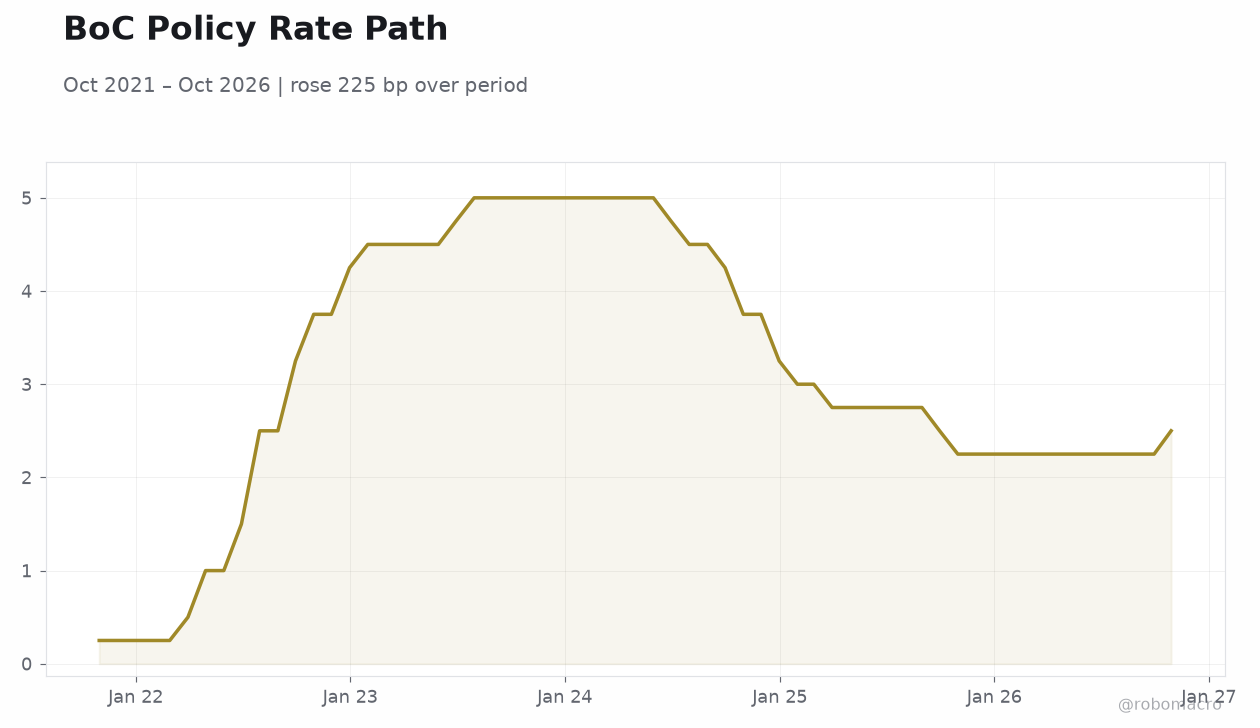 BoC Policy Rate Path | Type: macro_line | Policy Rate %: 2.5 (2026-10-29) | Range: 0.25–5 | Trend(5pt): 0.25,4.5,5,2.75,2.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| GDP Month-over-Month | 0 | 0.20 | 08:30 |
| GDP Month-over-Month Prel | - | - | 08:30 |
- Bank of Canada raised its policy rate 25 bp to 2.50% on October 28 — the first hike since 2023 — citing persistent inflation pressures even as growth remains sluggish.
- Canada 2Y and 10Y Government of Canada yields rose 5 bp and 4 bp respectively, steepening modestly to 3.41% and 3.87% as markets digest the tightening cycle's restart.
- Today's GDP month-over-month print (consensus +0.2%) will be the first hard test of whether the economy can absorb higher rates; USD/CAD slipped 0.22% to 1.40 on the hike.
Yesterday's Recap
The Bank of Canada delivered a 25 bp increase to 2.50% on October 28, marking its first rate hike since 2023, alongside the Monetary Policy Report and Rate Statement, with the Governor's press conference following at 10:30 ET. The decision landed in line with consensus expectations of 2.50%. Markets responded with a modest hawkish adjustment: the 2-year Government of Canada yield climbed 5 bp to 3.41% and the 10-year rose 4 bp to 3.87%, reflecting higher expected policy rates rather than growth optimism.
The S&P/TSX was essentially flat at 36,249, down 0.04%, as energy strength offset rate-sensitive sectors. USD/CAD fell 0.22% to 1.40, with the loonie firming as traders assessed the hike against incoming US data. WTI crude jumped 2.09% to $104.13, providing an offsetting tailwind for Canadian terms of trade even as the BoC flagged continued weakness in the economy.
The Day Ahead
Statistics Canada releases GDP month-over-month for the prior month at 08:30 ET, with consensus at +0.2% following a flat prior reading of 0.0%; the preliminary GDP estimate is also scheduled for the same slot. This is the key domestic data point of the week and the first growth read since the BoC's decision, making it a direct referendum on whether the hike is premature. A downside surprise would reinforce the argument — echoed by Rosenberg and others — that the central bank has tightened into weakness, while an upside print would validate the BoC's inflation-fighting stance.
No other Canadian releases are scheduled today, and tomorrow's calendar is empty, so positioning into month-end will be driven by this morning's print and US data flow.
Other Economic Notes
The BoC's own commentary acknowledges continued weakness in the Canadian economy, a theme amplified by media coverage questioning whether Ottawa's growth plan is delivering. Fiscal wiggle room is shrinking as budget wishlists expand, raising the prospect of crowding-out pressure on provincial and federal issuance — a structural backdrop for Government of Canada bond supply. ↓ p.2