Emerging Europe Macro Daily(Beta Mode)
MNB Holds at 5.5%, Forint Softens as Gold Bid Continues
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| BIST 100 | 11,577.10 | -1.87% |
| iShares Poland | 44.97 | +1.72% |
| EUR/PLN | 4.36 | -0.19% |
| EUR/HUF | 365.24 | +0.37% |
| EUR/CZK | 24.27 | -0.09% |
| USD/TRY | 49.61 | +0.05% |
| Brent Crude | 111.21 | +2.20% |
| Gold | 4,103.20 | -1.13% |
| Bitcoin | 82,811.84 | -0.16% |
| Poland 10Y Govt Yield | - | - |
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Central Bank Interest Rate Decision | 5.50 | 5.50 | 5.50 |
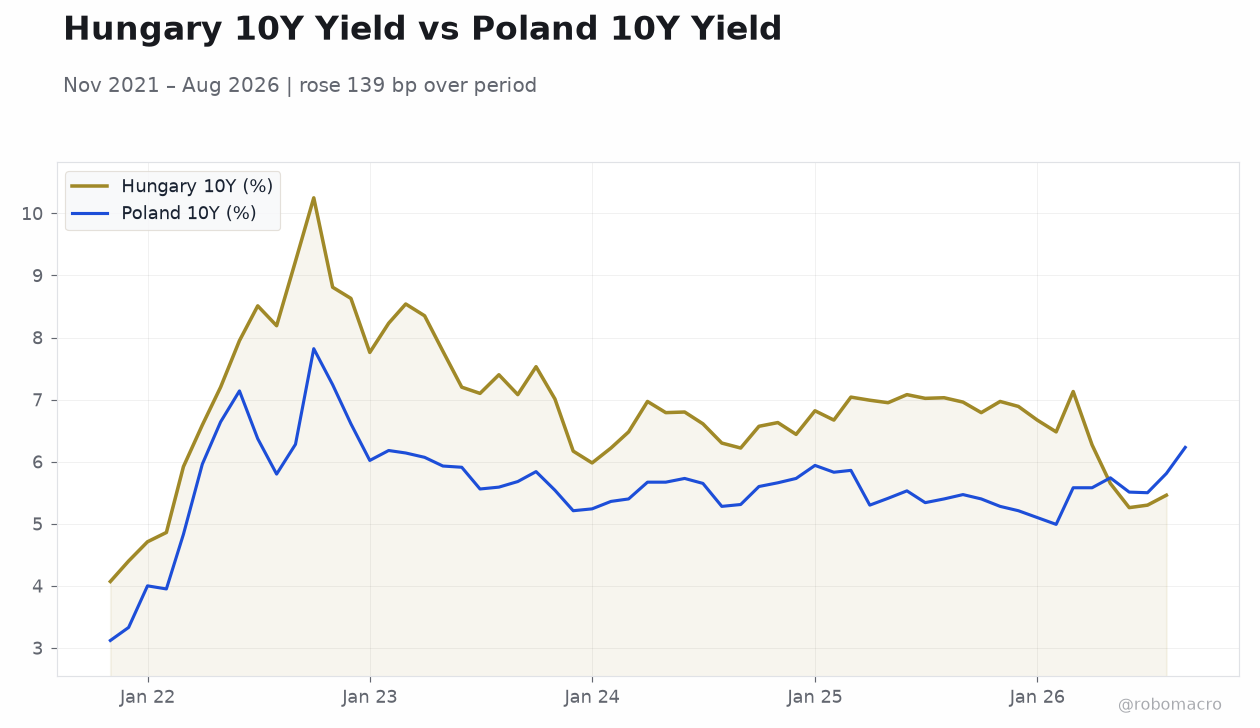 Hungary 10Y Yield vs Poland 10Y Yield | Type: macro_line | Hungary 10Y (%): 5.46 (2026-08-01) | Range: 4.07–10.25 | Trend(6pt): 4.07,7.76,6.48,6.95,5.3,5.46 | Poland 10Y (%): 6.23 (2026-09-01) | Range: 3.12–7.82 | Trend(6pt): 3.12,6.02,5.4,5.41,5.5,6.23
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
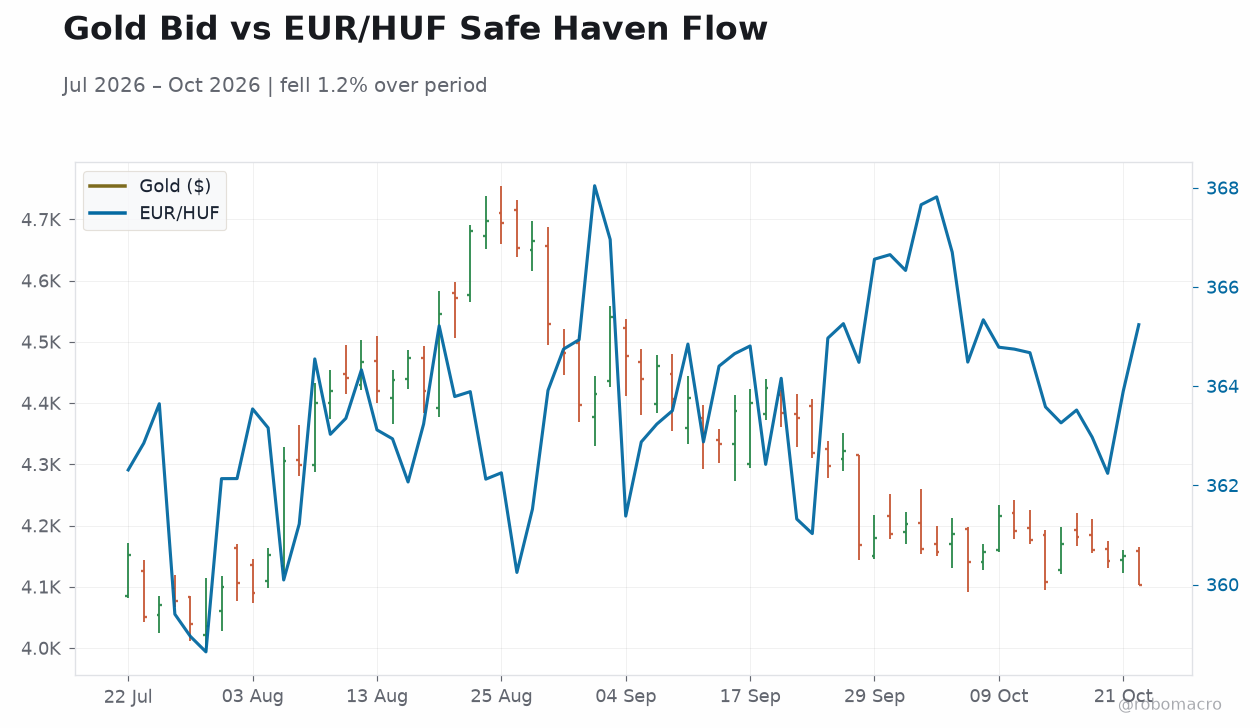
- MNB left its base rate unchanged at 5.50% on October 20, matching consensus; EUR/HUF drifted 0.37% higher to 365.24 as the hold offered no hawkish surprise.
- Polish assets outperformed: iShares Poland rose 1.72% and EUR/PLN slipped 0.19% to 4.36, with NBP confirming September gold purchases toward its 700-tonne target.
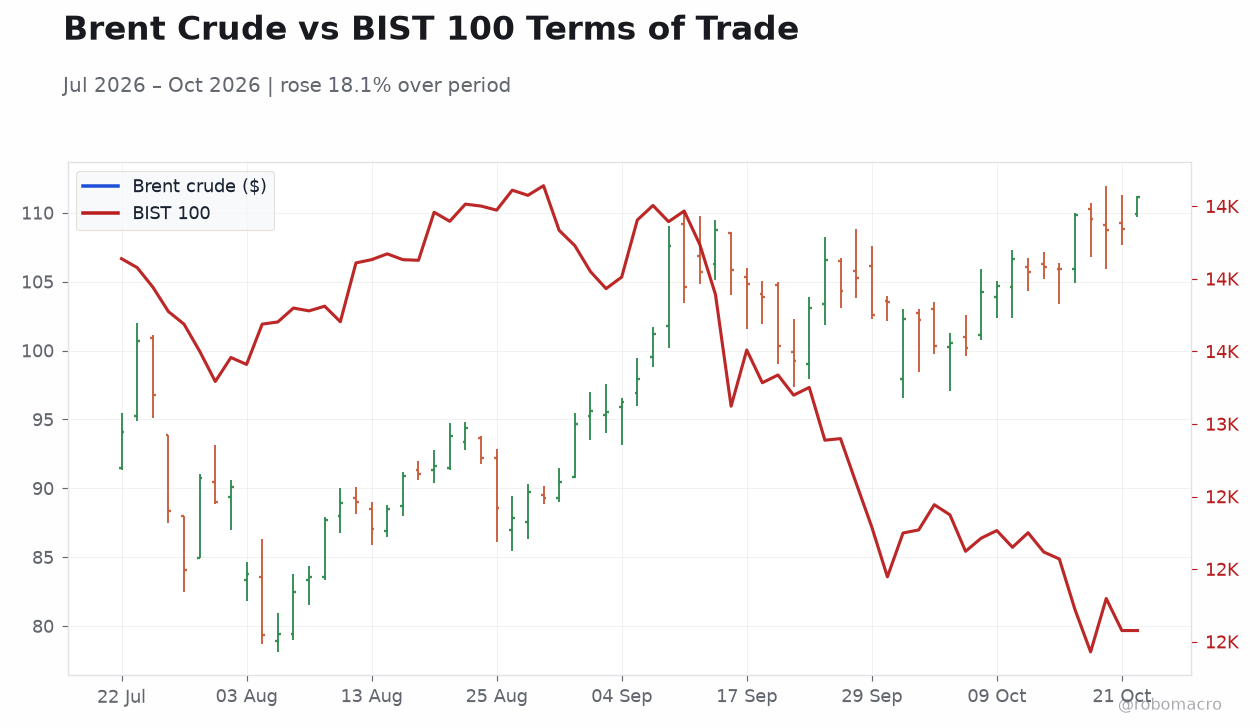
- BIST 100 fell 1.87% to 11,577.10 while Brent crude jumped 2.20% to $111.21, a terms-of-trade headwind for Turkey and a margin positive for regional refiners.
Yesterday's Recap
The dominant regional event was the MNB's rate decision, which printed at 5.50% — unchanged from the prior 5.50% and in line with consensus — leaving Hungary's policy stance firmly on hold. The forint nonetheless weakened, with EUR/HUF rising 0.37% to 365.24, suggesting the market had positioned for a more constructive tone than delivered. Polish markets moved the other way: iShares Poland gained 1.72% and EUR/PLN eased 0.19% to 4.36, supported by NBP's official confirmation of sizeable September gold purchases as it advances toward its declared 700-tonne reserve target — a signal of continued reserve diversification and zloty-supportive credibility.
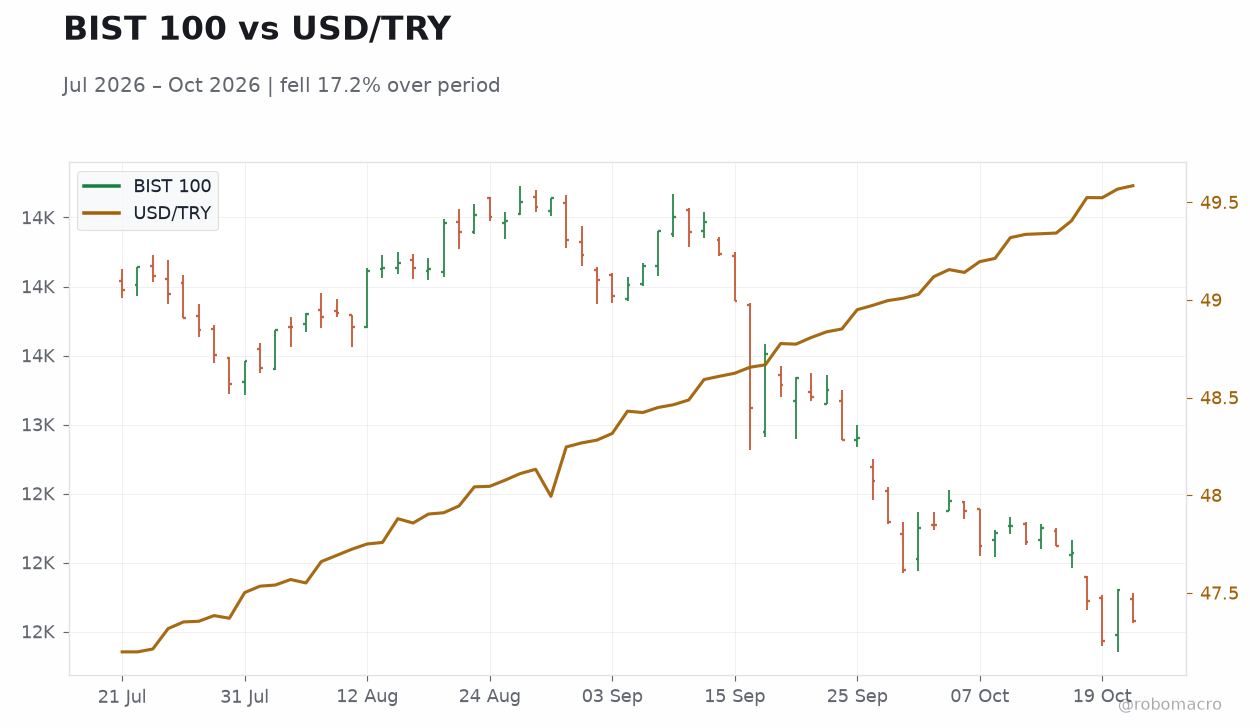
Czech assets were quiet, EUR/CZK edging 0.09% lower to 24.27. Turkey underperformed, with the BIST 100 down 1.87% to 11,577.10 and USD/TRY essentially flat at 49.61 (+0.05%), as the oil rally and global risk tone weighed on Istanbul. Regional fixed income traded without a clean directional signal, and no other high-impact Emerging Europe prints were recorded.
The Day Ahead
The regional calendar is empty for both today (October 22) and tomorrow (October 23), with no scheduled high-impact releases across Poland, Czech Republic, Hungary, Romania or Turkey. Attention therefore shifts to secondary themes: Hungary's 2027 budget details, presented Tuesday, point to tax measures generating roughly HUF 929bn in additional revenue, of which HUF 264bn is earmarked — a fiscal backdrop the MNB will weigh against its inflation path. In Poland, the gold-reserve story and NBP communication will be the main talking points, with the zloty's firm tone likely to draw scrutiny on intervention tolerance.
Romania and Turkey have no top-tier data due, leaving CBRT reserve dynamics and BNR liquidity management as the quiet-day watch items. Expect flows to be driven by global crude and euro-area rates rather than domestic catalysts.
Other Economic Notes
Hungary's institutional backdrop is unusually busy: the MNB revoked the operating licence of Trive Bank and ordered its winding-up, with the National Deposit Insurance Fund stepping in up to the statutory threshold within seven working days — a small-bank cleanup that reinforces the MNB's supervisory posture. ↓ p.2