Emerging Europe Macro Daily(Beta Mode)
Turkey IP Rebounds Ahead of BNR Decision
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| BIST 100 | 11,661.90 | -0.43% |
| iShares Poland | 43.66 | -0.30% |
| EUR/PLN | 4.40 | +0.27% |
| EUR/HUF | 364.07 | +0.56% |
| EUR/CZK | 24.35 | +0.11% |
| USD/TRY | 50.23 | +0.02% |
| Brent Crude | 92.30 | +0.89% |
| Gold | 4,060.40 | +0.75% |
| Bitcoin | 73,744.69 | -1.97% |
| Poland 10Y Govt Yield | - | - |
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Industrial Production Year-over-Year | -1.70 | - | 2.60 |
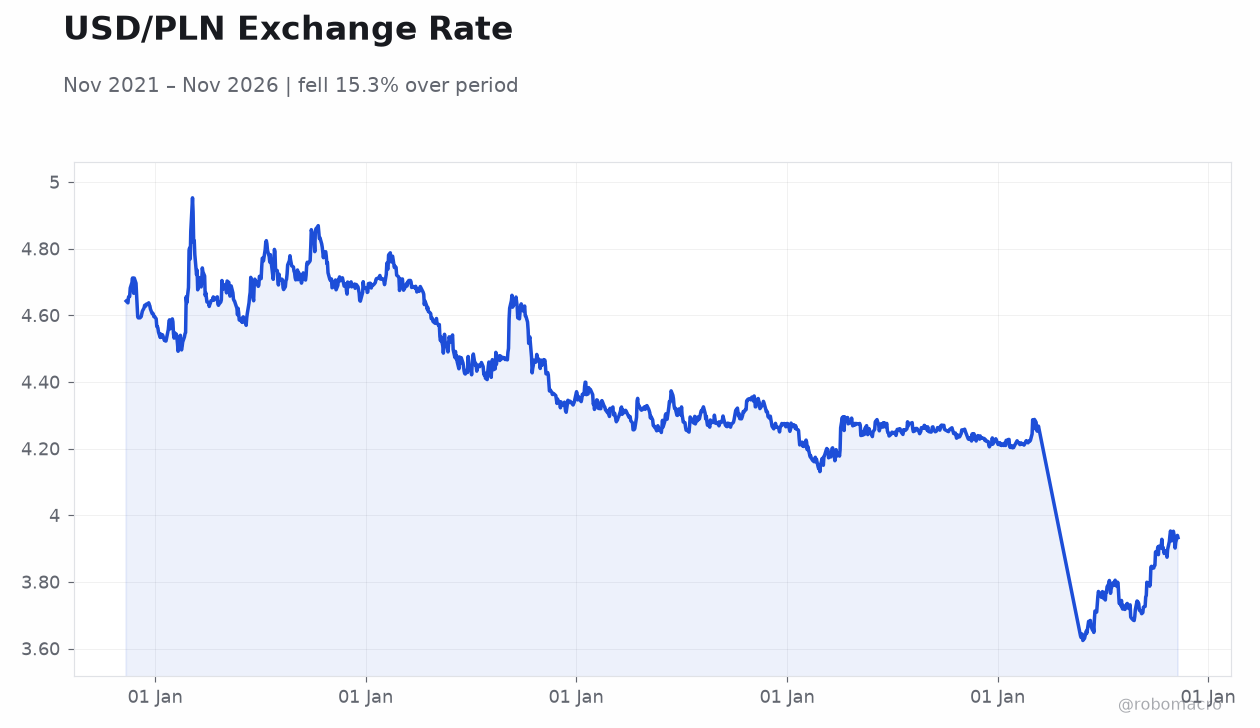
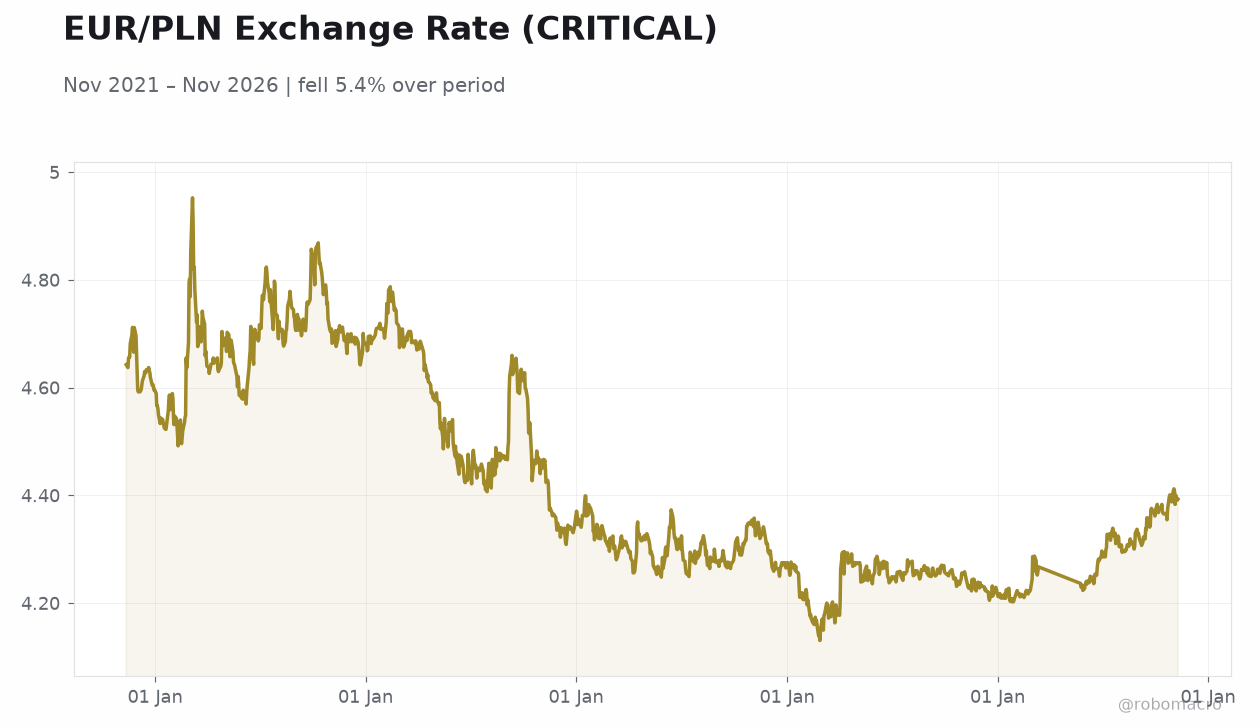 EUR/PLN Exchange Rate (CRITICAL) | Type: macro_line | EUR/PLN Exchange Rate (CRITICAL): 4.393 (2026-11-10) | Range: 4.131–4.952 | Trend(5pt): 4.643,4.711,4.256,4.254,4.393
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-11-12) | |||
| Central Bank Interest Rate Decision | 6.50 | - | 08:00 |
- Turkish industrial production rebounded to +2.6% y/y, reversing the prior -1.7% contraction and offering a rare positive data point for the CBRT's restrictive stance.
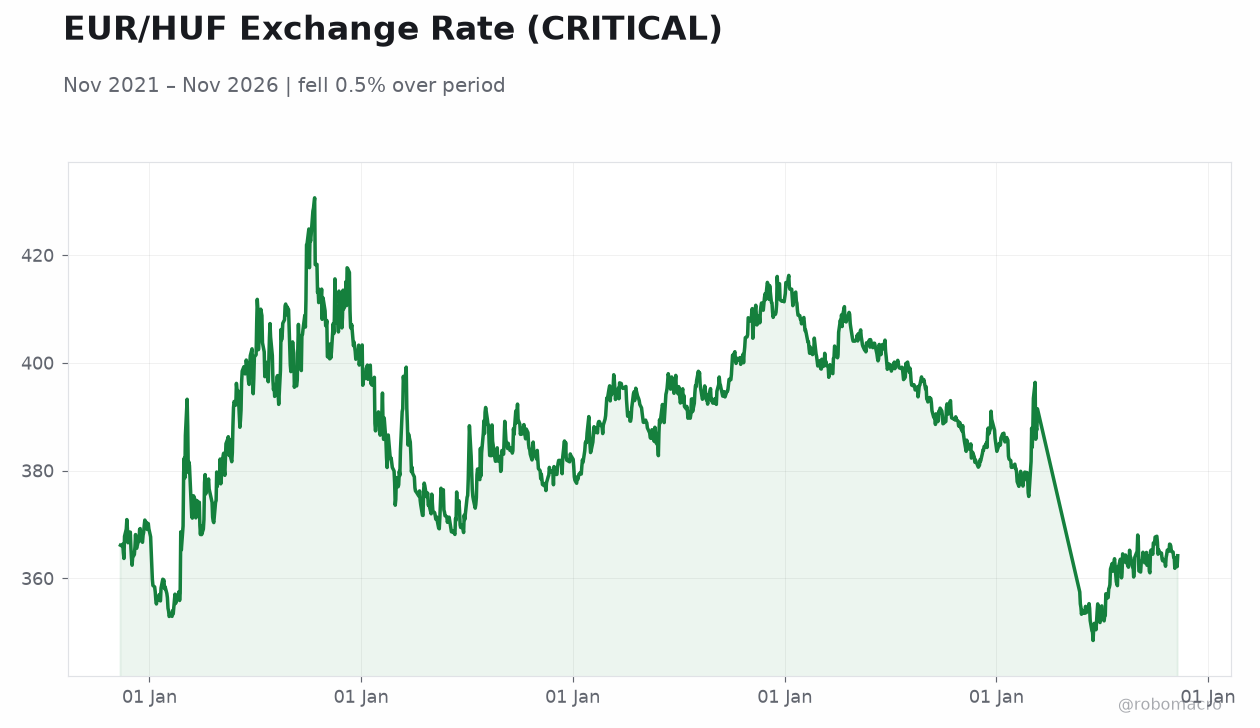
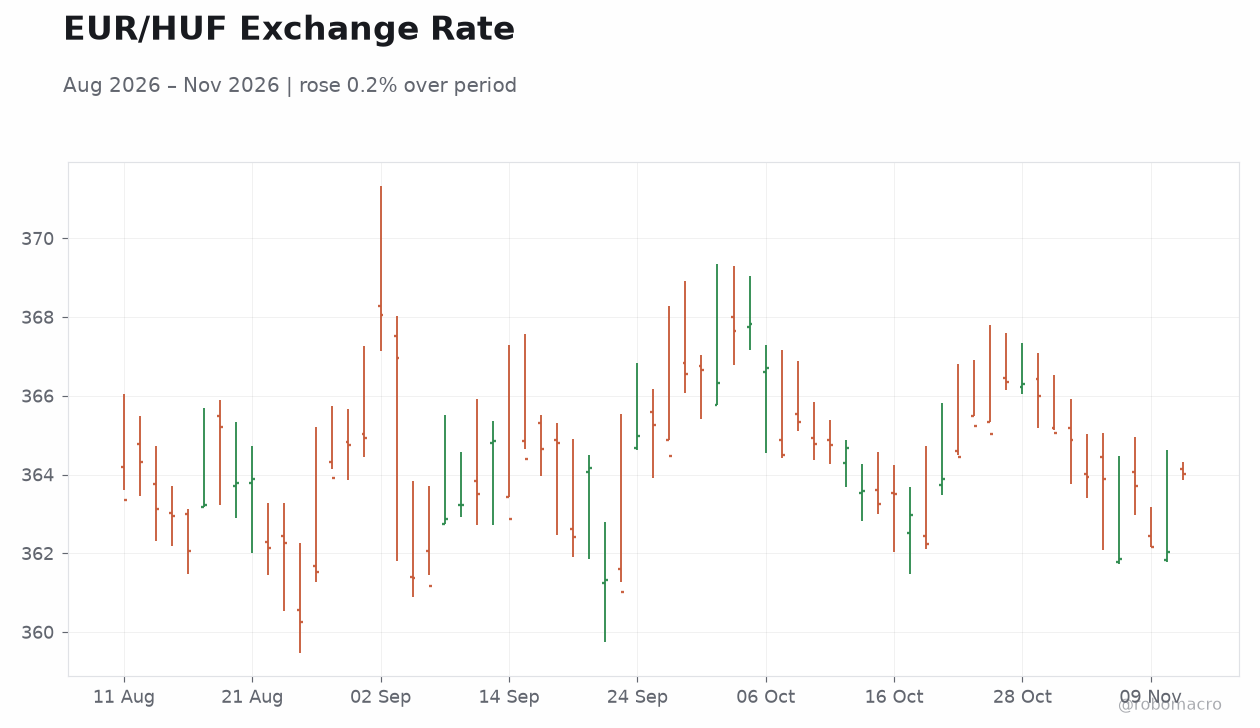
- EUR/HUF climbed 0.56% to 364.07 and EUR/PLN rose 0.27% to 4.40, with the forint underperforming ahead of the November 17 MNB decision.
- Romania's BNR meets Thursday with the 6.50% rate expected unchanged; Poland's Sejm moves toward a Tribunal of State motion against NBP Governor Glapiński, injecting institutional risk into PLN assets.
Yesterday's Recap
Turkey's industrial production printed at +2.6% y/y, a sharp reversal from the prior -1.7% contraction and the day's sole Emerging Europe data release. The rebound suggests Turkish manufacturing is stabilizing after a prolonged period of weak external demand and tight financial conditions, though the CBRT's restrictive stance remains a drag on credit-intensive sectors. Regional FX markets leaned weaker against the euro: EUR/HUF rose 0.56% to 364.07, EUR/PLN added 0.27% to 4.40, and EUR/CZK edged 0.11% higher to 24.35.
The forint's underperformance reflects positioning ahead of the MNB's November 17 meeting, where the base rate is expected to stay at 5.50%. USD/TRY was essentially flat at 50.23, with the lira's managed depreciation continuing at a measured pace. Equities were soft across the region: the BIST 100 fell 0.43% to 11,661.90 and iShares Poland slipped 0.30% to 43.66.
Brent crude advanced 0.89% to $92.30, a headwind for the region's energy-import-dependent economies.
The Day Ahead
Romania's central bank convenes Thursday at 08:00 ET to set its policy rate, with the benchmark expected to remain at 6.50%. The BNR has held steady through a prolonged inflation fight, and with regional peers at or below 5.50%, Romania's real-rate premium remains the widest in the EU bloc. No other Emerging Europe data releases are scheduled, leaving the BNR statement and accompanying commentary as the primary catalyst.
Markets will parse the tone for any signal on the timing of a first cut, particularly given the Leu's relative stability and the government's fiscal consolidation path. Polish markets will continue to digest the Sejm's Constitutional Accountability Committee report on Governor Glapiński, which could shape PLN sentiment into week's end.
Other Economic Notes
Poland's institutional risk premium is creeping higher as the Sejm prepares a decision on the Constitutional Accountability Committee's report concerning NBP Governor Adam Glapiński. The central bank issued a forceful response, stating it is "prepared for every scenario" and arguing that the Tribunal of State proceedings should not be politicized. The dispute matters for markets because it touches NBP independence — a key pillar of Poland's convergence credibility and a factor in the złoty's valuation.
↓ p.2