Eurozone Macro Daily(Beta Mode)
French Debt Warnings Overshadow Eurozone Data
Market Snapshot
| Asset | Level | Change |
|---|---|---|
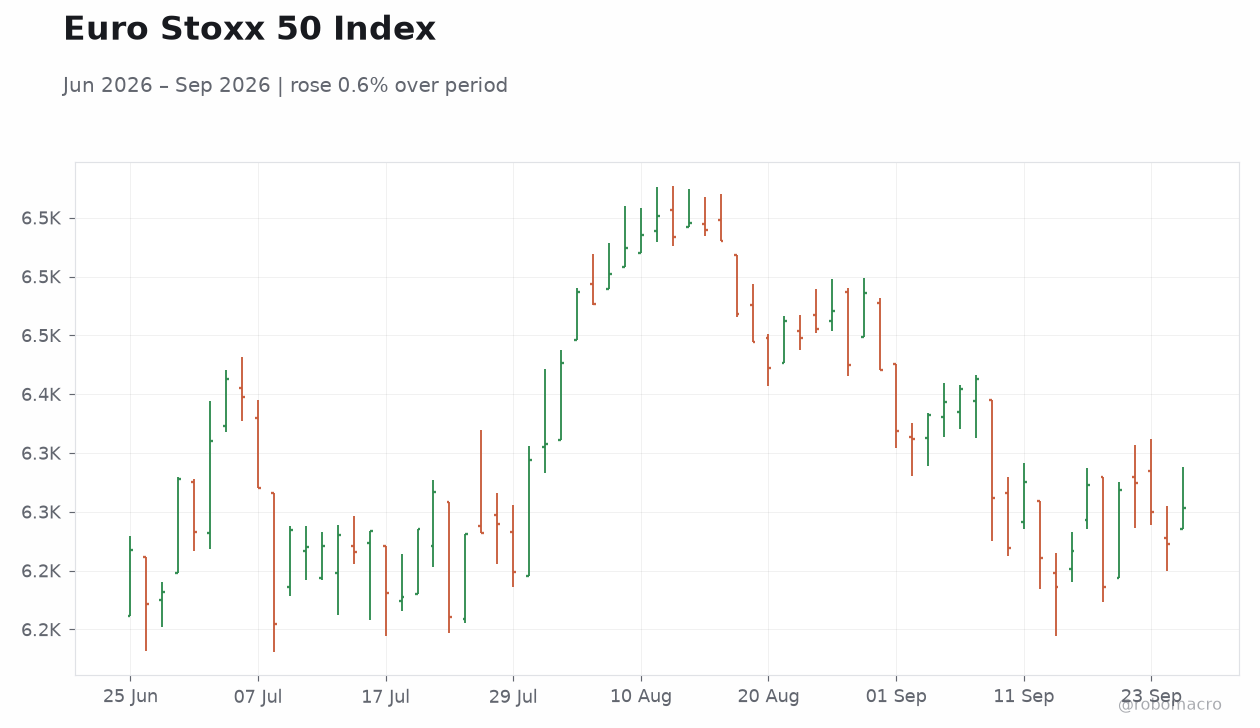
| Euro Stoxx 50 | 6,302.82 | +0.48% |
| DAX | 25,408.64 | +0.56% |
| CAC 40 | 8,077.80 | -0.04% |
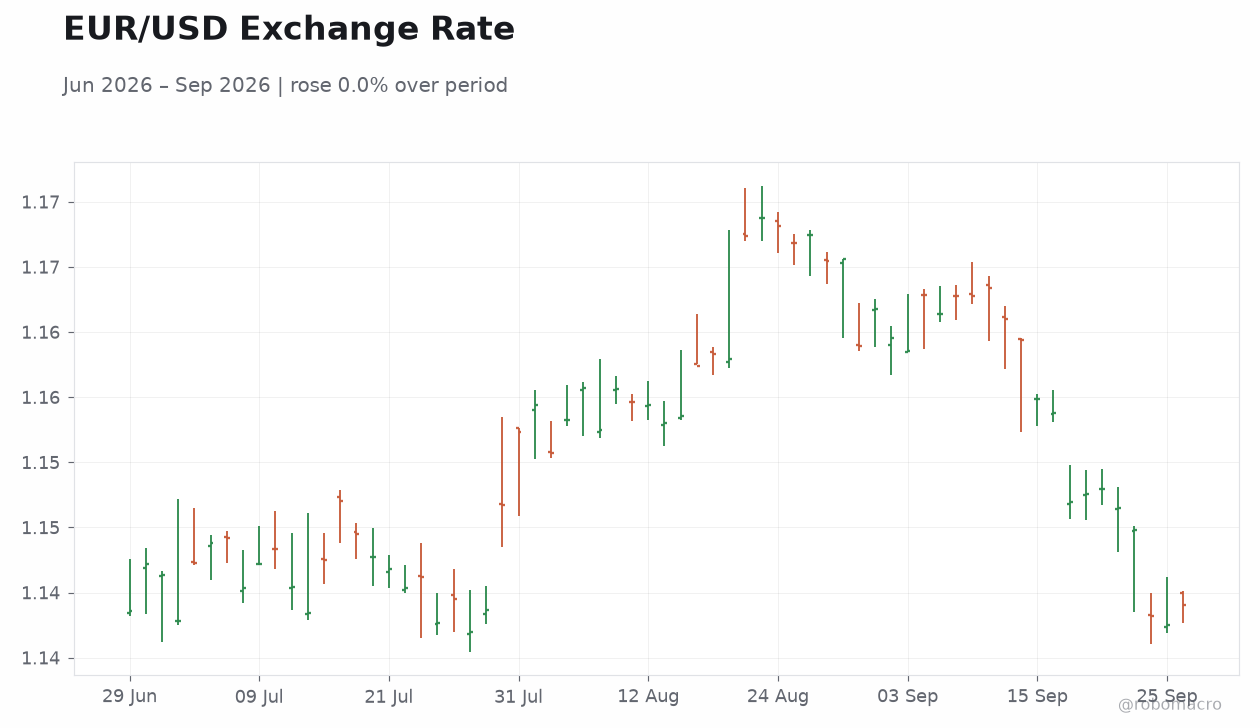
| EUR/USD | 1.14 | +0.13% |
| EUR/GBP | 0.86 | +0.15% |
| EUR/JPY | 179.64 | -0.55% |
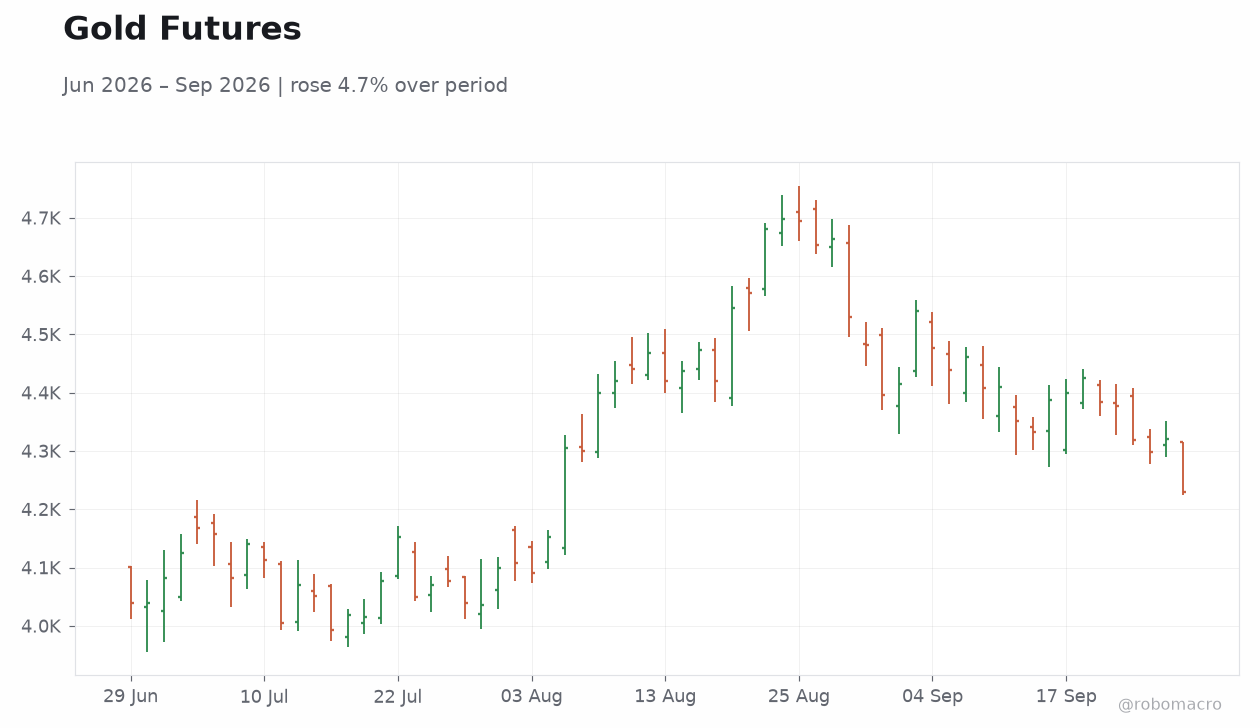
| Gold | 4,230.40 | -2.10% |
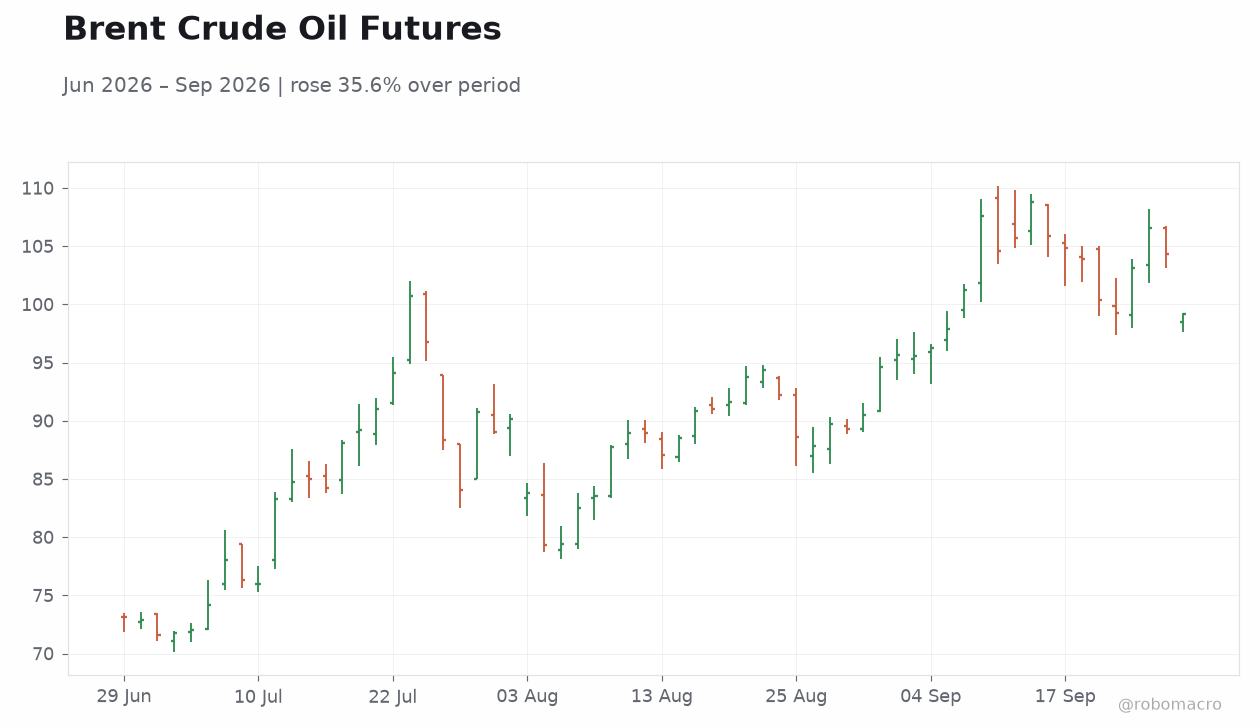
| Brent Crude | 99.13 | -4.98% |
| Bitcoin | 83,508.34 | -1.06% |
| German 2Y Bund | 3.28% | -2 bp |
| German 10Y Bund | 3.63% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
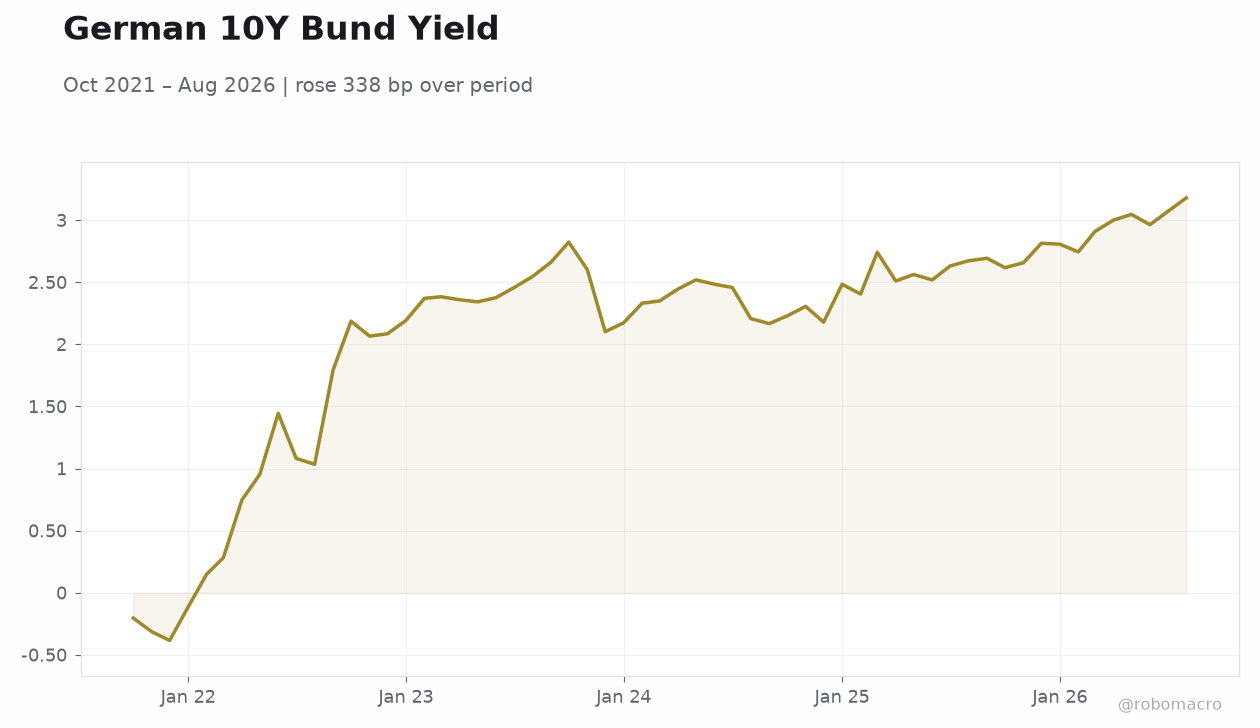 German 10Y Bund Yield | Type: macro_line | Yield %: 3.18 (2026-08-01) | Range: -0.3843–3.18 | Trend(6pt): -0.2043,2.085,2.332,2.51,2.964,3.18
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Inflation Rate Month-over-Month Preliminary | 0.70 | - | 23:00 |
| Inflation Rate Year-over-Year Preliminary | 4.30 | 4.70 | 23:00 |
| Unemployment Benefit Claims | 21,500 | - | 02:00 |
| Business Confidence Index | -3.90 | - | 02:00 |
| Retail Sales Month-over-Month | -3.40 | 1.40 | 22:00 |
| Retail Sales Year-over-Year | -2.50 | - | 22:00 |
| Inflation Rate Year-over-Year Preliminary | 2.40 | - | 22:45 |
| Inflation Rate Month-over-Month Preliminary | 0.70 | -0.50 | 22:45 |
| Headline Unemployment Rate | 6.40 | 6.40 | 23:55 |
| Unemployed Persons Level | 3.0m | - | 23:55 |
- Banque de France stresses no ECB fix for sovereign debt risks
- Spain and France inflation prints lead heavy data calendar tonight
- Euro Stoxx 50 rises 0.48% while DAX gains 0.56% on thin volumes
Yesterday's Recap
No Eurozone data releases occurred on 27 September across Germany, France, Italy or Spain. Equity markets closed mixed with the Euro Stoxx 50 advancing 0.48% to 6,302.82 and the DAX rising 0.56% to 25,408.64 while the CAC 40 slipped 0.04% to 8,077.80. EUR/USD gained 0.13% to 1.14 and EUR/GBP added 0.15% to 0.86.
German 2-year Bund yields fell 2 bp to 3.28% and the 10-year yield edged 1 bp higher to 3.63%. Brent crude dropped 4.98% to 99.13 amid broader commodity weakness. Coverage focused on whether Germany’s fiscal package is reaching the real economy and Volkswagen’s ongoing restructuring talks.
The Day Ahead
Spain releases preliminary inflation MoM and YoY figures at 23:00, followed by France unemployment claims and business confidence at 02:00. Germany retail sales MoM and YoY appear at 22:00 with unemployment rate and change data at 23:55. France inflation MoM and YoY prints at 22:45 carry high market impact and will shape near-term ECB expectations.
Italy business and consumer confidence plus preliminary inflation YoY follow at 00:00-01:00. Germany inflation MoM/YoY preliminary at 04:00 and S&P Global manufacturing PMIs for Spain, Italy and Germany close the session and will test resilience narratives.
Other Economic Notes
Banque de France Governor Moulin warned that France cannot rely on the ECB to resolve its fiscal deterioration and must cut spending ahead of the 2027 election. German reporting questions whether the fiscal package has begun supporting activity while Volkswagen faces domestic pushback on job reductions. Eurozone corporate lending growth has slowed as higher borrowing costs filter through.
Broader sentiment remains supported by resilient activity readings yet inflation at 3.20% YoY keeps policy vigilance elevated.
Global Macro News
Brent’s 4.98% decline to 99.13 reduces imported energy pressure on Eurozone inflation but highlights geopolitical supply risks. Gold’s 2.10% drop to 4,230.40 signals reduced safe-haven demand. EUR/JPY fell 0.55% to 179.64 as yen strength weighed on crosses.
Global equity tone stayed constructive despite commodity weakness, supporting peripheral spreads. U.S. data focus later in the week will influence EUR/USD direction alongside domestic inflation prints.
↓ p.2