Eurozone Macro Daily(Beta Mode)
Bunds Ease as Equities Rally, France in Focus
Market Snapshot
| Asset | Level | Change |
|---|---|---|
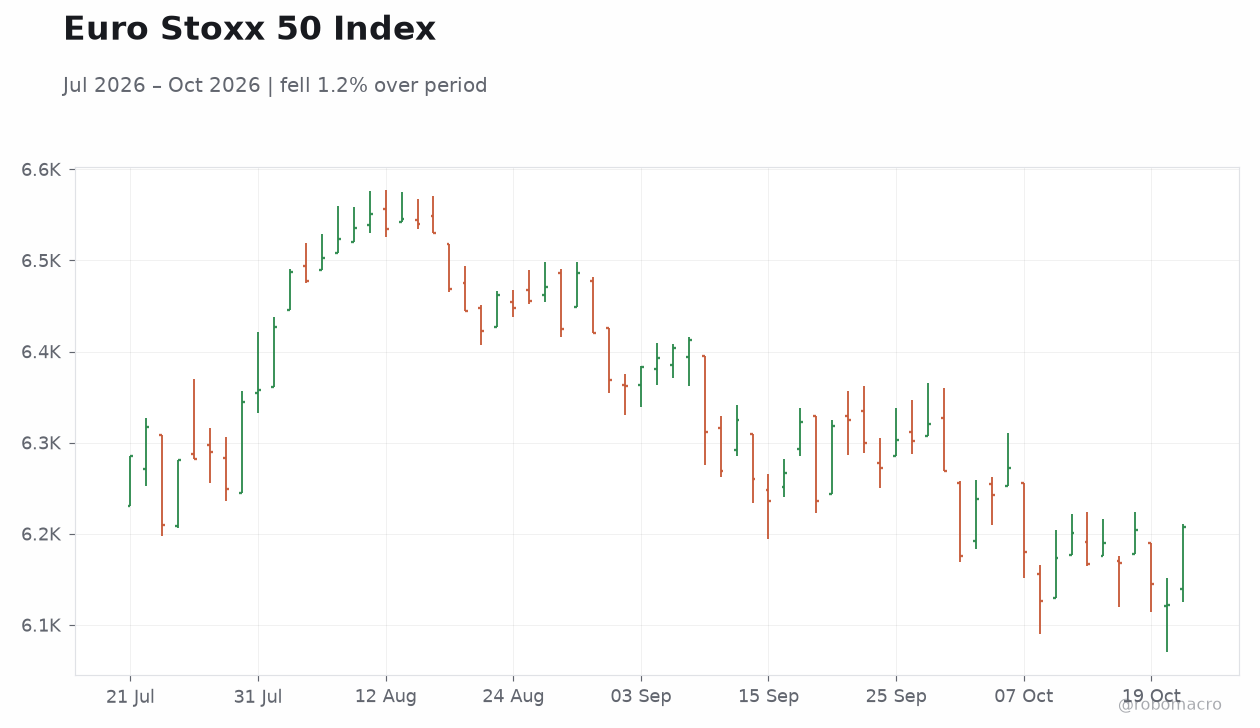
| Euro Stoxx 50 | 6,207.52 | +1.40% |
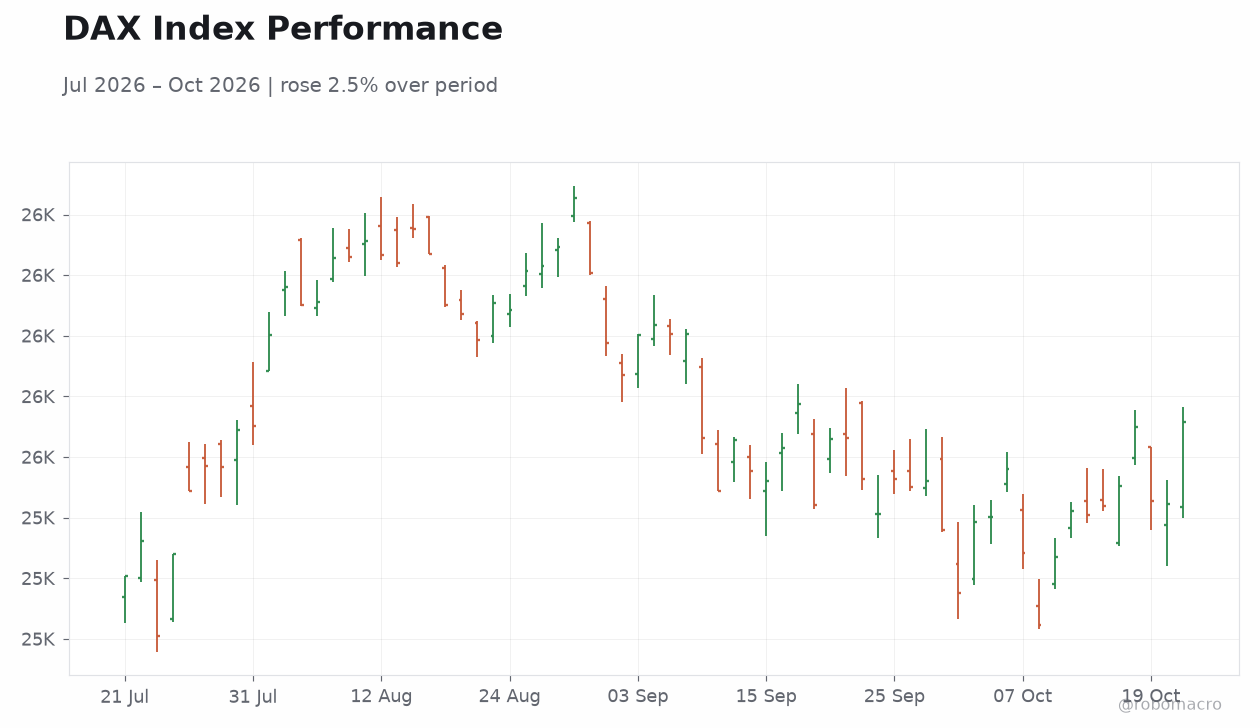
| DAX | 25,645.04 | +1.35% |
| CAC 40 | 7,921.68 | +1.06% |
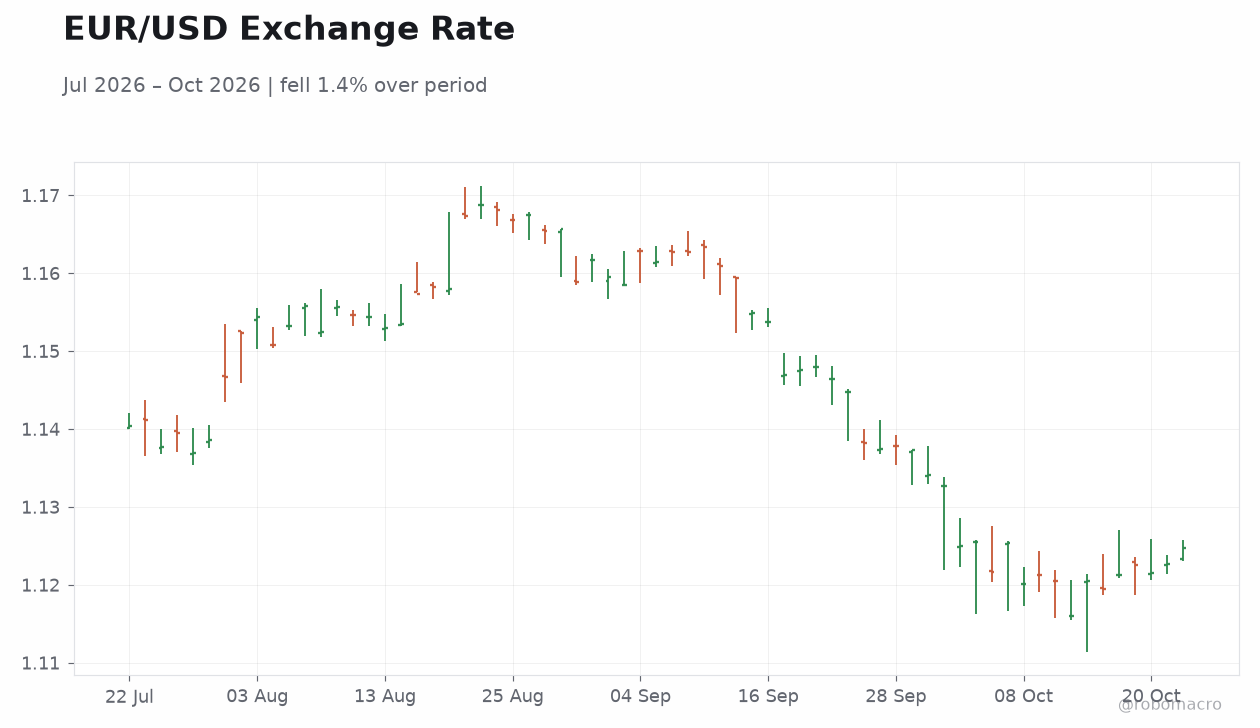
| EUR/USD | 1.12 | +0.17% |
| EUR/GBP | 0.84 | -0.03% |
| EUR/JPY | 177.33 | -0.19% |
| Gold | 4,106.30 | -1.05% |
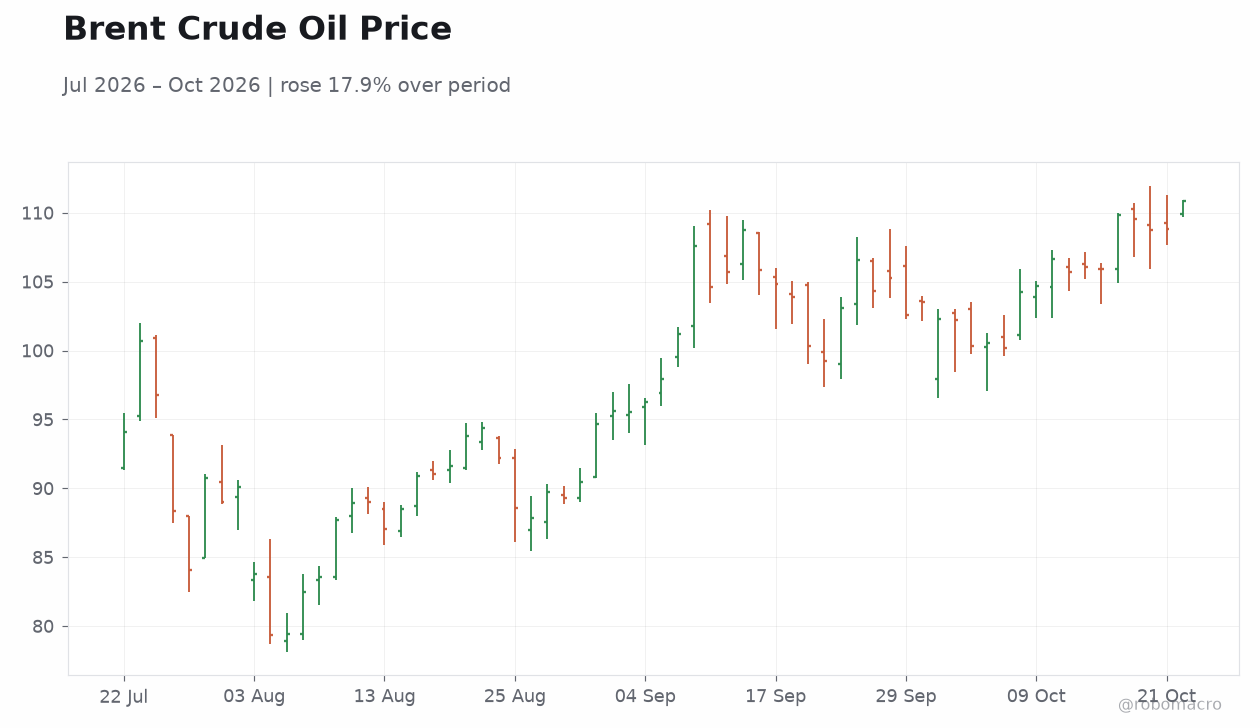
| Brent Crude | 110.89 | +1.90% |
| Bitcoin | 82,826.87 | -0.14% |
| German 2Y Bund | 3.07% | 0 bp |
| German 10Y Bund | 3.44% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
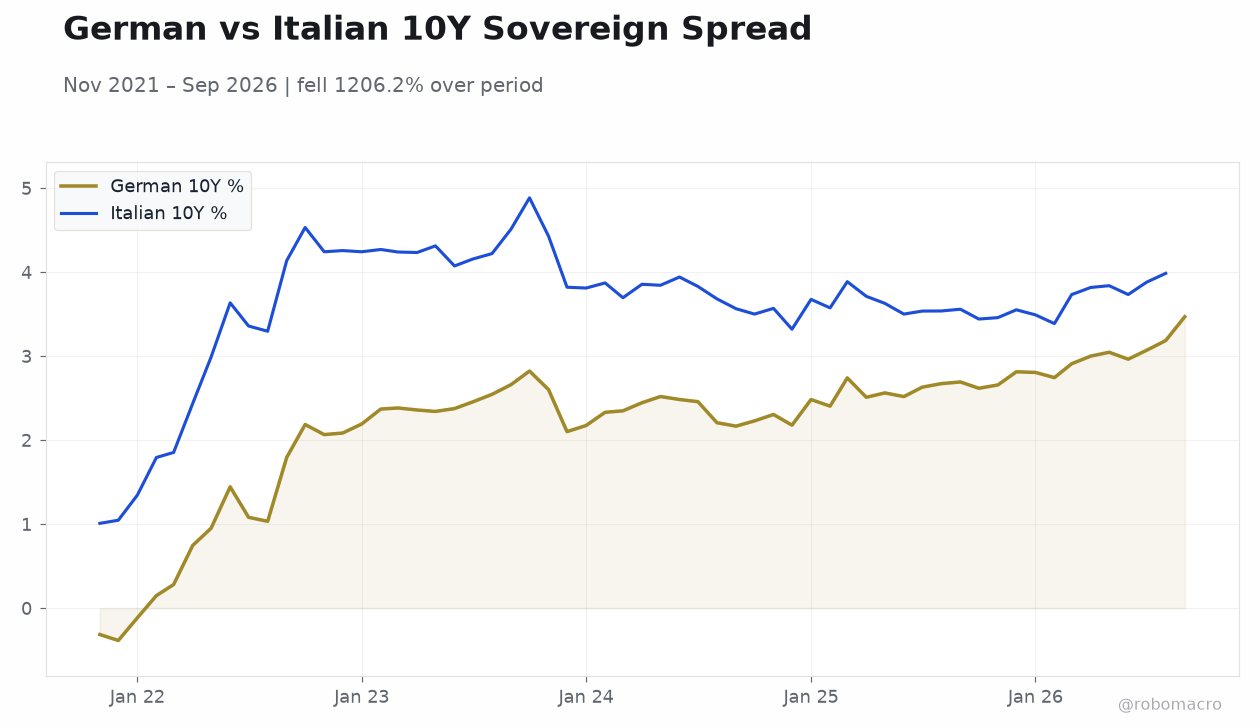 German vs Italian 10Y Sovereign Spread | Type: macro_line | German 10Y %: 3.47 (2026-09-01) | Range: -0.3843–3.47 | Trend(6pt): -0.3136,2.193,2.349,2.563,3.07,3.47 | Italian 10Y %: 3.986 (2026-08-01) | Range: 1.01–4.885 | Trend(6pt): 1.01,4.243,3.696,3.629,3.881,3.986
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Euro area risk assets rallied yesterday, with the Euro Stoxx 50 up 1.40% and the DAX up 1.35%, while the 10-year Bund yield eased 1 bp to 3.44%.
- The Bundesbank said Germany's economy likely stagnated in Q3, and German inflation reached 3.3% in September.
- France remains the key idiosyncratic risk, with PMIs and a credit rating review due over the weekend keeping EUR/USD pinned near 1.12.
Yesterday's Recap
Euro area equities rallied yesterday, with the Euro Stoxx 50 gaining 1.40% to 6,207.52, the DAX rising 1.35% to 25,645.04 and the CAC 40 up 1.06% to 7,921.68. Rates were steady to slightly lower, with the German 10-year Bund yield easing 1 bp to 3.44% while the 2-year held at 3.07%. EUR/USD edged up 0.17% to 1.12, though EUR/GBP slipped 0.03% to 0.84 and EUR/JPY fell 0.19% to 177.33.
The Bundesbank said Germany's economy likely stagnated in the third quarter, a downbeat assessment that nonetheless did little to dent risk appetite. German inflation reached 3.3% in September, keeping pressure on the ECB's price-stability mandate. Brent crude jumped 1.90% to $110.89, while gold fell 1.05% to $4,106.30.
The session's tone was constructive for equities but cautious on the euro, with France's fiscal trajectory dominating the narrative.
The Day Ahead
The calendar is light today, with no major euro area data releases scheduled, leaving markets to trade on positioning and headlines. Attention turns to tomorrow's flash PMIs, which will be the first read on October activity and a key input for the ECB's December deliberations. France's credit rating review over the weekend is the dominant event risk, with any downgrade likely to pressure OATs and the euro at the open next week.
ECB speakers may add color on the policy path, though no Governing Council decision is due. With Bund yields near 3.44% and EUR/USD holding above 1.12, traders will watch for any cracks in peripheral spreads.
Other Economic Notes
Germany's investment summit in Berlin drew €230bn in pledges, with Amazon, Anthropic and Boeing among the commitments, a rare positive headline for Europe's largest economy. KKR's co-head of European private equity said the firm is "very positive on Germany," citing a safe and stable investment environment. The Bundesbank's stagnation call underscores the gap between headline investment announcements and near-term activity.
↓ p.2