Eurozone Macro Daily(Beta Mode)
Bunds Rally as German Retail Sales Slump
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Euro Stoxx 50 | 6,176.06 | +0.73% |
| DAX | 25,818.21 | -0.85% |
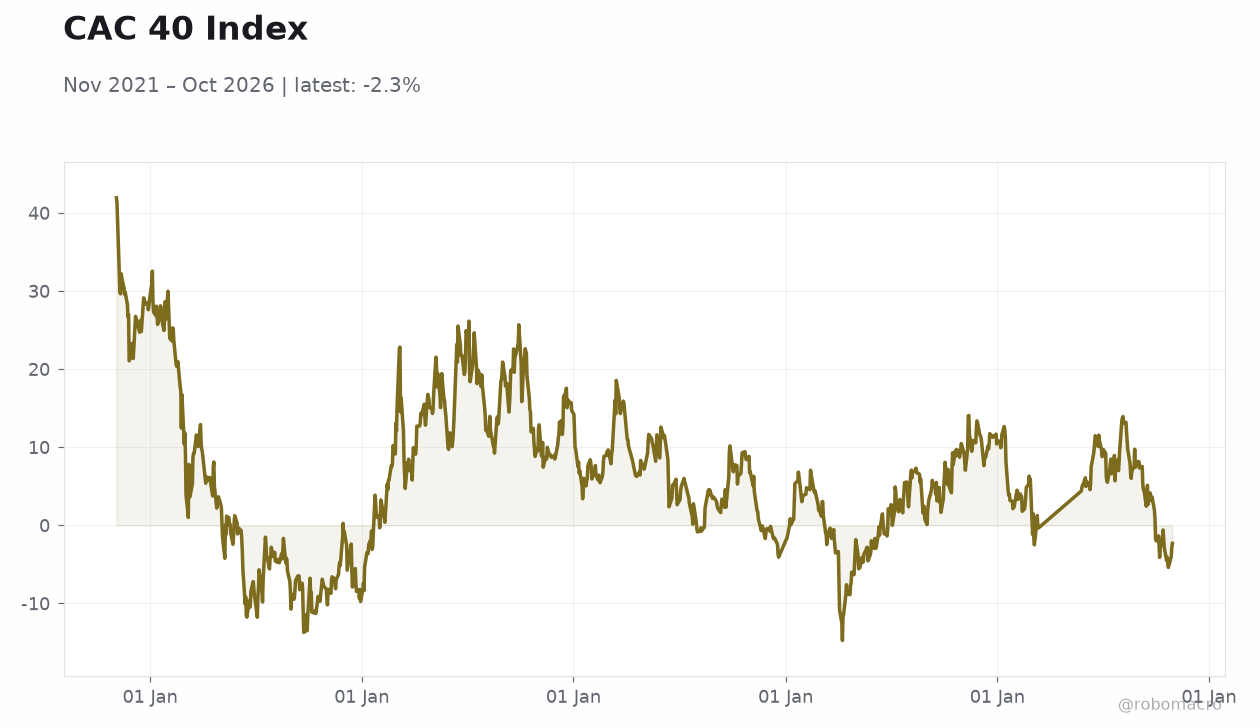
| CAC 40 | 8,047.69 | +0.98% |
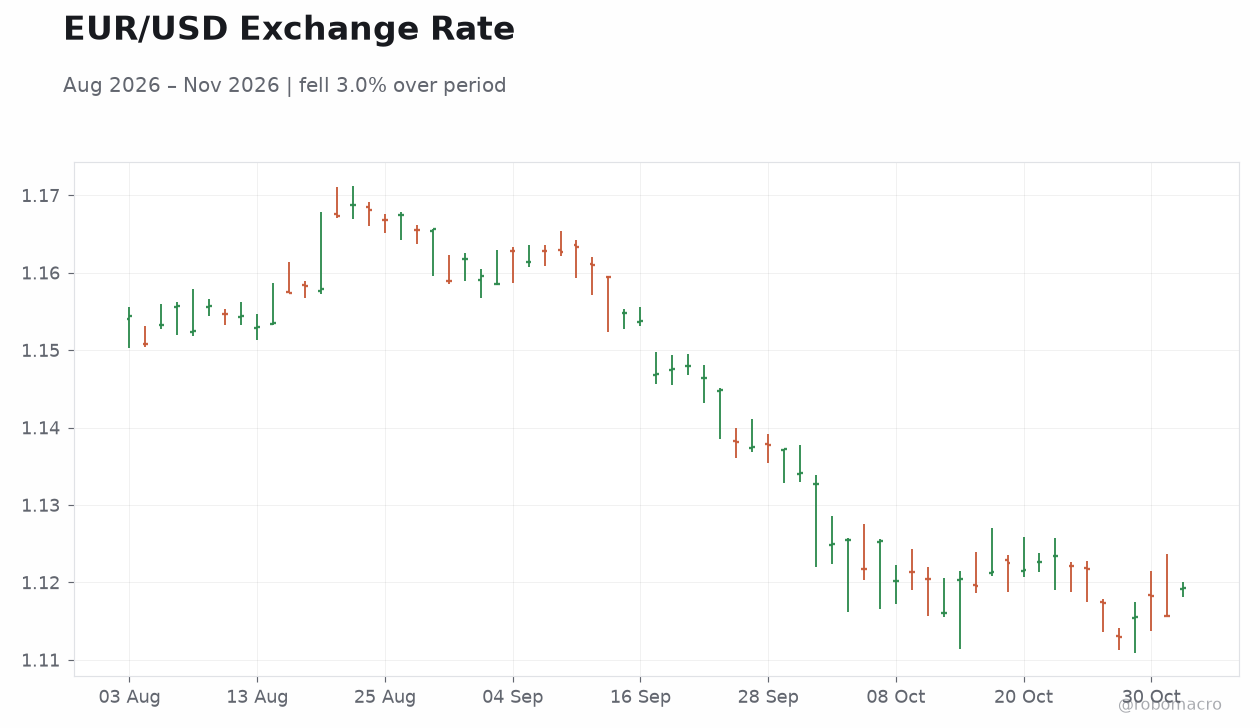
| EUR/USD | 1.12 | +0.33% |
| EUR/GBP | 0.83 | +0.13% |
| EUR/JPY | 176.68 | +0.43% |
| Gold | 3,969.60 | +1.81% |
| Brent Crude | 104.77 | -10.94% |
| Bitcoin | 76,792.42 | -1.86% |
| German 2Y Bund | 3.03% | -3 bp |
| German 10Y Bund | 3.37% | -3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Retail Sales Month-over-Month | 1.20 | 0.40 | -2 |
| Retail Sales Year-over-Year | -0.30 | - | -2.30 |
| S&P Global Manufacturing PMI Index | 51 | 50.80 | 52.20 |
| S&P Global Manufacturing PMI Index | 50.40 | 50.20 | 49.40 |
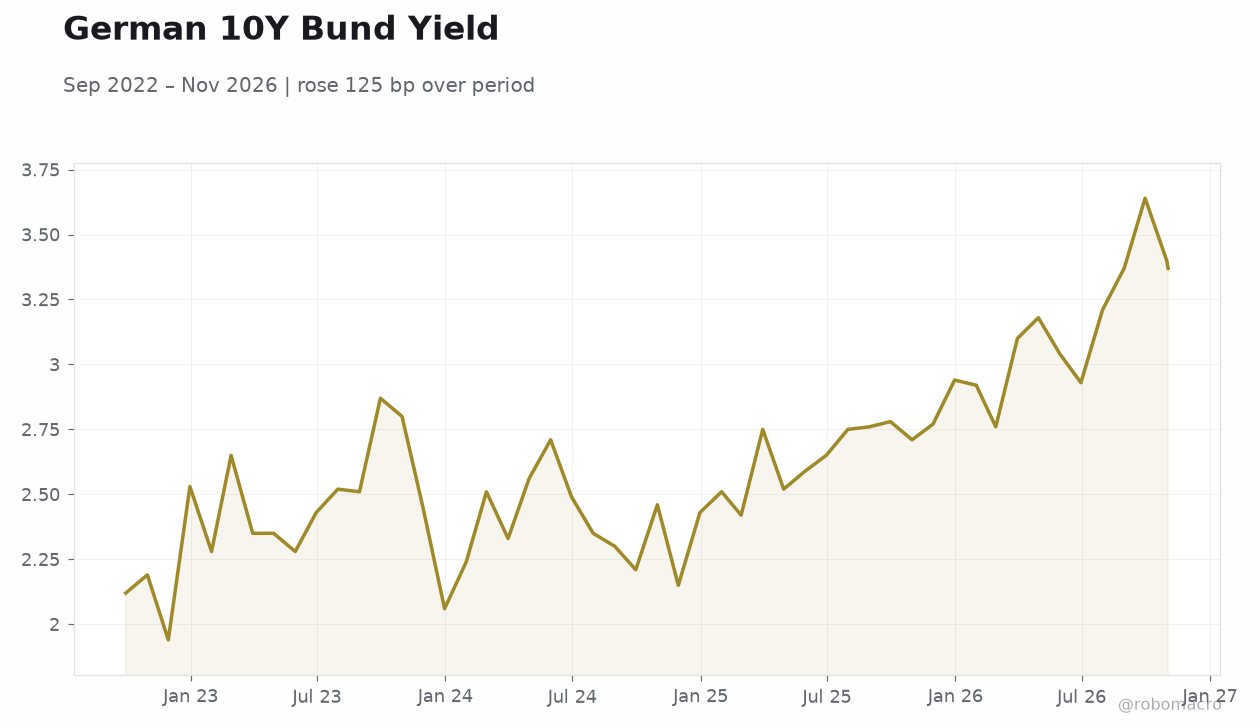 German 10Y Bund Yield | Type: macro_line | German 10Y yield (%): 3.37 (2026-11-02) | Range: 1.94–3.64 | Trend(6pt): 2.12,2.87,2.21,2.78,3.64,3.37
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-11-04) | |||
| Inflation Rate Year-over-Year Preliminary | 3.40 | - | 00:30 |
| Unemployment Level Change | 23,587 | 25,300 | 03:00 |
| S&P Global Services PMI | 58.30 | 57.20 | 03:15 |
| S&P Global Services PMI | 51.70 | - | 03:45 |
- German retail sales plunged 2.0% m/m and 2.3% y/y in November, far below the 0.4% consensus, signaling consumer weakness in the bloc's largest economy.
- Spanish manufacturing PMI beat at 52.2 while Italian manufacturing slipped into contraction at 49.4, highlighting divergent periphery momentum.
- Bunds rallied with 2Y and 10Y yields each easing 3 bp to 3.03% and 3.37%, while EUR/USD firmed 0.33% to 1.12 despite soft German data.
Yesterday's Recap
German retail sales disappointed sharply, contracting 2.0% m/m against a 0.4% consensus and -2.3% y/y, underscoring fragile household demand in the eurozone's largest economy. Spanish manufacturing PMI beat expectations at 52.2 versus 50.8 consensus, extending robust periphery momentum. Italian manufacturing PMI fell to 49.4 from 50.4, slipping into contraction and diverging from Spain's strength.
Markets reflected the mixed picture: the Euro Stoxx 50 gained 0.73% and CAC 40 rose 0.98%, while the DAX lagged, falling 0.85% on German consumer weakness. Rates moved lower, with the German 2Y Bund yield easing 3 bp to 3.03% and the 10Y down 3 bp to 3.37%. EUR/USD firmed 0.33% to 1.12, and Brent crude collapsed 10.94% to $104.77.
The Day Ahead
Wednesday's calendar is dominated by periphery data, with Dutch preliminary inflation for November due at 00:30 ET, following a prior 3.4% y/y print. Spain releases unemployment change at 03:00 ET, with consensus at 25,300 versus a prior 23,587. Spanish services PMI follows at 03:15 ET, expected at 57.2 versus the prior 58.3, a still-robust but moderating reading.
Italian services PMI is due at 03:45 ET, with no consensus published against a prior 51.7. No major ECB speakers or core eurozone releases are scheduled, leaving periphery services and Dutch inflation as the key directional inputs.
Other Economic Notes
France's fiscal trajectory remains the dominant sovereign risk theme, with ECB officials publicly pressing Paris to consolidate. Irish central bank governor Gabriel Makhlouf said French politicians need to "get on and fix" the economy's problems, ruling out immediate ECB support. French growth stagnation and debt concerns are increasingly framed as a drag on the broader eurozone recovery.
Meanwhile, Germany unveiled a blueprint to become a "sovereign AI nation" by 2030, signaling a policy pivot toward industrial competitiveness. Alstom's second outlook cut of 2026, driven by German project execution problems, adds to the industrial malaise narrative.