Eurozone Macro Daily(Beta Mode)
Risk Rally Masks Weak German Demand
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Euro Stoxx 50 | 6,265.71 | +1.97% |
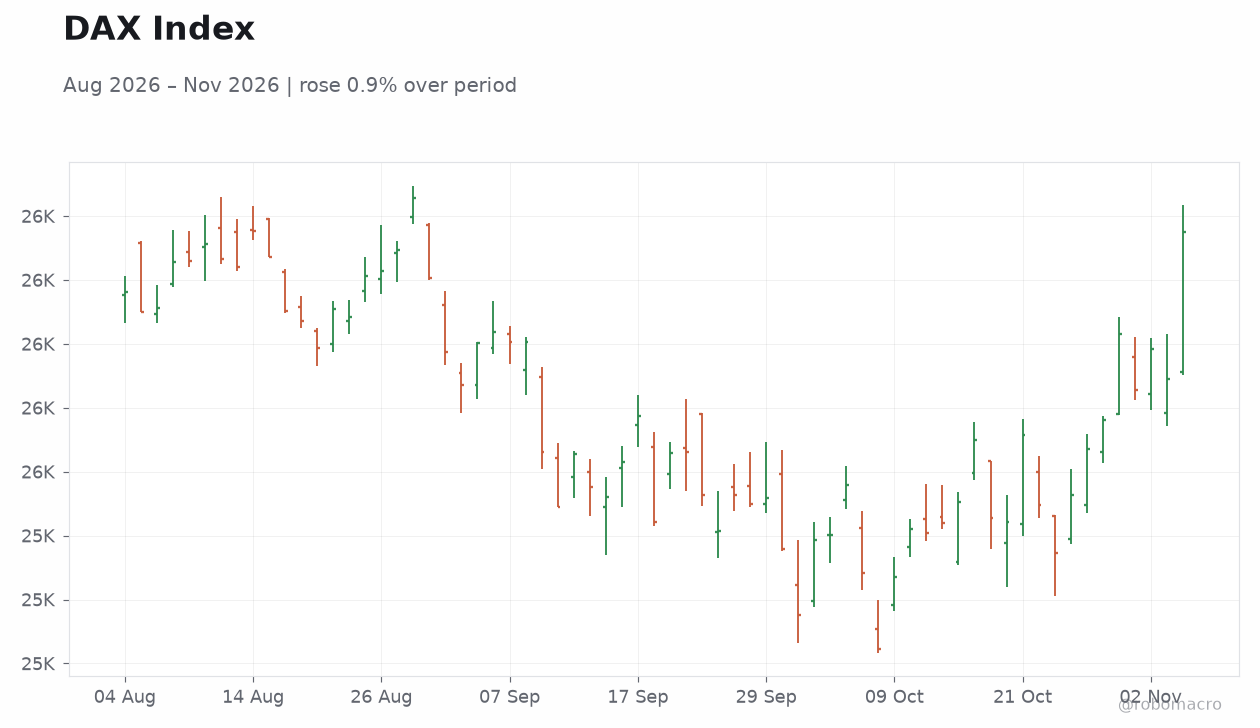
| DAX | 26,437.67 | +2.22% |
| CAC 40 | 8,177.89 | +1.96% |
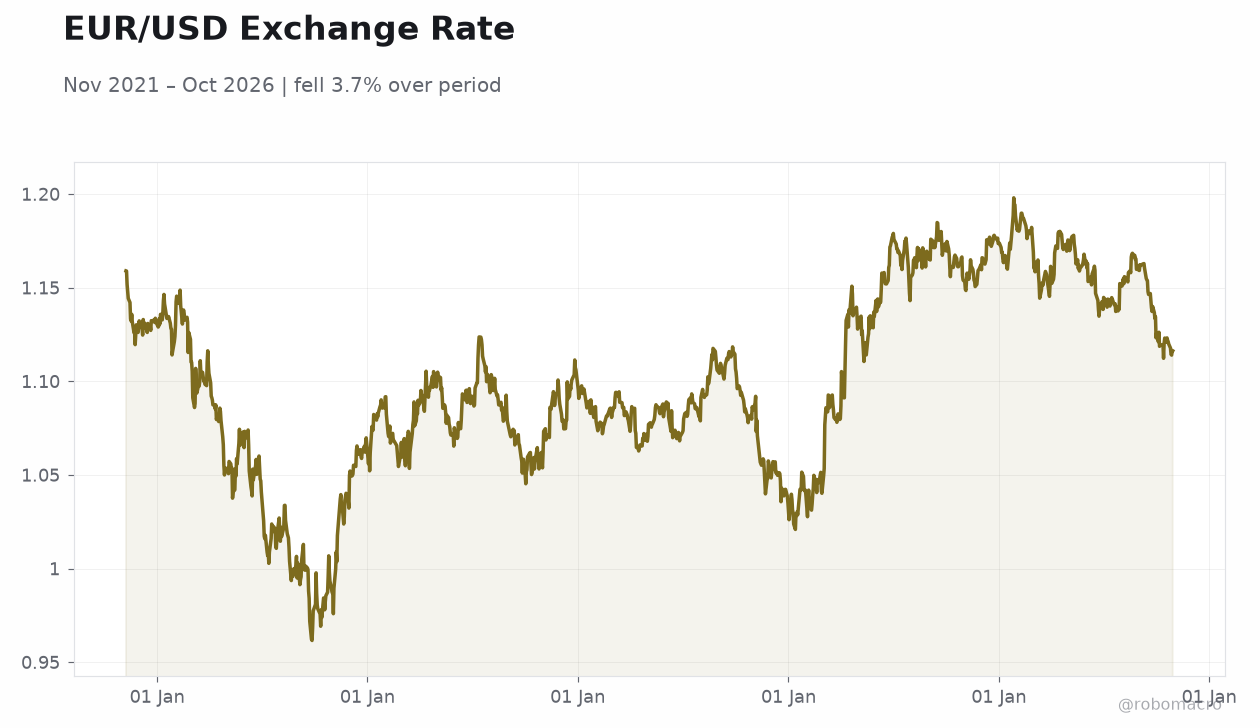
| EUR/USD | 1.13 | +0.52% |
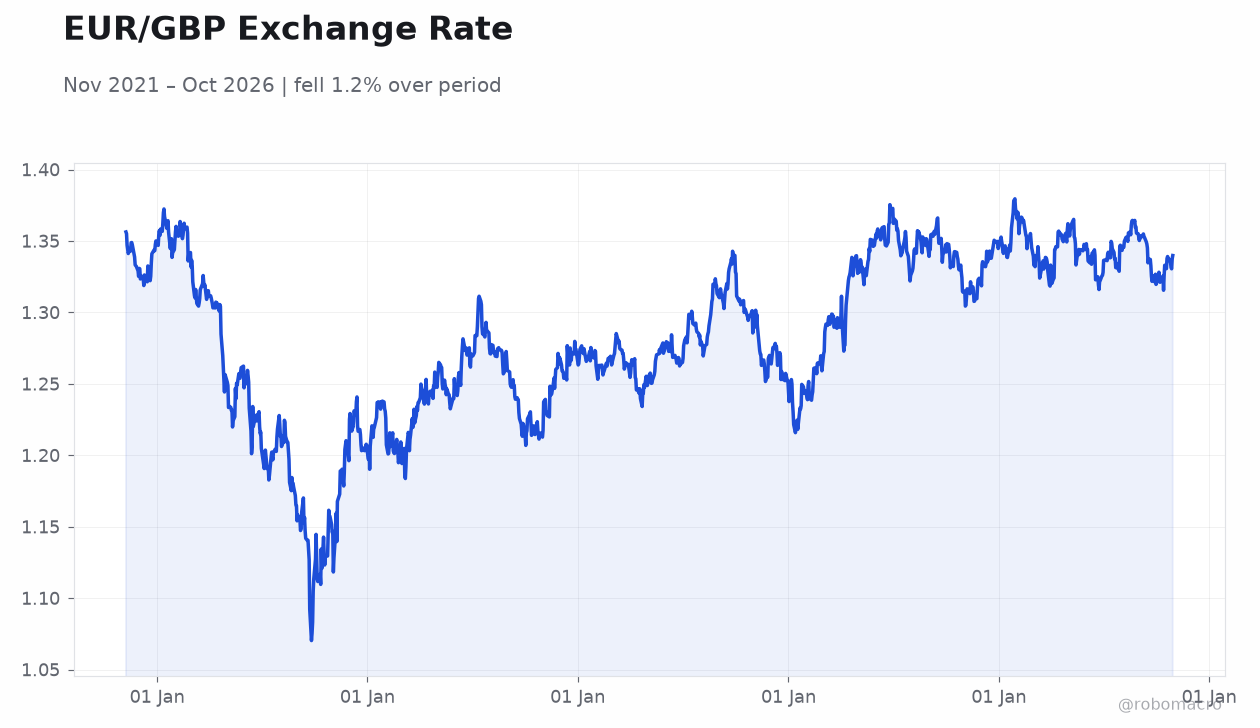
| EUR/GBP | 0.83 | +0.07% |
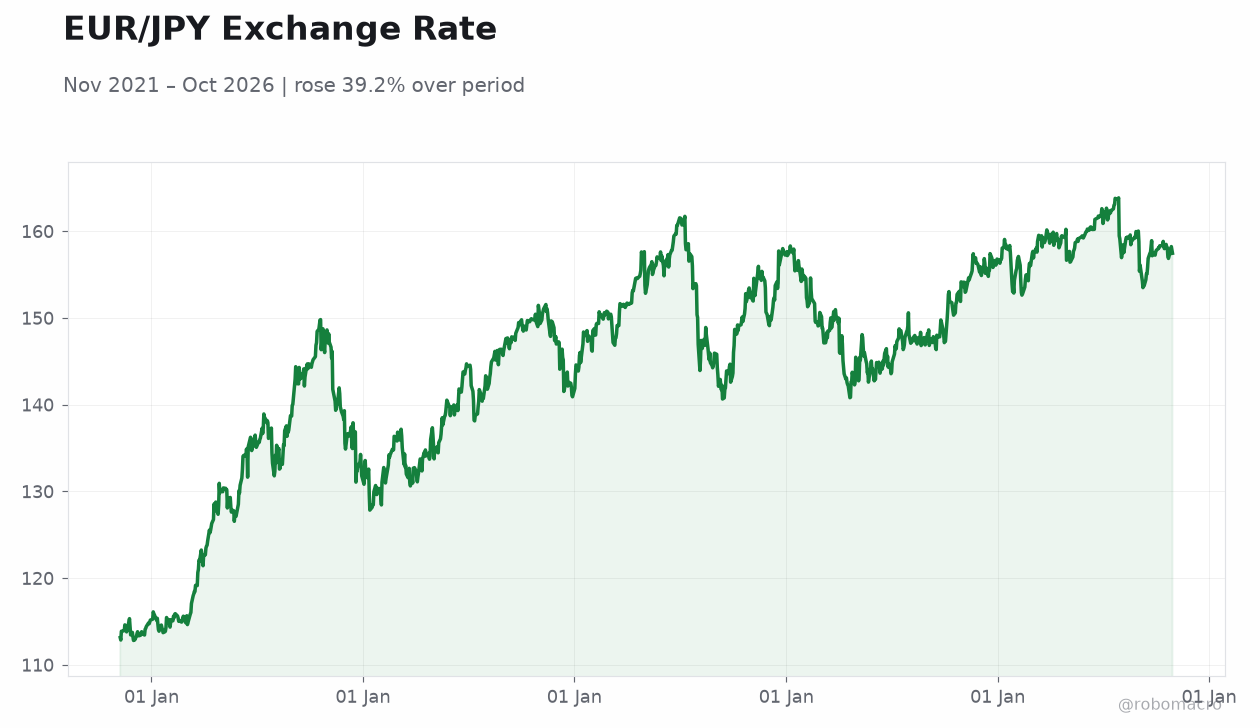
| EUR/JPY | 177.81 | +0.12% |
| Gold | 4,073.00 | +3.37% |
| Brent Crude | 94.62 | -8.67% |
| Bitcoin | 80,412.08 | +3.97% |
| German 2Y Bund | 3.05% | +1 bp |
| German 10Y Bund | 3.35% | 0 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Retail Sales Month-over-Month | 1.20 | 0.40 | -2 |
| Retail Sales Year-over-Year | -0.30 | - | -2.30 |
| S&P Global Manufacturing PMI Index | 51 | 50.80 | 52.20 |
| S&P Global Manufacturing PMI Index | 50.40 | 50.20 | 49.40 |
| Inflation Rate Year-over-Year Preliminary | 3.40 | - | 3.70 |
| Unemployment Level Change | 23,587 | 18,700 | 43,128 |
| S&P Global Services PMI | 58.30 | 57.60 | 57.20 |
| S&P Global Services PMI | 51.70 | - | 52 |
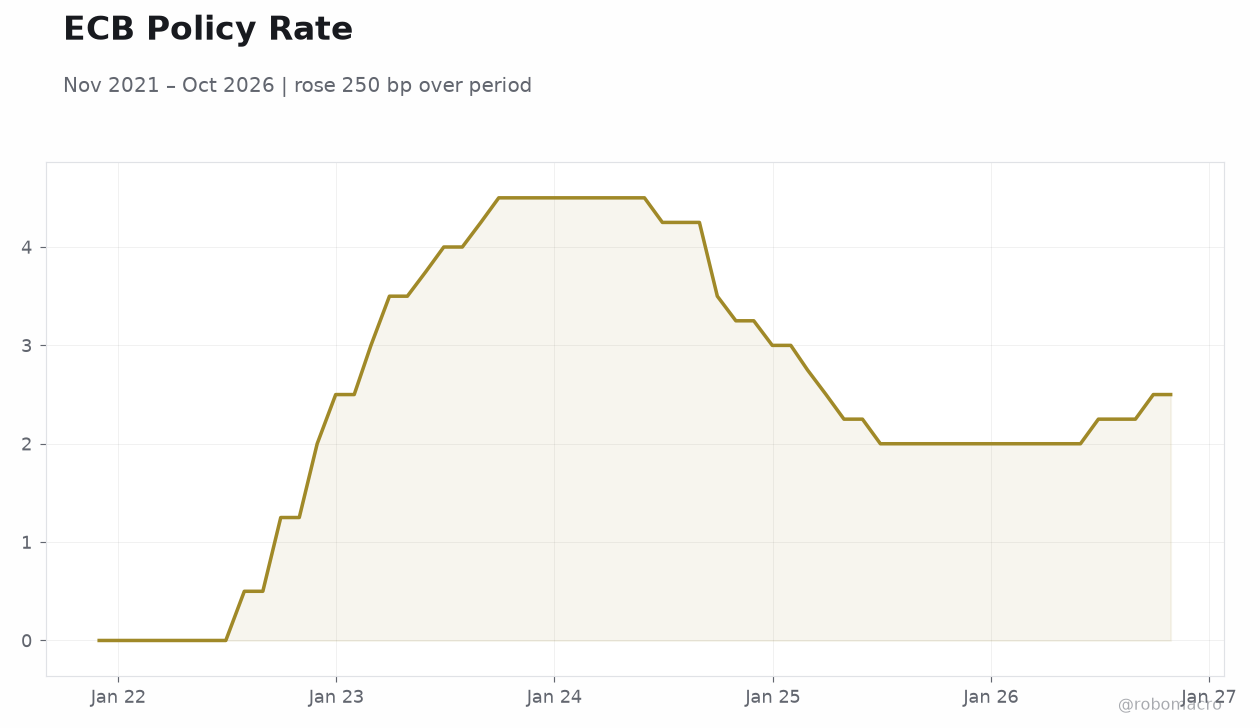 ECB Policy Rate | Type: macro_line | Policy Rate %: 2.5 (2026-10-29) | Range: 0–4.5 | Trend(5pt): 0,3,4.5,2,2.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Factory Orders Month-over-Month | -10.60 | 4 | 02:00 |
| Industrial Production Month-over-Month | -0.30 | 0.40 | 02:45 |
| Retail Sales Month-over-Month | 0.30 | 0.20 | 04:00 |
- Euro Stoxx 50 surges 1.97% and DAX 2.22% as risk appetite returns despite weak German retail sales (-2.0% MoM).
- Dutch inflation accelerates to 3.7% YoY, reinforcing ECB caution ahead of the December 17 meeting.
- Bund curve steady; 2Y at 3.05% (+1bp), 10Y at 3.35% (unchanged) as markets await German factory orders.
Yesterday's Recap
German retail sales disappointed sharply, contracting 2.0% month-over-month against consensus of +0.4%, with the year-over-year print at -2.3%, signaling persistent consumer weakness in the eurozone's largest economy. Spain's manufacturing PMI beat expectations at 52.2 versus 50.8 consensus, while Italy's manufacturing PMI slipped into contraction territory at 49.4, missing the 50.2 forecast. Dutch preliminary inflation accelerated to 3.7% year-over-year from 3.4% previously, adding to evidence that price pressures remain sticky.
Spain's services PMI moderated to 57.2 from 58.3, still indicating robust expansion, while Italy's services PMI improved to 52.0. Spanish unemployment rose by 43,128, significantly exceeding the 18,700 consensus, pointing to labor market softening. Despite the mixed data, European equities rallied strongly, with the Euro Stoxx 50 gaining 1.97% and the DAX surging 2.22%, while EUR/USD strengthened 0.52% to 1.13.
The Day Ahead
German factory orders are due at 02:00 ET, with consensus expecting a 4.0% rebound following the prior month's steep 10.6% contraction. France releases industrial production data at 02:45 ET, with forecasts pointing to a 0.4% monthly increase after the previous -0.3% decline. Italy's retail sales figures are scheduled for 04:00 ET, with consensus anticipating a modest 0.2% month-over-month gain.
These releases will provide fresh insight into the eurozone's industrial momentum and consumer spending dynamics as markets assess the region's growth trajectory heading into year-end.
Other Economic Notes
The eurozone inflation picture remains concerning, with headline CPI at 3.70% as of the latest preliminary reading, well above the ECB's 2% target. Unemployment stands at 6.50%, reflecting a labor market that remains relatively tight despite signs of softening in Spain. The divergence between German consumer weakness and Spanish services strength highlights the uneven nature of the eurozone recovery.
Fiscal consolidation risks are mounting, particularly in France, where budget pressures could weigh on growth prospects. Energy price volatility remains a key risk, with Brent crude declining 8.67%, offering some relief to inflation dynamics.