RoboMacro ResearchAlso todaySee the Commodities Daily

GCC Macro Daily(Beta Mode)

October 19, 2026 robomacro.com

Houthi Strikes Test Saudi Resilience; FII Delayed to 2027

Saudi Aramco25.28-0.39%
MSCI Saudi35.10-0.17%
MSCI UAE19.52-0.20%
MSCI Qatar15.60-0.22%

Market Snapshot

AssetLevelChange
Saudi Aramco25.28-0.39%
MSCI Saudi35.10-0.17%
MSCI UAE19.52-0.20%
MSCI Qatar15.60-0.22%
MSCI Kuwait34.90-0.81%
Brent Crude110.02+0.15%
WTI Crude98.86-2.51%
Gold4,162.10-0.45%
USD/SAR3.75+3.19%
USD/AED3.67+0.03%
USD/KWD0.31+0.03%
Bitcoin81,765.08-0.31%

Prior Economic Events

Data Prior Cons Actual
No events available
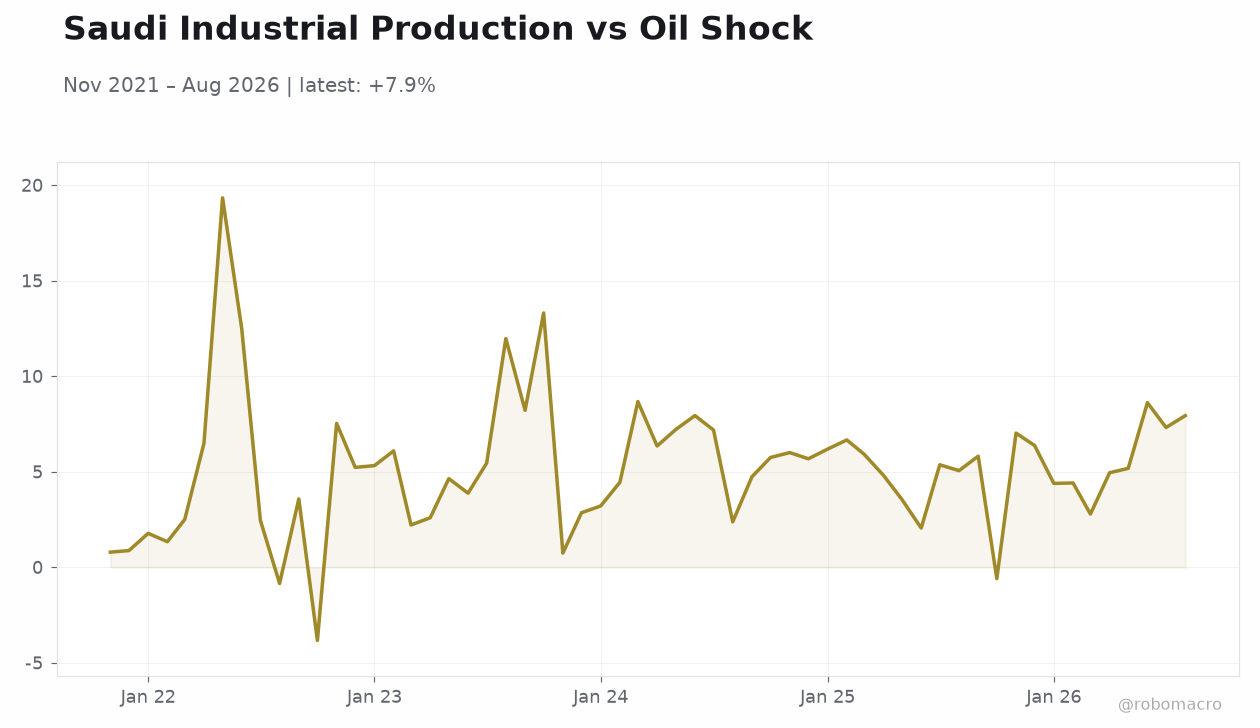
Saudi Industrial Production vs Oil ShockSaudi Industrial Production vs Oil Shock | Type: macro_line | Saudi IP Index: 7.935 (2026-08-01) | Range: -3.835–19.33 | Trend(6pt): 0.7882,5.318,8.671,3.545,7.313,7.935

Today's Economic Events

Data Prior Cons Time
No events available
  • Houthi missile and drone attacks on Saudi Arabia intensify, with six strikes claimed overnight, pressuring oil supply risk and GCC sovereign CDS.
  • Riyadh postpones the Future Investment Initiative (FII) to 2027 as flight disruptions ripple across Emirates, Etihad, flydubai, and Qatar Airways.
  • SAMA Governor affirms Saudi economic resilience; Finance Minister Al-Jadaan touts investment buffers against energy shocks.

Yesterday's Recap

Saudi Arabia dominated the GCC macro narrative as Houthi forces claimed six attacks on Saudi targets, prompting renewed scrutiny of the Kingdom's fiscal and oil-supply resilience. SAMA Governor Ayman Al-Sayari stated the Saudi economy remains resilient despite Middle East conflict, while Finance Minister Mohammed Al-Jadaan argued Saudi investments have mitigated the global energy shock's impact. Riyadh postponed the Future Investment Initiative to 2027, a signal that security risk is now shaping event calendars, not just markets.

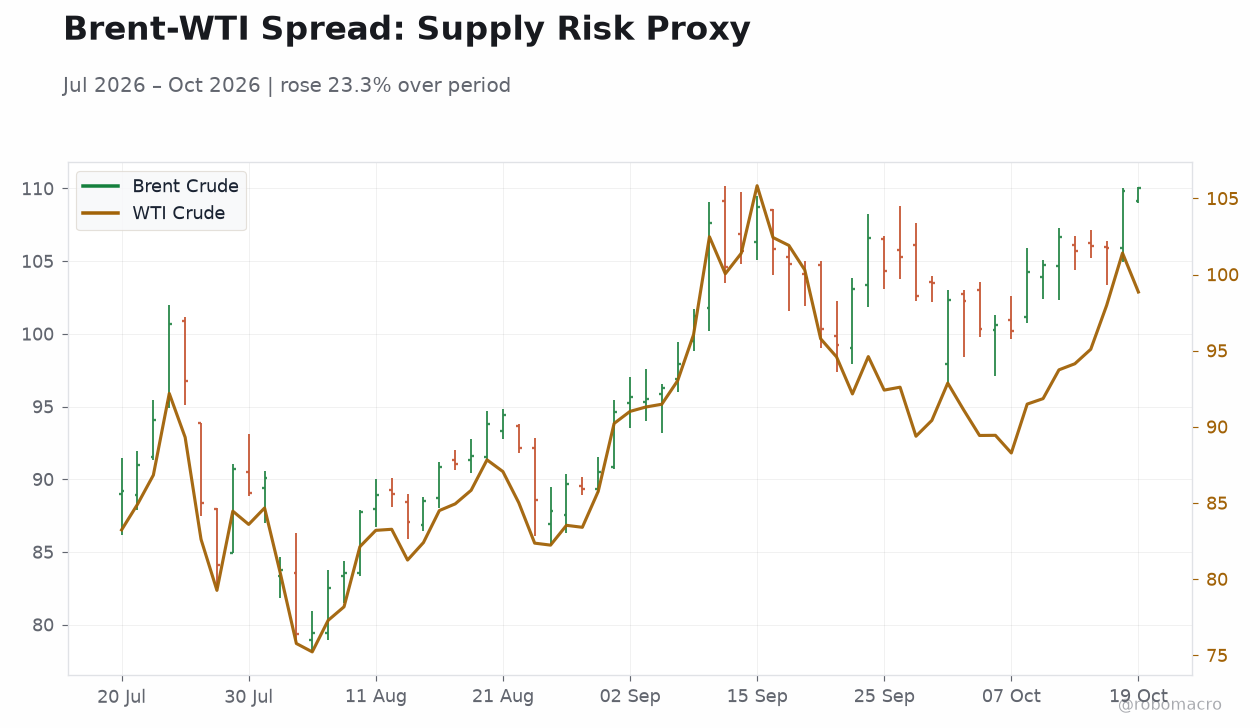
Regional equity benchmarks were uniformly softer: MSCI Saudi fell 0.17%, MSCI UAE 0.20%, MSCI Qatar 0.22%, and MSCI Kuwait 0.81%, with Saudi Aramco down 0.39% to SAR 25.28. Brent crude edged up 0.15% to $110.02, though WTI dropped 2.51% to $98.86, a divergence worth monitoring for Saudi fiscal assumptions. The UAE extended Abu Dhabi–Saudi flight cancellations through October 24, and Qatar Airways cut Jeddah flights while extending Riyadh and Dammam cancellations, underscoring how security risk is transmitting into aviation and logistics.

No official GCC macro prints were released yesterday.

The Day Ahead

The calendar is empty for Monday, October 19, with no scheduled GCC data releases across Saudi Arabia, the UAE, Qatar, Kuwait, Oman, or Bahrain. Market attention will therefore center on security headlines out of Yemen and the Red Sea, plus any official Saudi commentary on oil export flows through the Strait of Hormuz. Traders will watch whether Brent's premium over WTI widens further, a proxy for Middle East supply-risk pricing.

UAE and Qatari aviation updates on Saudi route cancellations remain a live indicator of disruption duration. With no prints due, positioning will likely be driven by global risk sentiment and Fed communication rather than domestic catalysts.

Other Economic Notes

Non-oil diversification momentum continues despite the security overhang, with Emirates NBD becoming the first MENA bank to run OpenAI models in the UAE, a marker of Gulf AI adoption. Qatar is advancing a comprehensive plan to ease Lebanon's electricity crisis and has called for a non-aggression pact with Iran while strengthening its defense industry. ↓ p.2
Page 1

GCC Macro Daily(Beta Mode)

October 19, 2026 robomacro.com
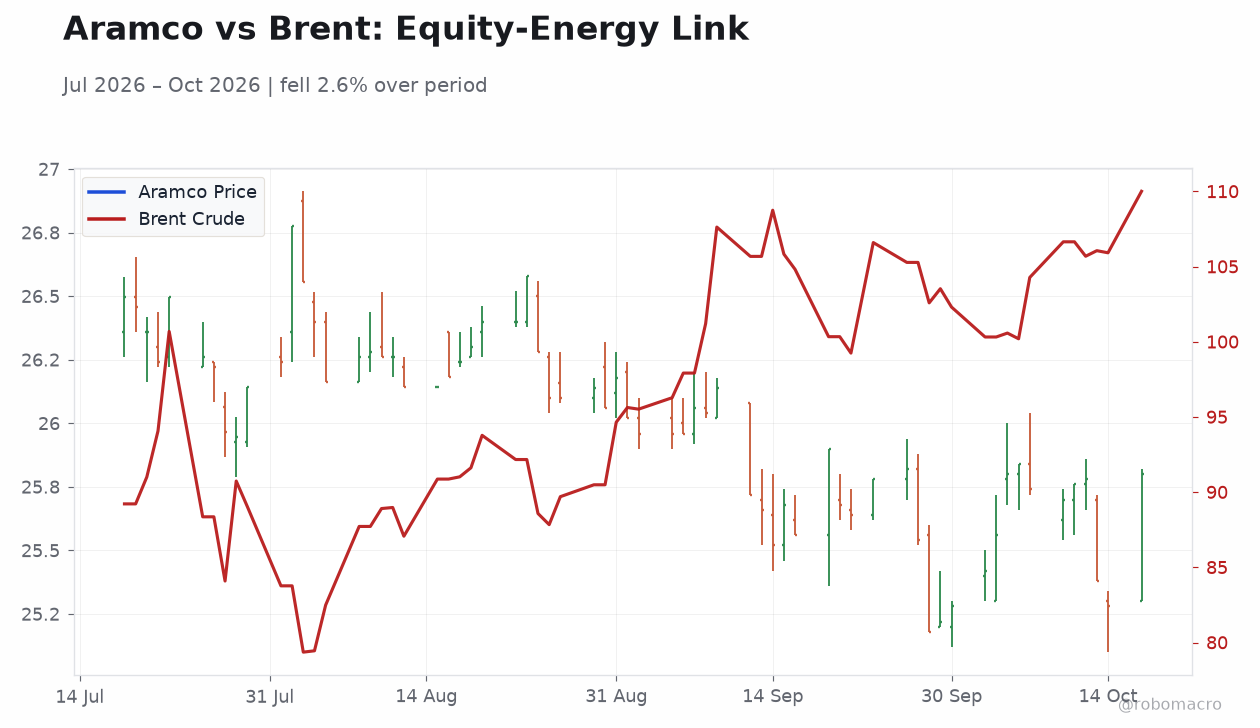
Aramco vs Brent: Equity-Energy Link Aramco vs Brent: Equity-Energy Link | Type: market_hloc | Aramco Price: 25.8 (2026-10-18) | Range: 25.18–26.77 | Trend(5pt): 26.5,26.28,26.18,25.78,25.8 | Brent Crude: 110 (2026-10-19) | Range: 79.36–110 | Trend(5pt): 89.22,88.91,95.63,104.3,110
Brent-WTI Spread: Supply Risk Proxy Brent-WTI Spread: Supply Risk Proxy | Type: market_hloc | Brent Crude: 110 (2026-10-19) | Range: 79.36–110 | Trend(5pt): 89.22,88.91,95.63,104.3,110 | WTI Crude: 98.85 (2026-10-19) | Range: 75.22–105.8 | Trend(5pt): 83.23,83.2,91.01,92.41,98.85
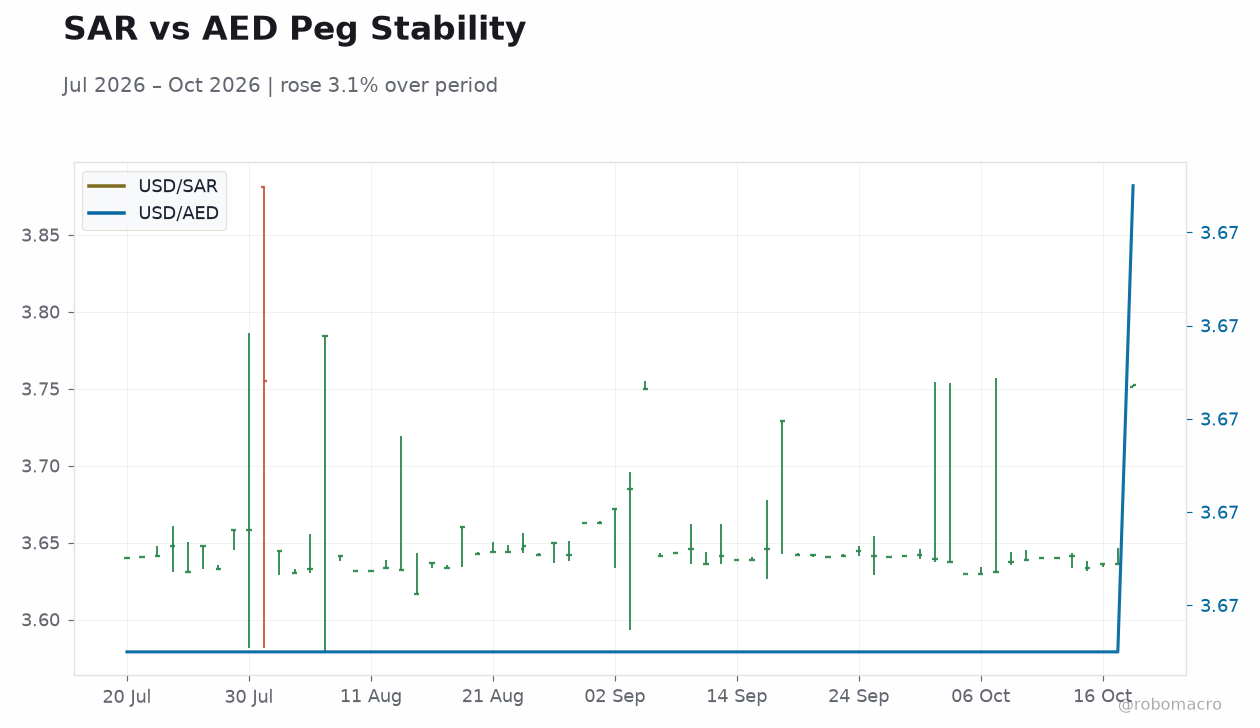
SAR vs AED Peg Stability SAR vs AED Peg Stability | Type: market_hloc | USD/SAR: 3.752 (2026-10-20) | Range: 3.617–3.784 | Trend(6pt): 3.64,3.631,3.672,3.645,3.636,3.752 | USD/AED: 3.672 (2026-10-20) | Range: 3.671–3.672 | Trend(6pt): 3.671,3.671,3.671,3.671,3.671,3.672
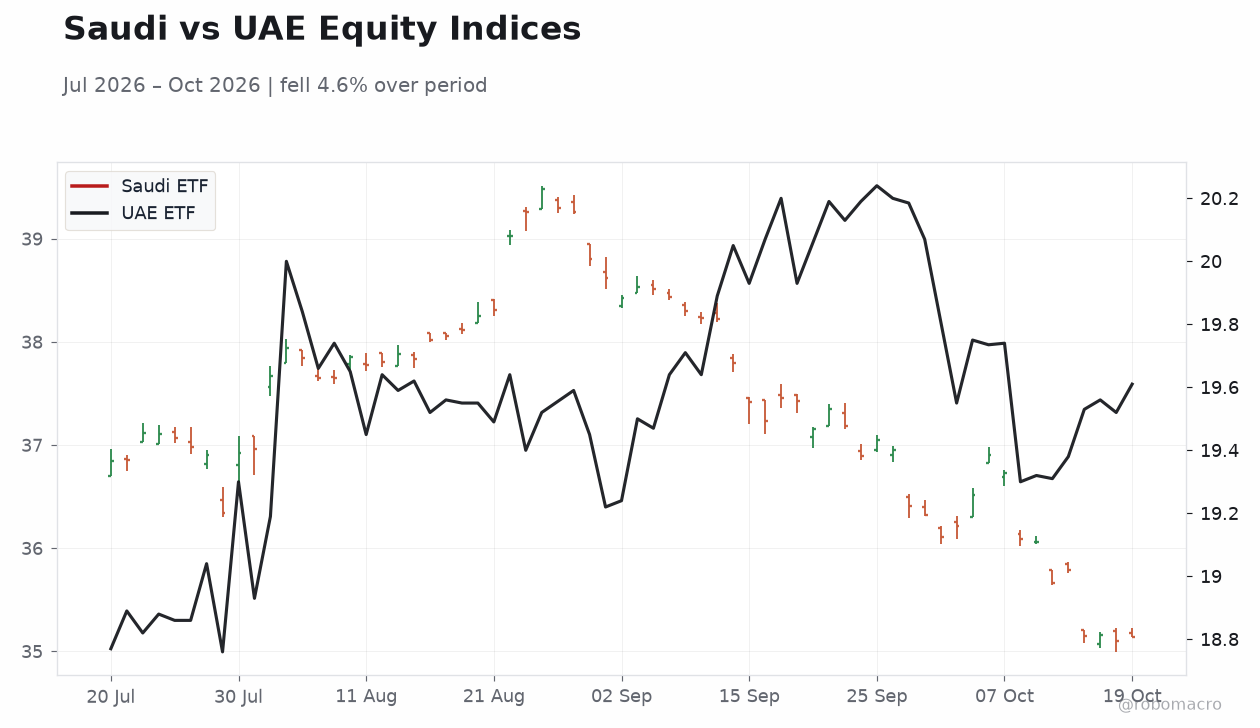
Saudi vs UAE Equity Indices Saudi vs UAE Equity Indices | Type: market_hloc | Saudi ETF: 35.14 (2026-10-19) | Range: 35.1–39.48 | Trend(5pt): 36.85,37.78,38.43,37.05,35.14 | UAE ETF: 19.61 (2026-10-19) | Range: 18.76–20.24 | Trend(5pt): 18.77,19.45,19.24,20.24,19.61

Other Economic Notes (continued)

A Chinese firm agreed to build rail tunnels in Qatar amid Iran war risk, signaling continued infrastructure commitment. Kuwait's Emir and French President Macron discussed deeper energy and investment ties as Macron began a Gulf tour seeking energy security and Strait of Hormuz reopening. These developments reinforce that GCC capital deployment is proceeding even as headline risk rises.

Global Macro News

Iran warned the US against targeting energy facilities, pledging swift retaliation, which keeps a risk premium embedded in crude. A Qatari LNG tanker sailed through the Red Sea despite Houthi attack risk, a modest but notable confidence signal for Gulf energy logistics. Gold slipped 0.45% to $4,162.10, while Bitcoin eased 0.31% to $81,765, suggesting risk appetite is mixed rather than outright defensive.

The Brent–WTI spread reflects differentiated supply-risk pricing, with waterborne crude carrying the geopolitical premium. Asian buyers are already feeling the pinch: Houthi attacks on Saudi Arabia are raising Pakistan's oil import costs and investor concerns, and Bangladesh faces another economic blow from Saudi conflict risk. Macron's Gulf tour framing around energy security and Hormuz reopening underscores European dependence on Gulf supply continuity.

For GCC sovereigns, the key transmission channel remains oil revenue volatility into fiscal balances and CDS spreads.

Sponsored by Arbitrage Search
Page 2

GCC Macro Daily(Beta Mode)

October 19, 2026 robomacro.com

Continuation

GCC Central Banks Watch

All six GCC central banks remain structurally tethered to the Fed through their USD pegs, with SAMA, CBUAE, QCB, CBK, CBO, and CBB rate decisions mechanically constrained by US policy. Kuwait is the outlier, pegging the dinar to a basket rather than the dollar alone, which affords the CBK marginally more discretion though it still tracks Fed direction closely. SAMA's governor publicly emphasized Saudi resilience, but the policy stance remains a hold-and-follow posture absent a Fed move.

Interbank rates bear watching: SAIBOR and EIBOR should stay anchored near the Fed corridor, though any liquidity strain from flight cancellations or oil-revenue timing could nudge them. FX reserve adequacy across the GCC remains comfortable, with the UAE and Saudi Arabia holding substantial buffers to defend pegs. No GCC central bank has signaled divergence from the Fed path, and with no data on the calendar today, expect policy silence to persist.

Sponsored by Arbitrage Search
Page 3