Greater China Macro Daily(Beta Mode)
China Trade Surges, Stocks Stabilize on State Support
Market Snapshot
| Asset | Level | Change |
|---|---|---|
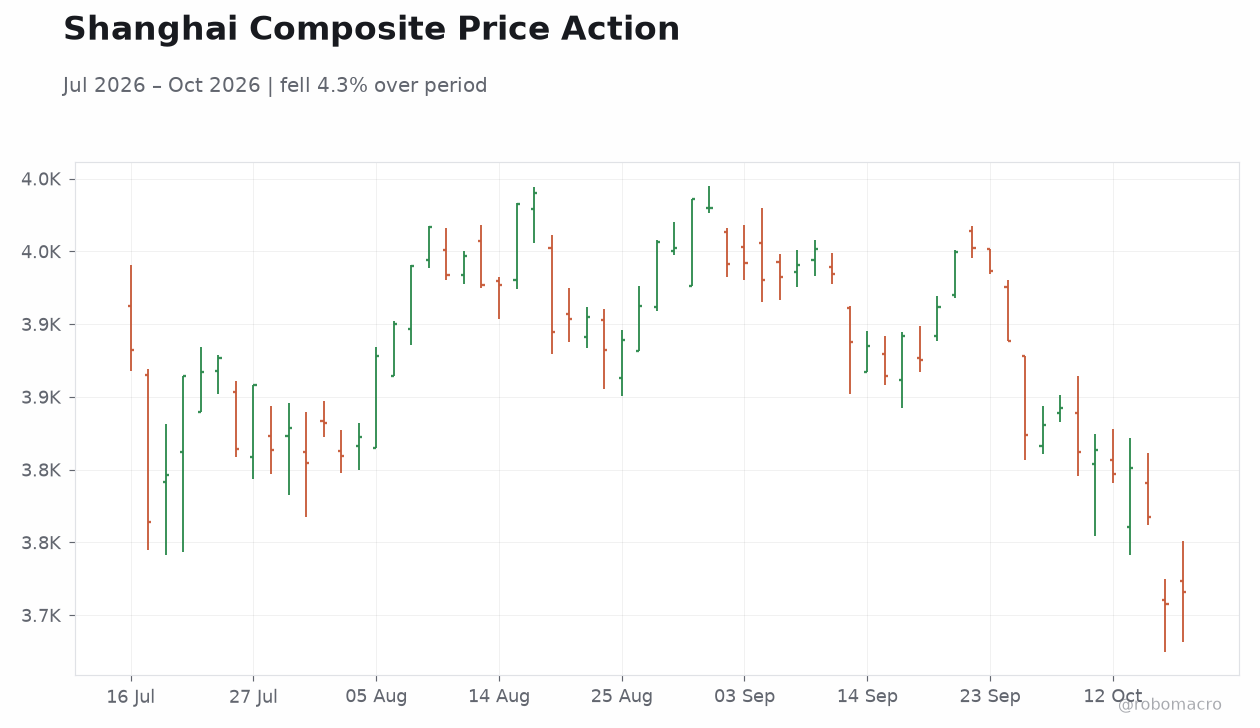
| Shanghai Composite | 3,716.28 | +0.24% |
| CSI 300 | 4,170.61 | +0.11% |
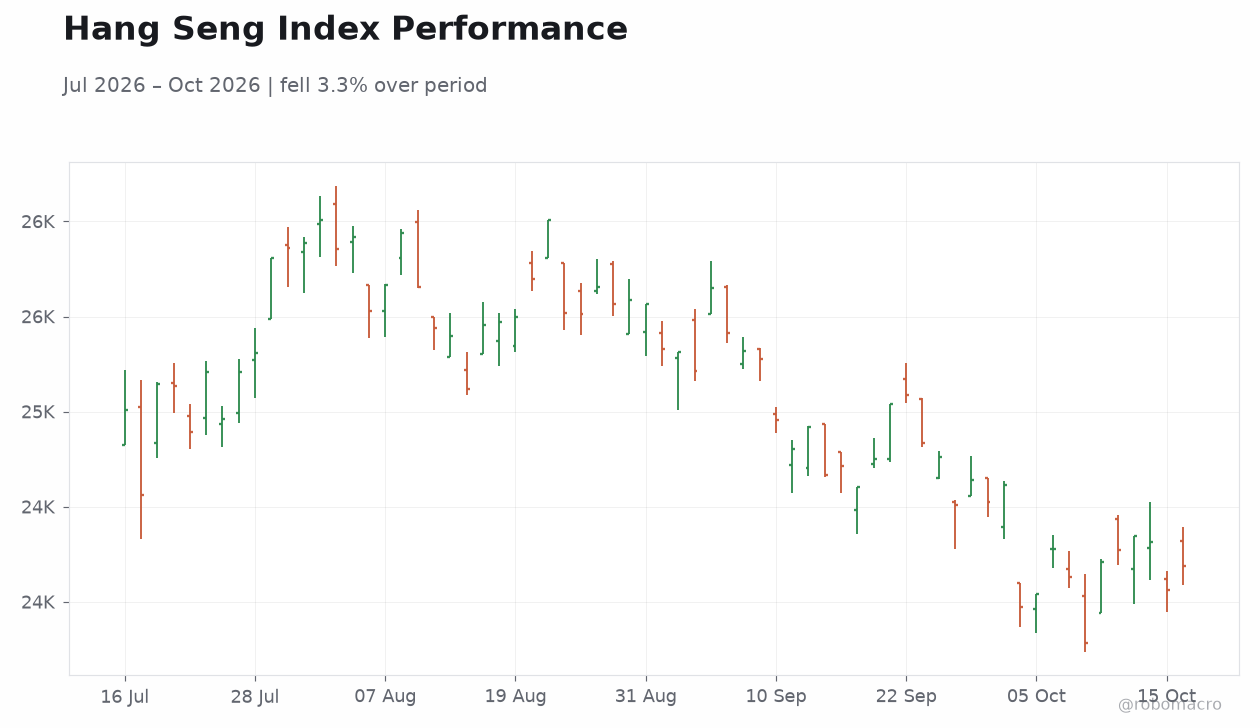
| Hang Seng | 24,186.83 | +0.52% |
| TAIEX | 47,111.26 | +0.30% |
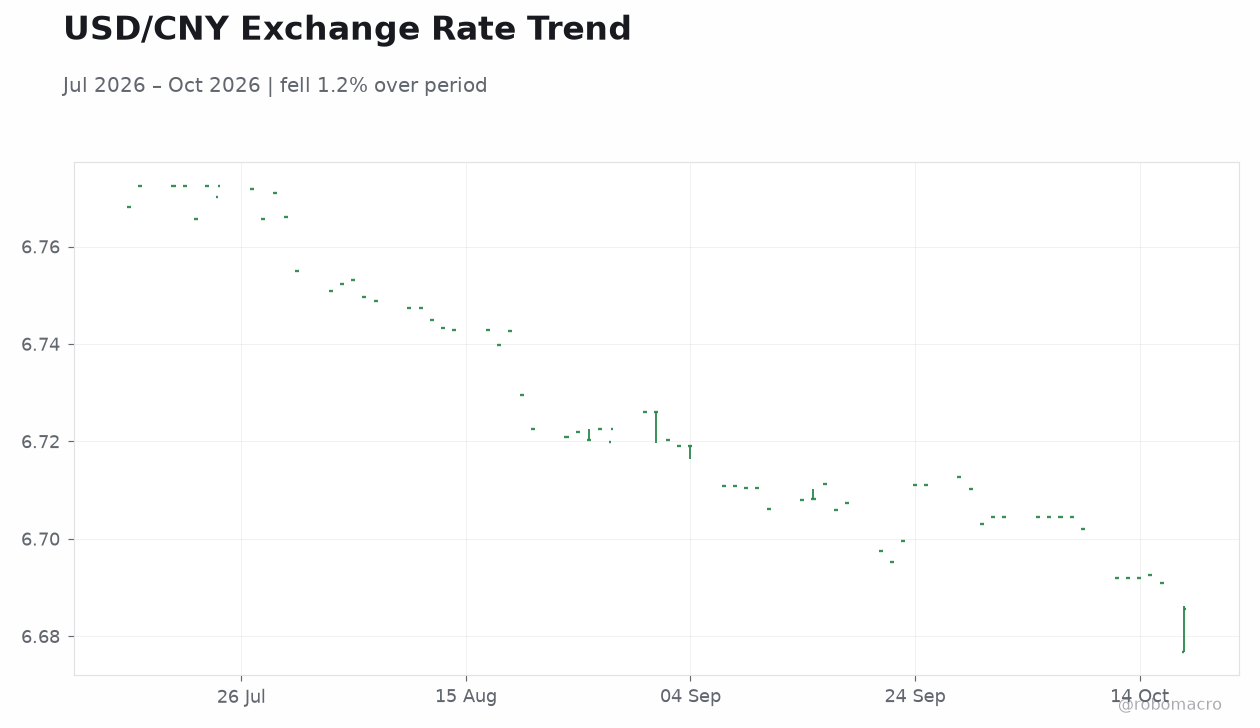
| USD/CNY | 6.68 | -0.21% |
| USD/HKD | 7.85 | -0.01% |
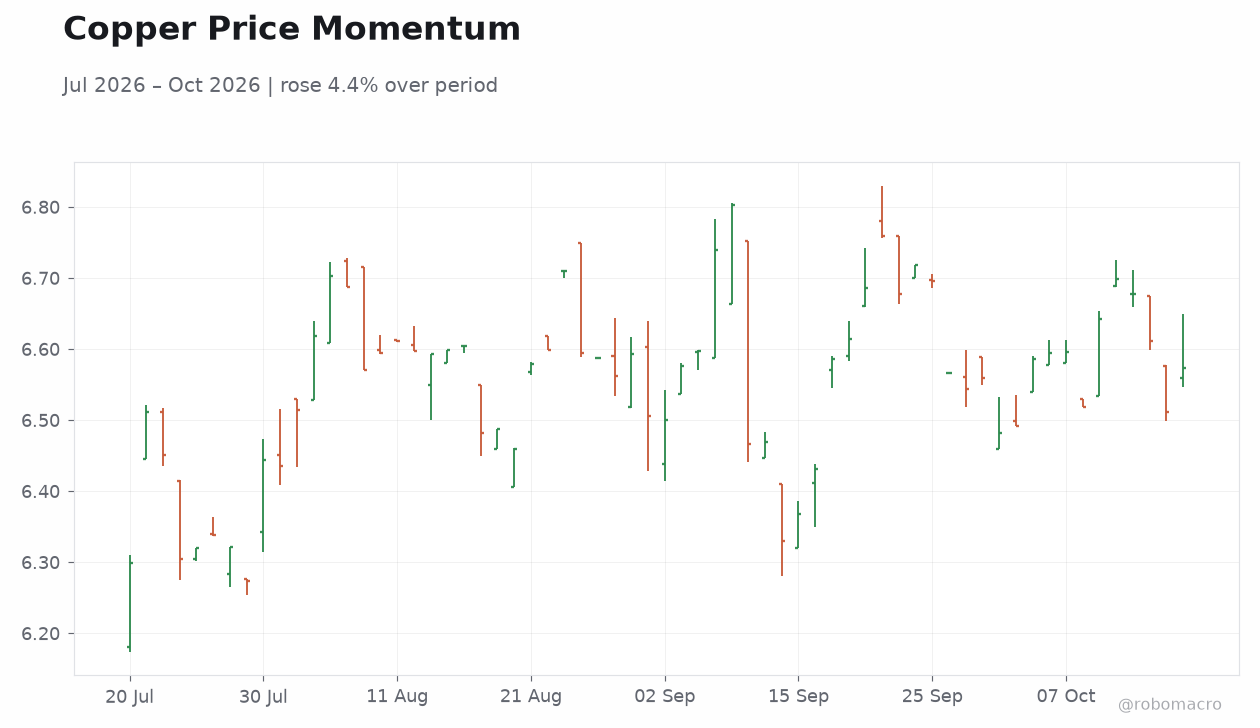
| Copper | 6.57 | +0.95% |
| Brent Crude | 109.86 | +3.72% |
| Gold | 4,181.10 | +0.26% |
| Bitcoin | 81,377.73 | -0.01% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Year-over-Year | 0.80 | 1 | 0.90 |
| Inflation Rate Month-over-Month | 0.40 | 0.30 | 0.20 |
| Producer Price Index Year-over-Year | 3.80 | 4.50 | 5 |
| Exports Year-over-Year | 25 | 25.50 | 36.30 |
| Imports Year-over-Year | 28.20 | 24.50 | 31 |
| Trade Balance | 119,090m | 118,100m | 133,530m |
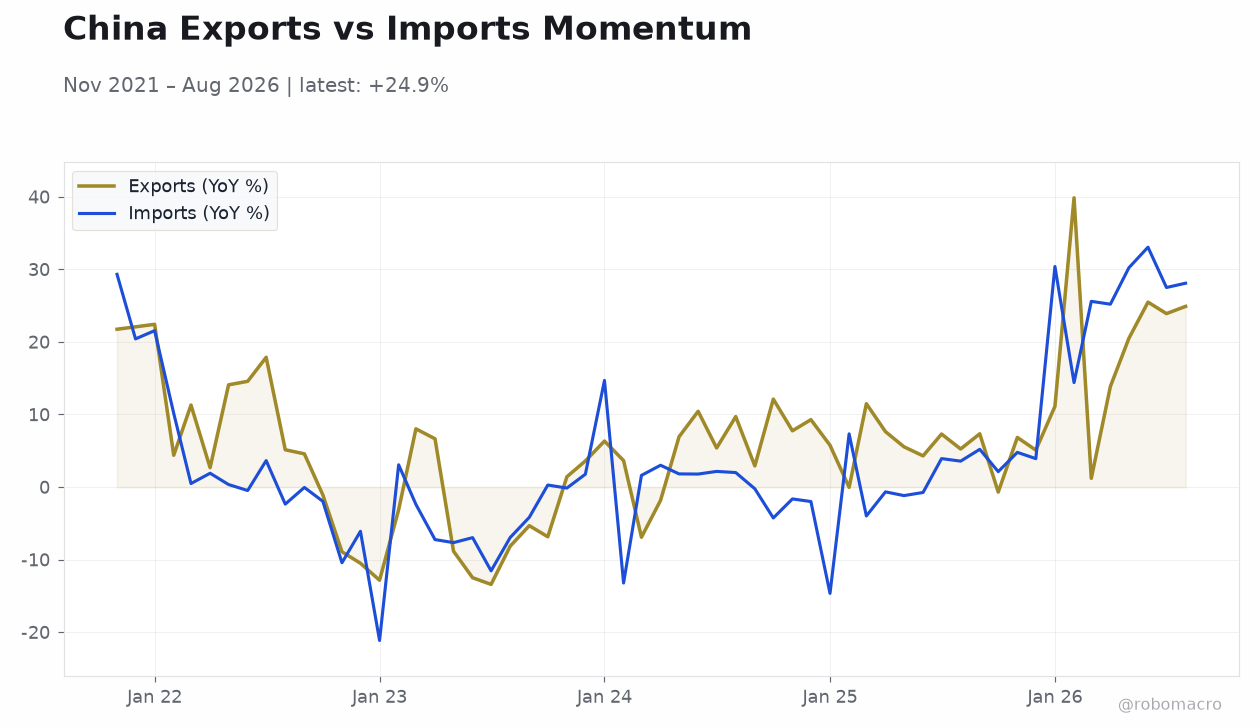 China Exports vs Imports Momentum | Type: macro_line | Exports (YoY %): 24.9 (2026-08-01) | Range: -13.41–39.85 | Trend(6pt): 21.75,-12.84,-6.912,5.548,23.9,24.9 | Imports (YoY %): 28.09 (2026-08-01) | Range: -21.14–33.05 | Trend(6pt): 29.31,-21.14,1.608,-1.177,27.5,28.09
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Mainland China's September exports surged 36.3% YoY and imports rose 31.0%, far exceeding consensus, driving a record $133.53bn trade surplus and lifting the yuan toward a third straight weekly gain.
- Beijing's "national team" stepped up equity support via heavy ETF inflows, selling curbs, and buyback encouragement, helping the Shanghai Composite and Hang Seng close higher on Friday.
- Attention turns to a heavy data week: China's Q3 GDP, LPR decision, and global flash PMIs, with the PBoC expected to hold policy rates steady.
Yesterday's Recap
Greater China markets closed higher on Friday, with mainland Chinese equities supported by signs of renewed state buying. The Shanghai Composite rose 0.24% to 3,716.28 and the CSI 300 gained 0.11% to 4,170.61, while Hong Kong's Hang Seng advanced 0.52% to 24,186.83. Taiwan's TAIEX added 0.30% to 47,111.26, recovering modestly after regional semiconductor-led volatility earlier in the week.
The latest trade data dominated the macro narrative: mainland China's exports grew 36.3% year-over-year and imports climbed 31.0%, both crushing consensus estimates, producing a trade surplus of $133.53bn. Inflation prints released alongside trade showed CPI up just 0.9% year-over-year with a 0.2% monthly gain, while producer prices accelerated to 5.0% YoY, underscoring a widening gap between consumer and factory-gate inflation. The currency reflected the trade strength, with USD/CNY easing 0.21% to 6.68 as the yuan held firm.
Copper, a key China growth proxy, rallied 0.95%, and Brent crude jumped 3.72% to $109.86 amid Middle East supply concerns.
The Day Ahead
The calendar is quiet into Monday, but the week ahead is dense. Mainland China's loan prime rate decision headlines Tuesday, with the PBoC widely expected to keep the one- and five-year LPR unchanged following the strong trade data. Third-quarter GDP follows later in the week alongside activity indicators, which will test whether export momentum is translating into domestic demand.
Global flash PMIs due Friday will include China's manufacturing and services readings, offering a timely check on the post-Golden Week recovery. Hong Kong and Taiwan have no major scheduled releases, leaving equity and currency markets to digest the week's flow of Chinese data and any follow-through from state fund buying.
Other Economic Notes
Beijing's interventionist streak extended beyond equities, with reports that authorities are moving to restrict exports of certain solar technologies to preserve technological advantage—a continuation of the rare earths playbook with implications for global supply chains. Separately, officials signaled plans to further open domestic financial markets to foreign investors, a structural reform push that contrasts with the short-term market-support measures. ↓ p.2