Greater China Macro Daily(Beta Mode)
China PMIs Eyed as Equities Diverge, HKMA Eases Refi
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Shanghai Composite | 3,671.00 | +0.62% |
| CSI 300 | 4,083.87 | +0.85% |
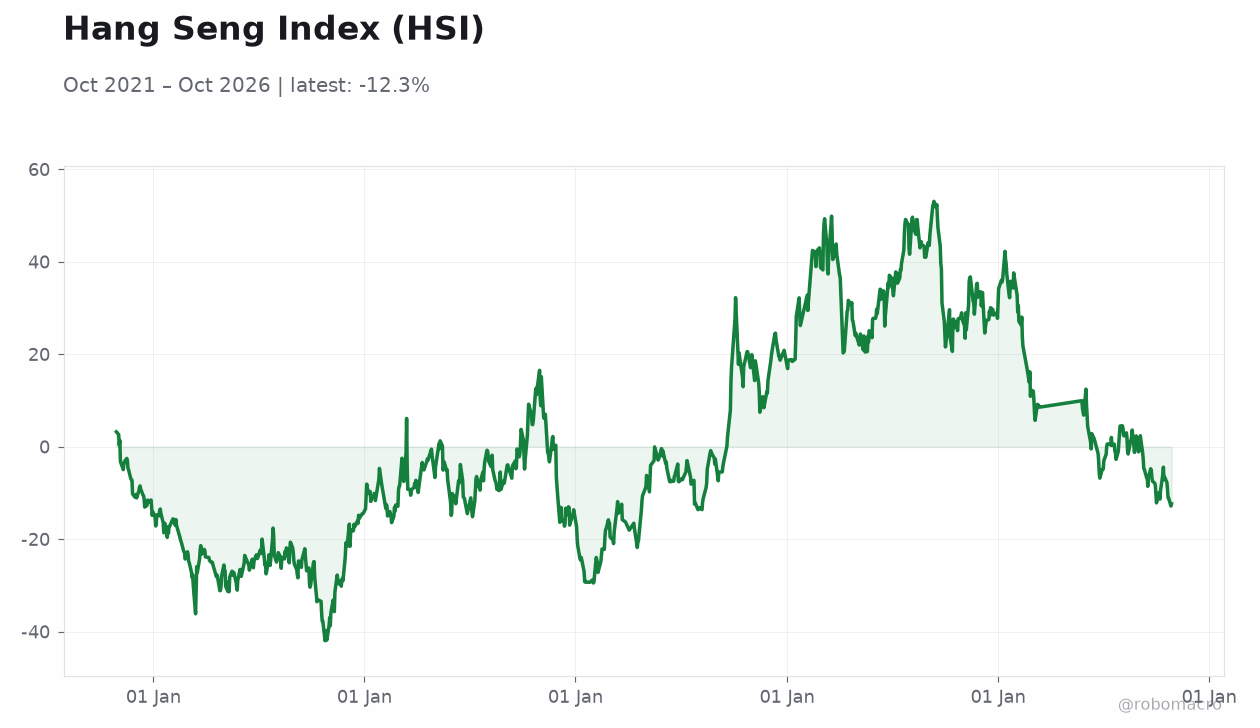
| Hang Seng | 23,041.32 | -0.73% |
| TAIEX | 46,096.23 | +0.12% |
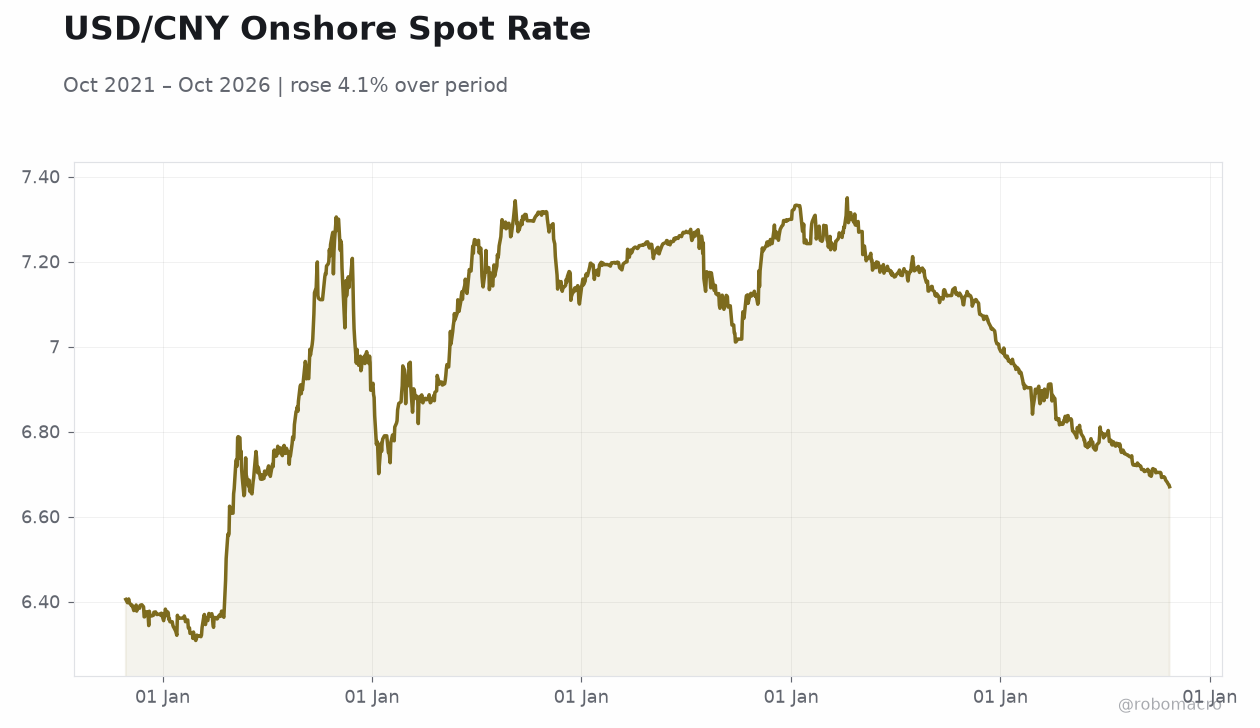
| USD/CNY | 6.67 | -0.07% |
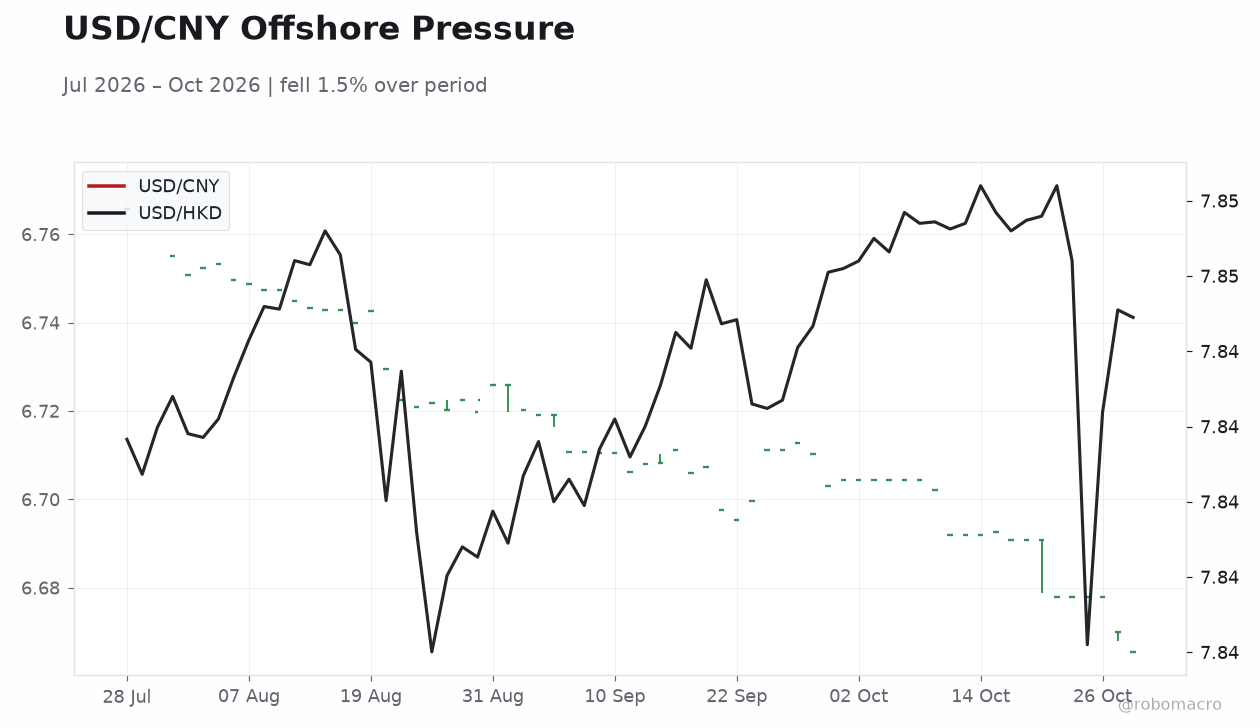
| USD/HKD | 7.84 | -0.00% |
| Copper | 6.68 | +0.91% |
| Brent Crude | 110.44 | -3.02% |
| Gold | 4,081.20 | +0.16% |
| Bitcoin | 81,238.44 | +0.54% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
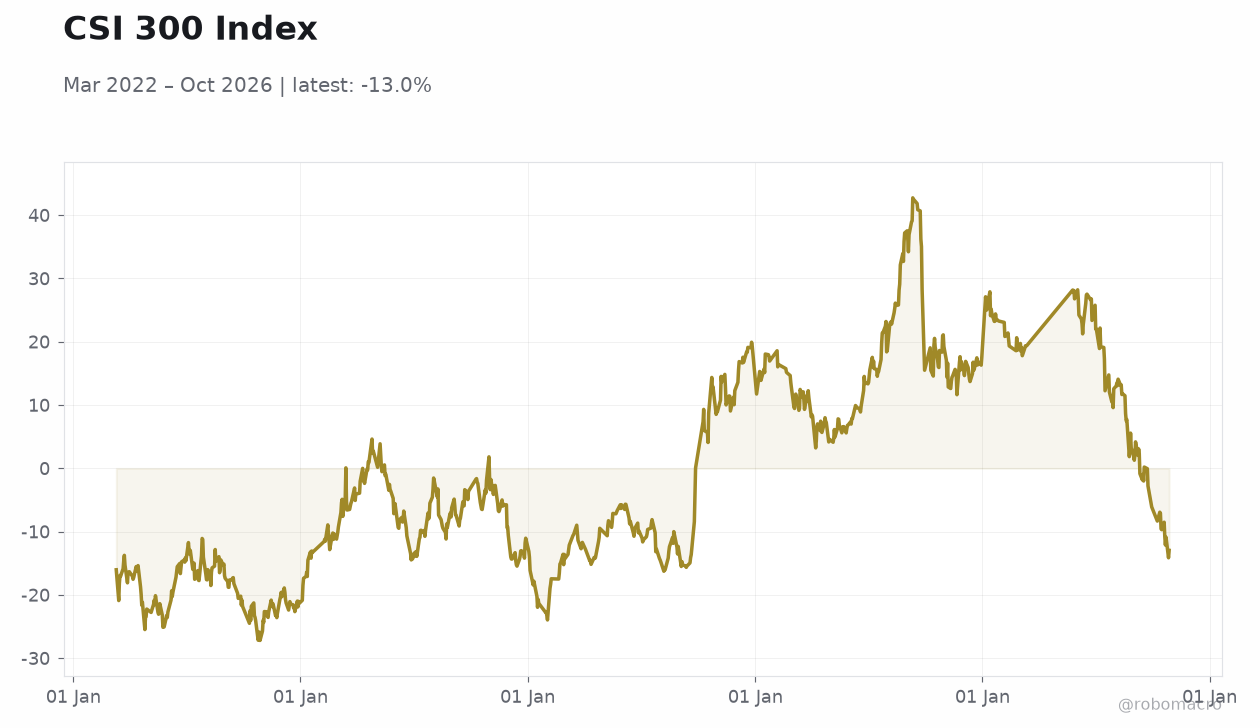 CSI 300 Index | Type: macro_line | CSI 300 Index: -12.96 (2026-10-28) | Range: -27.2–42.74 | Trend(6pt): -16.02,-5.552,-11.58,15.61,-14.13,-12.96
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| NBS Manufacturing PMI | 50.10 | 50.10 | 21:30 |
| NBS Non-Manufacturing PMI | 50.20 | 50.50 | 21:30 |
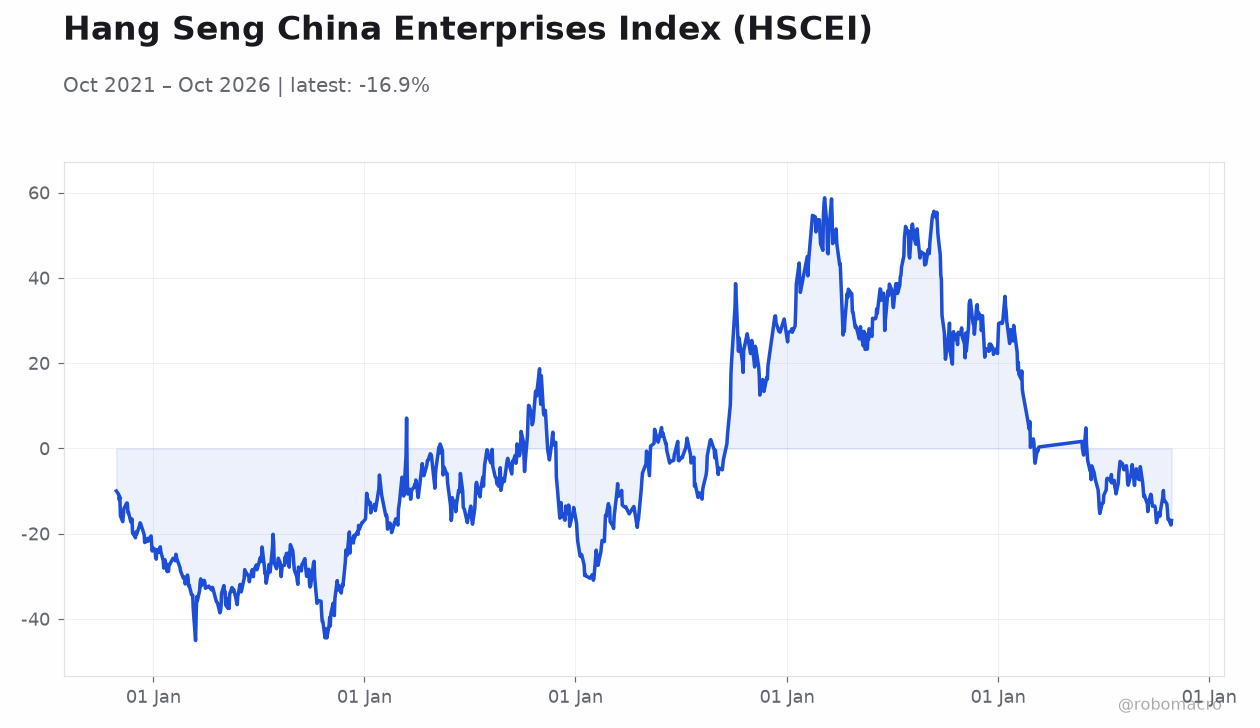
- Mainland equities advanced (CSI 300 +0.85%, Shanghai Composite +0.62%) while Hong Kong lagged (Hang Seng -0.73%), with the divergence reflecting property-sector stress and offshore sentiment.
- China's NBS Manufacturing PMI (consensus 50.1) and Non-Manufacturing PMI (consensus 50.5) are due October 30, the week's key growth read.
- HKMA appointed Deutsche Bank as a Primary Liquidity Provider for Hong Kong's offshore RMB market and urged banks to ease developer refinancing amid a "K-shaped" property recovery.
Yesterday's Recap
Mainland China equities outperformed on Tuesday, with the CSI 300 rising 0.85% and the Shanghai Composite adding 0.62%, while Hong Kong's Hang Seng fell 0.73% as property-sector concerns and offshore risk appetite weighed on the territory. Taiwan's TAIEX edged up 0.12%, supported by continued AI-driven semiconductor demand that has also lifted South Korean tech stocks. The yuan firmed modestly, with USD/CNY at 6.67 (-0.07%), while USD/HKD held at 7.84 near the strong side of the peg band.
Copper, a key China growth proxy, gained 0.91% to 6.68, signaling steady industrial demand expectations. Brent crude slumped 3.02% to 110.44, easing imported inflation pressure for mainland China, while gold ticked up 0.16% to 4,081.20. No official Greater China data releases printed yesterday, leaving markets positioned ahead of Friday's mainland PMI readings.
The Day Ahead
The calendar is light today, with attention fixed on Friday's (October 30) mainland China NBS Manufacturing PMI, where consensus sits at 50.1 — exactly at the expansion/contraction threshold — and the Non-Manufacturing PMI, consensus 50.5 versus a prior 50.2. A manufacturing print below 50 would reinforce expectations of subdued industrial momentum and could prompt fresh PBoC liquidity support. Hong Kong and Taiwan have no scheduled tier-one releases, so flows will be driven by mainland sentiment and offshore RMB dynamics.
Traders will also watch copper and Brent moves for cross-asset confirmation of the growth narrative. With no US or regional data on the docket, positioning into Friday's PMIs likely dominates session direction.
Other Economic Notes
China's external trade relationships continue to shift: reports suggest Chinese buyers prefer Brazilian soybeans over US supply despite Beijing's stated openness, underscoring the commercial rather than political logic driving agricultural procurement. China conceded an annual limit of 350,000 hybrid vehicle export units under EU trade pressure, a concession that narrows alternative-market prospects for mainland automakers. China-Zimbabwe trade surged 51.6% to US$5bn, illustrating deepening South-South commodity linkages.
↓ p.2