Greater China Macro Daily(Beta Mode)
China PMI Slump, HK Fintech Push, TAIEX Tumbles
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Shanghai Composite | 3,599.02 | -1.44% |
| CSI 300 | 3,985.50 | -1.39% |
| Hang Seng | 23,294.42 | +1.46% |
| TAIEX | 45,211.83 | -2.49% |
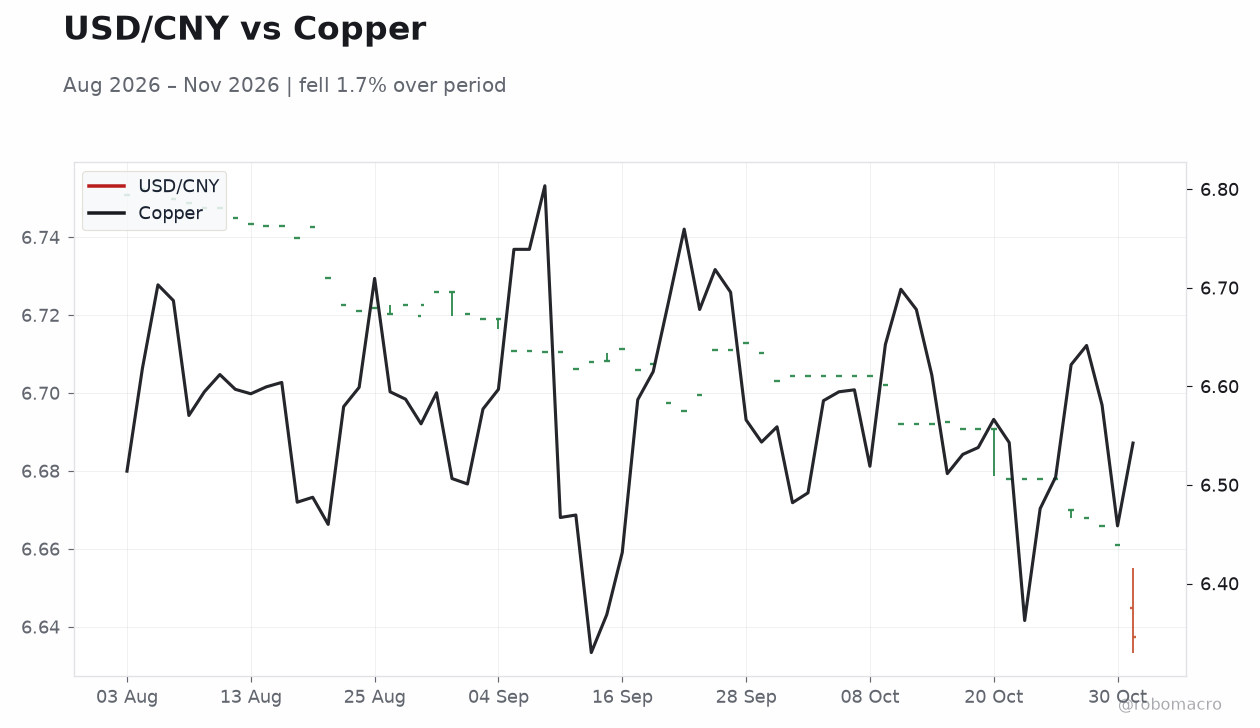
| USD/CNY | 6.64 | -0.35% |
| USD/HKD | 7.85 | +0.00% |
| Copper | 6.54 | +1.30% |
| Brent Crude | 104.23 | -11.40% |
| Gold | 3,956.60 | +1.48% |
| Bitcoin | 76,674.60 | -2.01% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
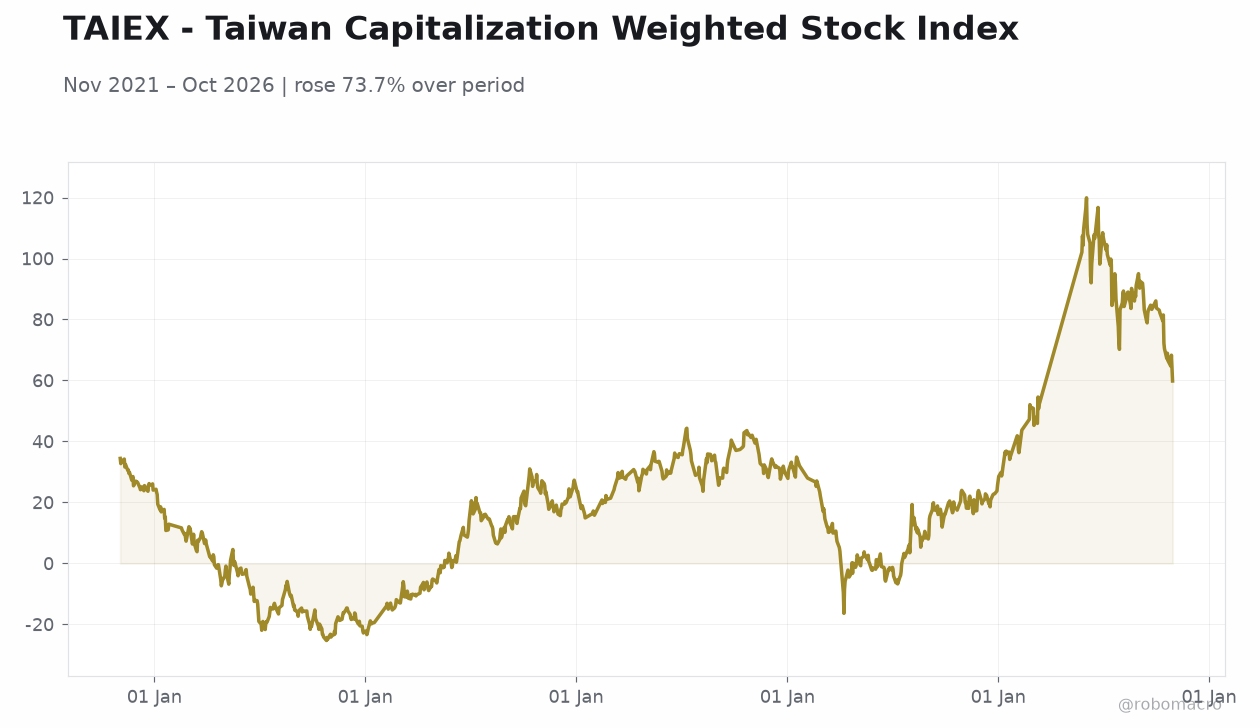 TAIEX - Taiwan Capitalization Weighted Stock Index | Type: macro_line | TAIEX - Taiwan Capitalization Weighted Stock Index: 59.83 (2026-10-30) | Range: -25.27–119.9 | Trend(5pt): 34.44,-18.26,16.4,-1.983,59.83
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Tuesday (2026-11-03) | |||
| RatingDog Services PMI | 51.60 | 51.50 | 20:45 |
- China's October factory activity eased into contraction, with the RatingDog Services PMI due Tuesday at a 51.5 consensus versus 51.6 prior, as growth momentum wobbles into Q4.
- Mainland equities sold off sharply (Shanghai Composite -1.44%, CSI 300 -1.39%) while Hong Kong bucked the trend (Hang Seng +1.46%) on fintech and tokenization momentum from HKMA's FinTech Week.
- Taiwan's TAIEX plunged 2.49% as the AI chip trade showed cracks after mixed US-China earnings, even as Taiwan's growth continues to outpace regional peers on semiconductor demand.
Yesterday's Recap
Mainland China's equity complex weakened on Monday, with the Shanghai Composite falling 1.44% to 3,599.02 and the CSI 300 down 1.39% to 3,985.50, as October factory activity data pointed to a slowdown in manufacturing momentum. The offshore yuan strengthened, with USD/CNY down 0.35% to 6.64, reflecting continued conversion flows and a softer dollar backdrop. Hong Kong diverged positively, with the Hang Seng gaining 1.46% to 23,294.42 as HKMA's FinTech Week 2026 unveiled a slate of tokenization and agentic-finance initiatives, including Project SAGE and 24/7 tokenized settlement infrastructure.
Taiwan was the day's laggard, with the TAIEX tumbling 2.49% to 45,211.83 as the global AI trade showed signs of fatigue following mixed US and China earnings. In commodities, copper — a key China growth proxy — rose 1.30% to 6.54, while Brent crude collapsed 11.40% to 104.23 on demand concerns. China's mega banks reported record quarterly profits as margins recovered and bond-trading gains offset sluggish loan growth.
The Day Ahead
The calendar is light, with the sole scheduled Greater China release being China's RatingDog Services PMI on Tuesday at 20:45 ET, consensus 51.5 versus 51.6 prior — a print below 50 would confirm the services sector is losing steam alongside manufacturing. No Hong Kong or Taiwan data releases are scheduled. Markets will continue to digest HKMA's FinTech Week announcements, particularly the tokenized settlement and Project SAGE frameworks, which could support Hong Kong financial-sector sentiment.
Taiwan's TAIEX will remain sensitive to AI-chip earnings follow-through and any further signs of semiconductor demand moderation. Mainland investors will watch for any PBoC liquidity operations or State Council signals on stimulus as growth concerns mount.
Other Economic Notes
China's state-owned mega banks posted their strongest-ever quarterly profits, with improved net interest margins and bond-investment trading gains outweighing weak credit demand — a sign that margin recovery is underway even as loan growth stays soft. The African Export-Import Bank is planning a $1 billion syndicated loan that could include an offshore yuan tranche, a modest but symbolic step in internationalizing the CNH market. ↓ p.2