Greater China Macro Daily(Beta Mode)
PBoC Caps Yuan Rally, Services PMI Cools
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Shanghai Composite | 3,677.55 | +1.92% |
| CSI 300 | 4,101.33 | +2.31% |
| Hang Seng | 23,525.97 | +0.57% |
| TAIEX | 43,307.54 | -3.59% |
| USD/CNY | 6.66 | +0.25% |
| USD/HKD | 7.85 | -0.02% |
| Copper | 6.41 | +0.49% |
| Brent Crude | 94.64 | -8.65% |
| Gold | 4,070.50 | +3.30% |
| Bitcoin | 80,190.84 | +3.68% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| RatingDog Services PMI | 51.60 | 51.50 | 50.80 |
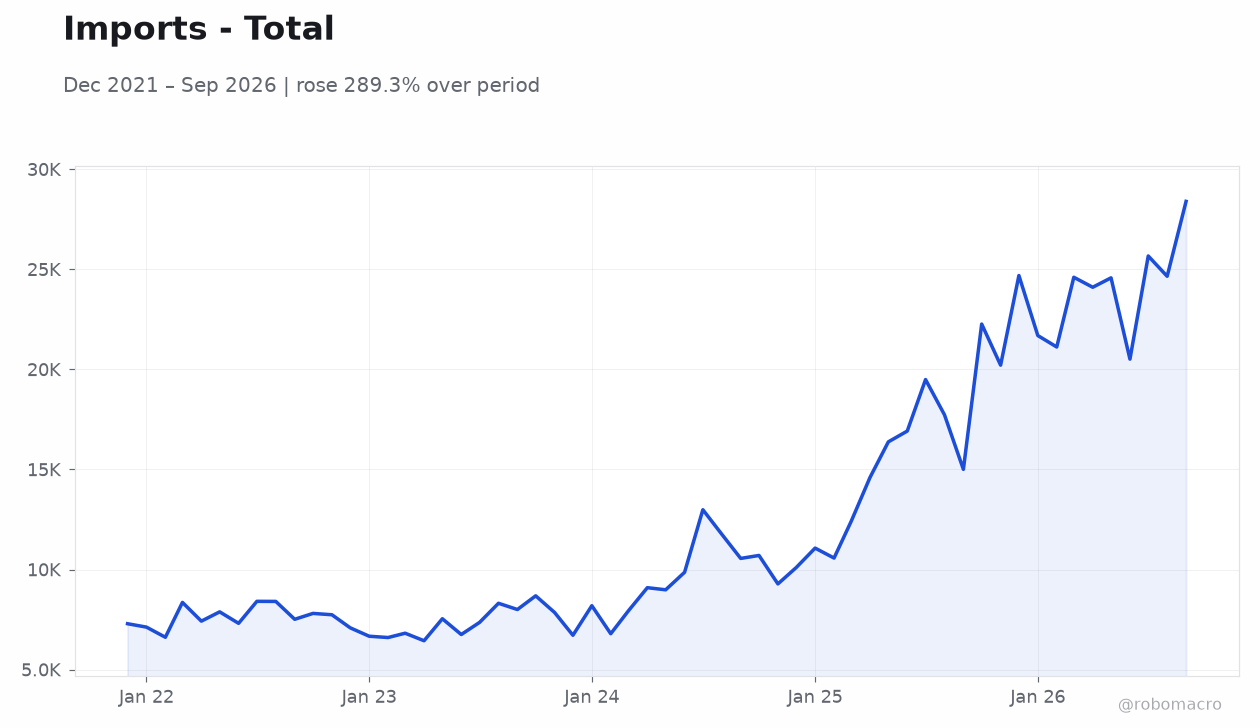
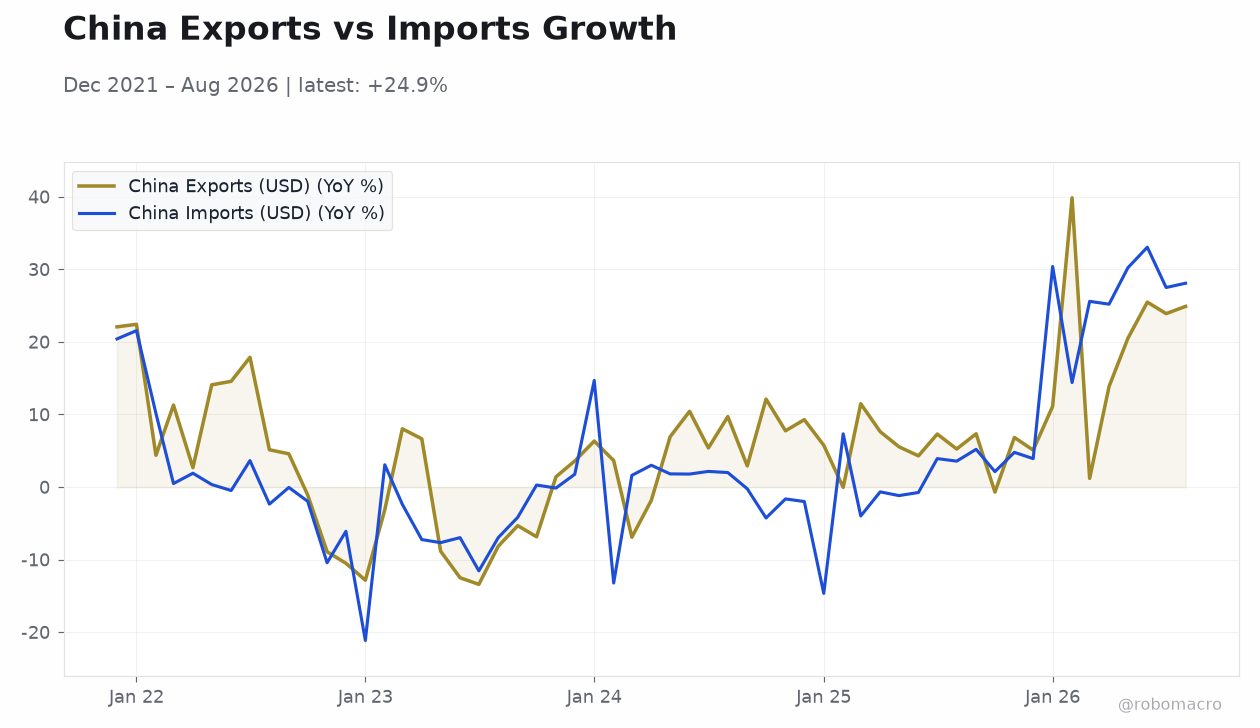 China Exports vs Imports Growth | Type: macro_line | China Exports (USD): 24.9 (2026-08-01) | Range: -13.41–39.85 | Trend(5pt): 22.08,-3.12,-1.835,4.3,24.9 | China Imports (USD): 28.09 (2026-08-01) | Range: -21.14–33.05 | Trend(5pt): 20.42,3.068,3.005,-0.7467,28.09
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
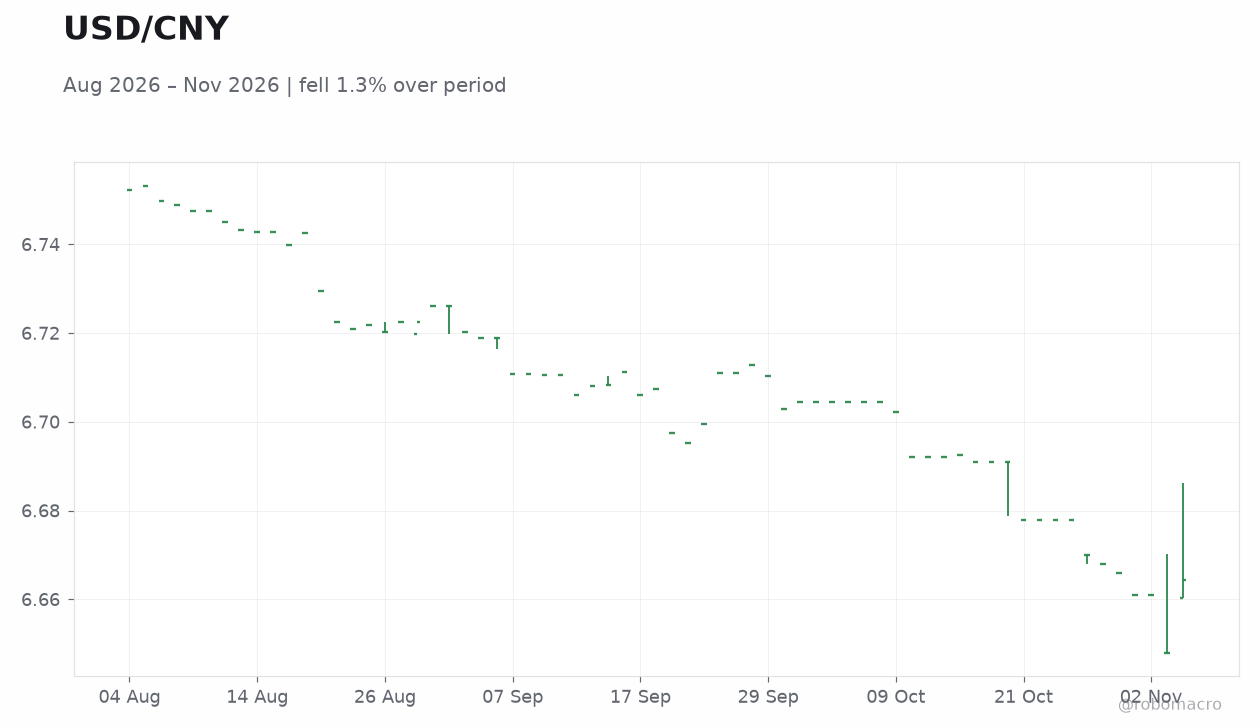
- PBoC raised the FX reserve requirement ratio to 6% to slow the yuan's rally, triggering the currency's sharpest daily decline in recent memory even as USD/CNY printed at 6.66.
- China's RatingDog Services PMI unexpectedly slipped to 50.8 in November from 51.6, the first deceleration since July, signaling softening business confidence.
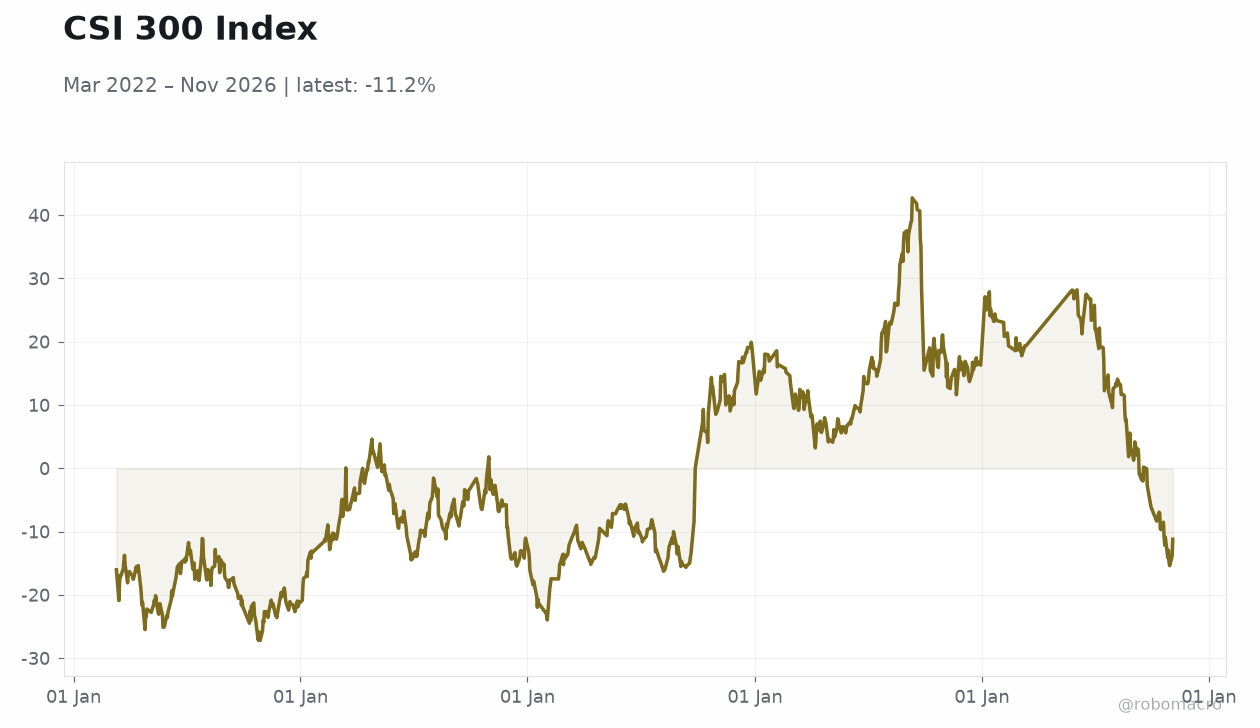
- Mainland equities defied the data weakness, with CSI 300 surging 2.31% and Shanghai Composite up 1.92%, while TAIEX plunged 3.59% on semiconductor-sector volatility.
Yesterday's Recap
Mainland China's private services gauge printed at 50.8 in November, down from 51.6 previously and below consensus of 51.5 — the first slowdown in services activity since July, pointing to easing business confidence as domestic demand remains fragile. The PBoC's decision to lift the FX reserve requirement ratio to 6% dominated FX markets, engineering a sharp yuan pullback after an extended appreciation run; USD/CNY settled at 6.66, up 0.25% on the day. Despite the softer data and currency adjustment, onshore equities rallied hard — the CSI 300 jumped 2.31% to 4,101.33 and the Shanghai Composite gained 1.92% to 3,677.55, suggesting investors read the FX move as a deliberate policy buffer rather than a distress signal.
Hong Kong's Hang Seng added a modest 0.57% to 23,525.97, with the city's Q3 GDP expanding 5.2% year-on-year supporting sentiment. Taiwan was the outlier, with TAIEX collapsing 3.59% to 43,307.54 amid semiconductor-sector profit-taking. In commodities, copper — a key China growth proxy — firmed 0.49% to 6.41, while Brent crude cratered 8.65% to 94.64 on demand concerns.
The Day Ahead
The Greater China calendar is empty for Wednesday, November 4, with no scheduled mainland, Hong Kong, or Taiwan data releases. Market attention will instead center on follow-through from the PBoC's FX reserve ratio adjustment and whether the yuan stabilizes near 6.66 or extends its retreat. Hong Kong's Global Financial Leaders' Investment Summit, hosted by the HKMA, continues to draw cross-border capital-flow headlines.
Taiwan traders will watch semiconductor supply-chain sentiment after TAIEX's sharp reversal. With no domestic prints to anchor positioning, Greater China assets will likely take their cue from overnight global risk appetite and commodity moves.
Other Economic Notes
Europe is increasingly targeting the yuan exchange rate as it seeks to curb China's low-cost export advantage, adding a trade-policy dimension to currency management just as Beijing faces twin pressures on exports and domestic demand. Vice Premier He Lifeng used Hong Kong's platform to urge the city to leverage its "One Country, Two Systems" framework to deepen openness to global trade, reinforcing Hong Kong's role as an offshore yuan hub. ↓ p.2