India Macro Daily(Beta Mode)
IP Surge Eases RBI Rate Cut Pressure
Market Snapshot
| Asset | Level | Change |
|---|---|---|
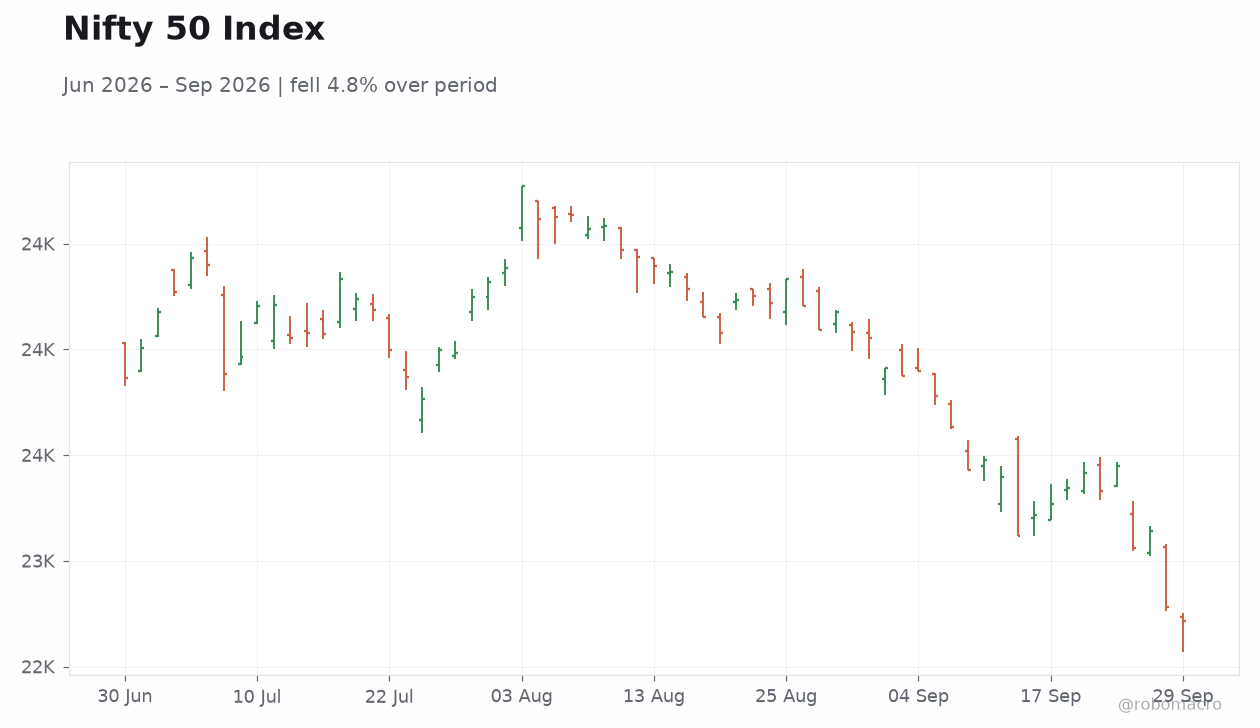
| Nifty 50 | 22,716.20 | -0.28% |
| Sensex | 72,529.07 | -0.33% |
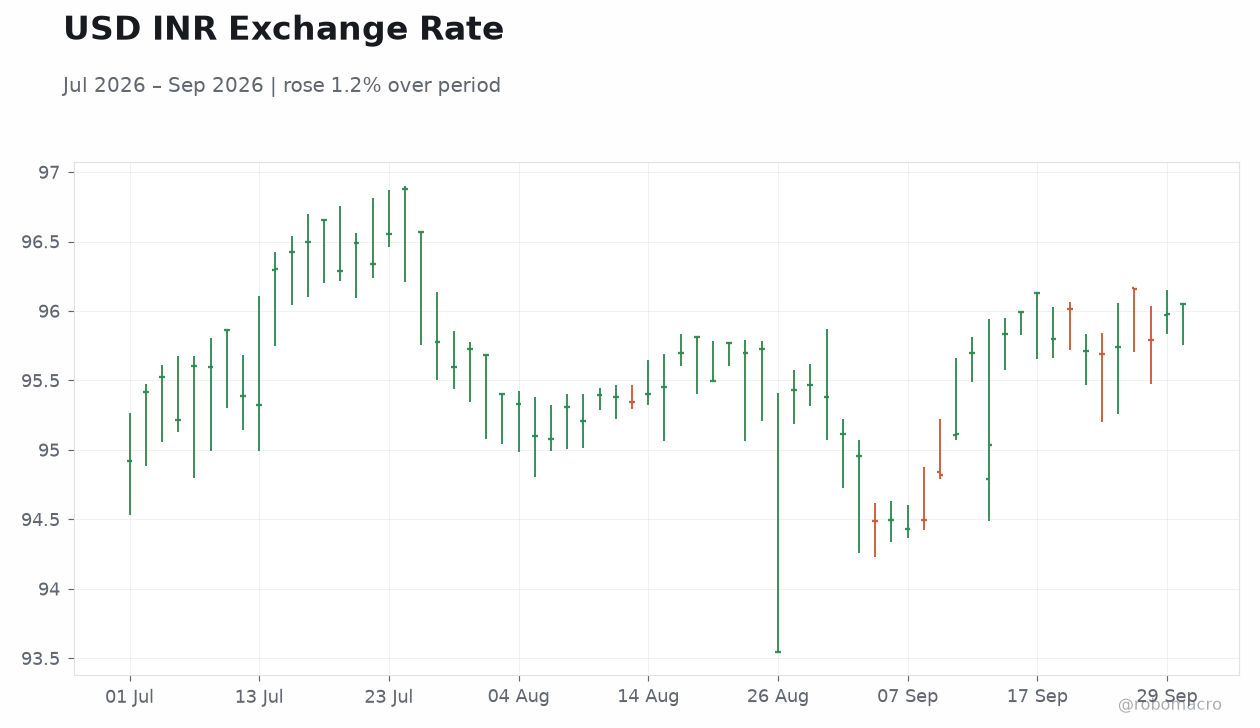
| USD/INR | 96.05 | +0.07% |
| EUR/INR | 108.77 | -0.27% |
| Reliance | 1,187.00 | +0.42% |
| HDFC Bank | 708.70 | -1.94% |
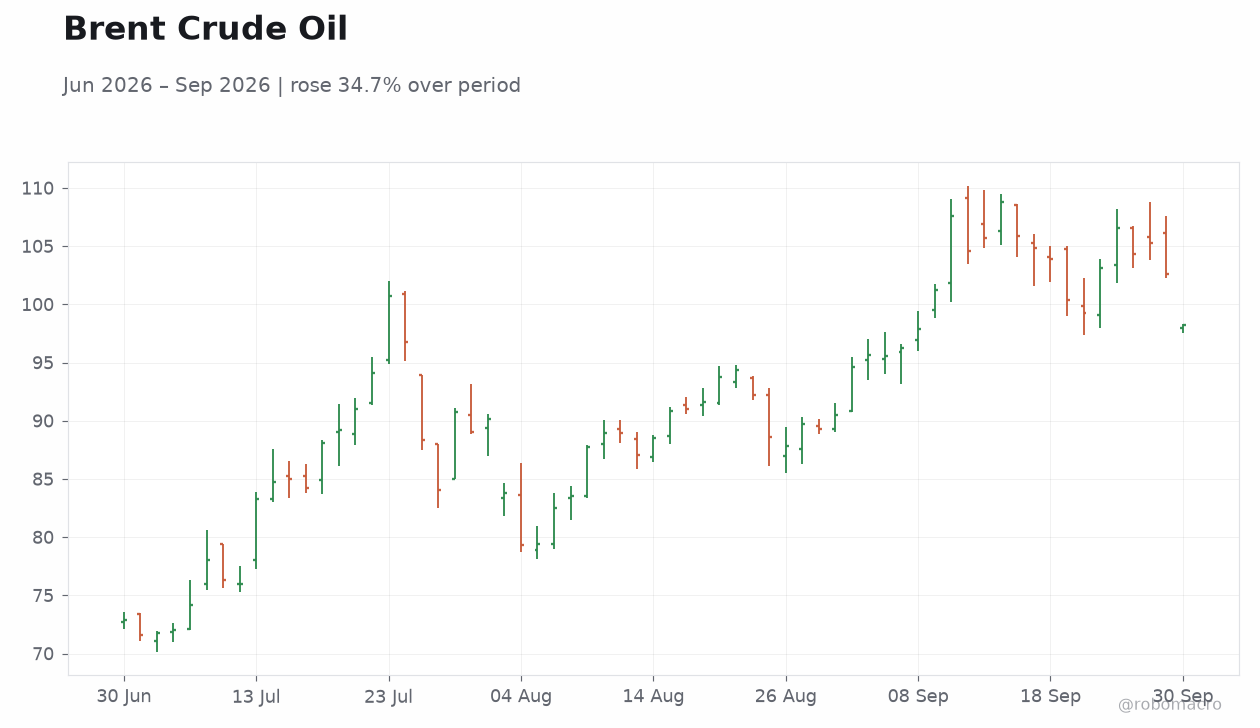
| Brent Crude | 98.19 | -4.29% |
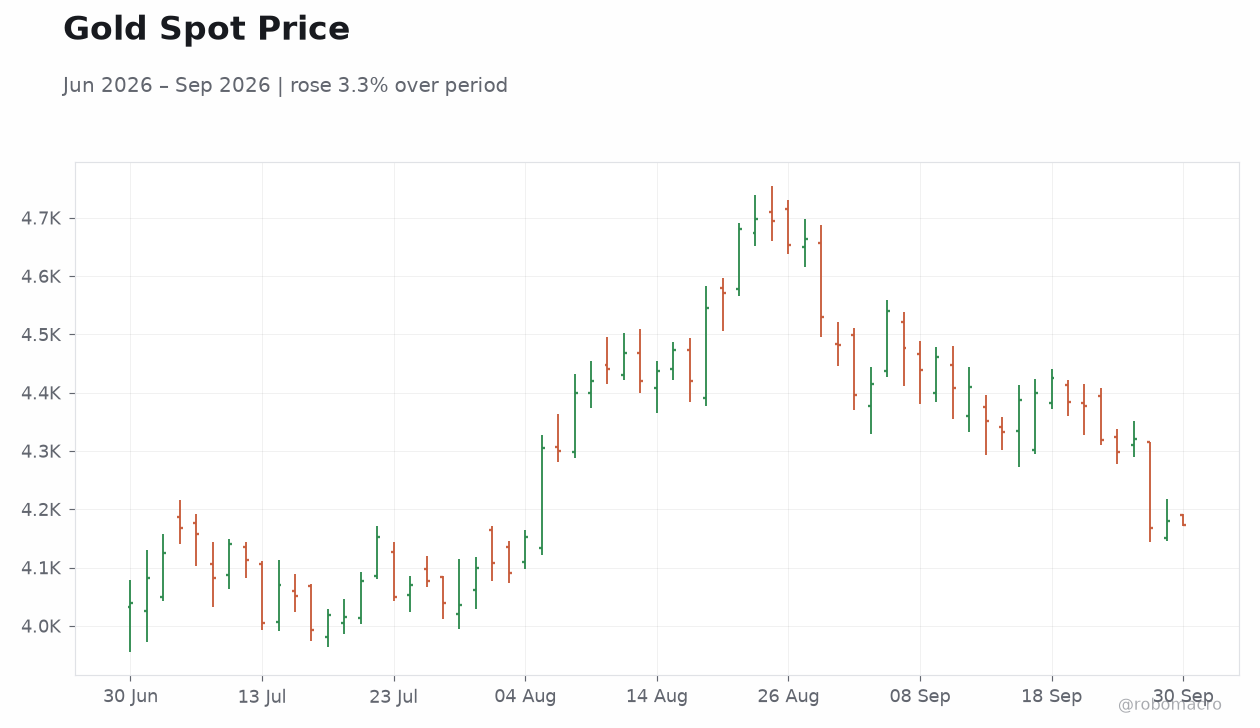
| Gold | 4,172.40 | -0.17% |
| Bitcoin | 83,407.08 | -0.26% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Industrial Production Year-over-Year | 6.70 | 6.50 | 8 |
| Manufacturing Production Year-over-Year | 7.30 | - | 9 |
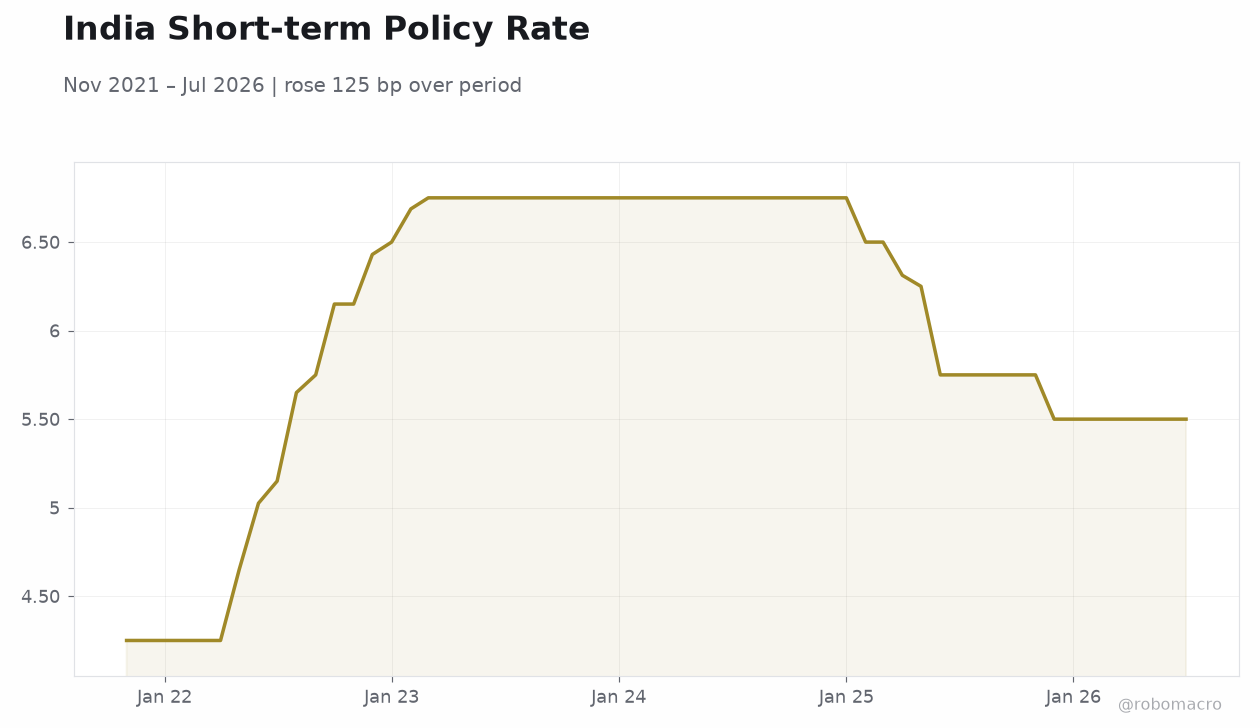 India Short-term Policy Rate | Type: macro_line | %: 5.5 (2026-07-01) | Range: 4.25–6.75 | Trend(5pt): 4.25,6.5,6.75,6.25,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Industrial production surges to 8% y/y, beating consensus
- RBI drains $20 billion liquidity through FX operations
- Nifty slips 0.28% while rupee holds near 96 amid debt rise
Yesterday's Recap
Industrial Production rose 8.0% y/y in August, exceeding the 6.5% consensus and prior 6.7% reading, while Manufacturing Production climbed 9.0% y/y from 7.3%. Equity markets closed lower with Nifty 50 at 22,716.20, down 0.28%, and Sensex at 72,529.07, down 0.33%. The rupee edged 0.07% weaker to 96.05 against the dollar as Brent crude fell 4.29% to 98.19.
India's external debt increased to $778.2 billion in the June quarter, according to RBI data. The central bank drained nearly $20 billion from surplus liquidity via foreign exchange operations, bond sales and reverse repos. Reliance Industries gained 0.42% while HDFC Bank declined 1.94%.
August indicators reflected firmer vehicle sales and narrower trade deficit alongside the industrial momentum.
The Day Ahead
No economic releases are scheduled for 30 September or 1 October, leaving markets to digest yesterday's industrial data and liquidity developments. Traders will monitor rupee movements near the 96 level for signs of further RBI intervention. Equity sentiment may hinge on global crude price trends after the sharp Brent decline.
Private capex and credit growth trends flagged by Kotak will stay in focus as stronger industrial prints support the growth narrative. Attention could also turn to any updates on external debt management or trade remedy actions.
Other Economic Notes
Crisil raised its FY27 GDP growth forecast to 7%, citing resilient domestic demand. Kotak highlighted limited near-term recovery in private capital expenditure and credit expansion despite the industrial rebound. August economic indicators showed gains in vehicle sales and credit growth alongside a narrower trade deficit, though geopolitical risks persist.
The rise in external debt to $778.2 billion underscores the need for careful external sector monitoring. These developments reinforce India's growth trajectory even as liquidity conditions tighten.
Global Macro News
Easing Brent crude prices supported a modest rupee rebound and reduced imported inflation pressures for India. Global brokerages increasingly expect the RBI to hike rates sooner than previously anticipated given persistent growth momentum. ↓ p.2